PDF 原檔:260824_ASIC展望_gfhk_asic-outlook-wrapup_original.pdf
已驗證圖片清單(Step 2.5)
共抽出 5 張,逐張 Read 全數驗證。
| 檔案 | 對應 Figure | 內容(親眼所見) | 分類 |
|---|---|---|---|
..._002.png |
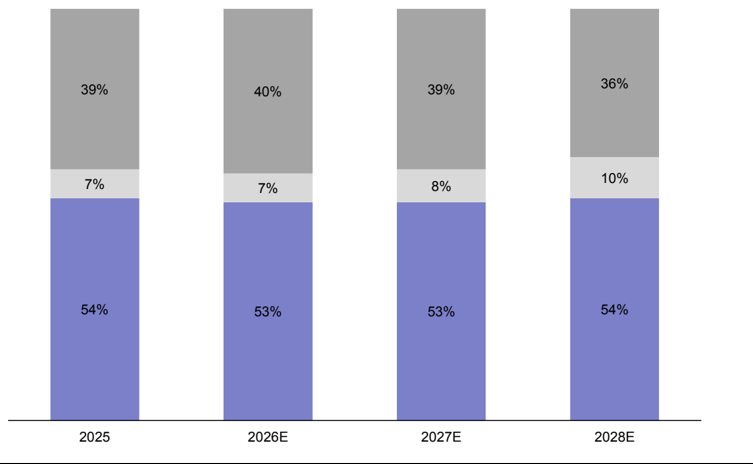
Figure 1 | TSMC CoWoS 消耗占比堆疊柱:NVIDIA GPU 54%/53%/53%/54%、AMD GPU 7%/7%/8%/10%、ASIC 39%/40%/39%/36%(2025/2026E/2027E/2028E) | ✅ 真資料圖 |
..._003.png |
Figure 2 | Google TPU 出貨量估計堆疊柱:2024 合計 2,760;2025E 2,854(舊世代 2,550+v7 Ghostfish 304);2026E 4,504(1,200+2,624+v8AX 180+v8x 500);2027E 8,840(1,520+3,720+3,600) | ✅ 真資料圖(⚠ 圖說寫 units mn,數值實為 k units) |
..._004.png |
Figure 3 | Meta ASIC 出貨量估計堆疊柱:2024 150、2025E 150、2026E 316(v1 Athena 300+v1.5 Iris 16)、2027E 640(400+ARKE 200+40) | ✅ 真資料圖(單位口徑同上待確認) |
..._005.png |
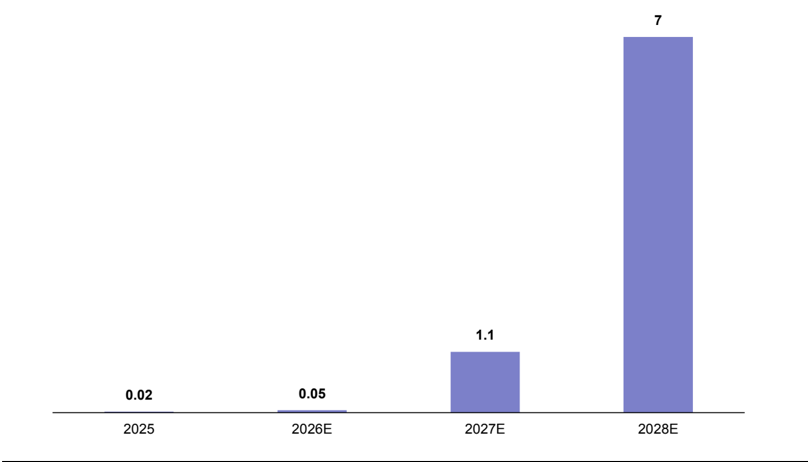
Figure 7 | Intel 後段(backend)營收預估:2025 0.02、2026E 0.05、2027E 1.1、2028E 7(US$bn) | ✅ 真資料圖 |
原始內容
ASIC Outlook Wrap-up - MTK, MRVL, Intel Firming
Jeff Pu, CFA
SFC CE No. BNO719
jeffpu@gfgroup.com.hk
Henry Huang
SFC CE No. BYA749
henryhuang@gfgroup.com.hk
What's New?
Following our recent earnings notes and supply chain research, we provide our view on major ASIC's volume and progress. We continue to like MRVL, MTK and Intel for the positive/intact outlook.
Comments
Nvidia vs. ASIC: Contrary to general perception, we still believe that Nvidia's share will remain stable in 2027, on CoWoS consumption basis at TSMC; together with AMD, we expect GPU share is on an increasing trend (figure 1). As said in our recent Nvidia Preview note on Aug 18 , we believe that Nvidia' Vera Rubin Platform is much ahead of its competitors in performance/TCO/supply chain and is gaining shares in major CSPs such as AWS/GOOG which even have their own ASICs.
TPU dynamics-prefer MTK (2454 TT Buy): We cut Broadcom's Sunfish volumes for 2026/27 on June 16 (our report of June Edition ) due to packaging re -design, and set 460k CoWoS (ASIC) in 2027. Shipments of Sunfish should begin in late -2026 with volume in 1Q27. For 2027, we keep Broadcom's 50k CoWoS estimate to Meta for Iris+ and ARKE, but highlight the difficulty in 2H27 of reallocating capacity back to TPU as MTK's Humufish ramps on N2 advantage. On the other hand, we keep MTK's Zebrafish volumes unchanged at 25k/180k CoWoS for 2026/27. However, investor feedback suggests MTK is more like a funding -short stock amid concerns over Humufish tape -out, Google's slower AI model progress and worries over AMD/MRVL. However, we expect the engineering tape -out to be around Nov-2026, with Google/MTK committing meaningful resources and a manageable pass -rate bar. We continue to prefer MTK over Broadcom.
Google attach silicon-prefer MRVL (Buy): As said in our MRVL report on Aug 20 , we continue to see meaningful contribution from Google's silicon-CXL, DPU, and MPU. We expect ~$3bn each from CXL and DPU by 2028. For MPU, optimized for token generation, we model a 2Q28 start on TSMC N2 and conservatively estimate ~$3bn CY28 revenue. We also view Google's equity partnership as increasing MRVL's chances of securing TPU v10 (Merope) in 2H28. This won't impact MTK, in our view, given that the Icefish engagement already confirmed.
AWS T3/T4-prefer MRVL (Buy) and SMTC (Buy): We continue to expect Marvell to participate in Trainium 3, contributing roughly $1bn/$2bn in CY26/27. For Trainium 4, given the design of NPO scale -up for UALink/NVLink, we believe that Marvell's strengthened scale -up optical networking position post -Celestial AI will lead to an enhanced allocation share, vs. its competitors. Together with a much higher ASP, we expect >$3bn revenue contribution of T4 to MRVL in CY28. For NPO, we expect 6.4T OE to be the primary specs for T4. We forecast AWS will consume 5m/12m OE units for Trainium 4 in 2H27E/2028E. We forecast global OE units to be 11m/40m at optical component's level and like SMT (Buy) for its 2 nd supplier position.
ASIC packaging-prefer Intel (Buy) and ABF substrate names: Per our Intel note on Aug 14 , we raised our back -end revenue forecast to $1.1bn/$7bn in FY27/FY28, supported by better visibility on AWS T3 for EMIB -T in 2027 and major Google Humufish/Triggerfish volumes through 2H27-2028. Looking ahead, we see a path with high likelihood to win back-end business from U.S. fabless including MSFT, QCOM, MRVL, with products across ASIC, CPU and CPO. On supply, we expect ABF substrate to greatly benefit from EMIB.
Risks: 1) AI demand slowdown, 2) infrastructure deployment, 3) supply constraints, 4) competition.
Focus Charts
Figure 1: GPU, vs. ASIC's CoWoS share at TSMC
Nvidia GPU AMD GPU ASIC
Sources: Company data, GF Securities (Hong Kong) Brokerage
Figure 2: Google TPU volume estimates (units mn)
Old gen v7 (Ghostfish) v8AX (Sunfish/Hellcat) v8x (Zebrafish/Maddog)
Sources: Company data, GF Securities (Hong Kong) Brokerage
Figure 3: Meta ASIC volume estimates (units mn)
Old gen
v1 (Athena)
v1.5 (Iris)
ARKE
Total
Sources: Company data, GF Securities (Hong Kong) Brokerage
Figure 4: Google TPU Roadmap
| TPU v7 Ironwood | TPU 8i | TPU 8t | TPU v9t | TPU v9t+ | TPU v9i | TPU v10t | |
|---|---|---|---|---|---|---|---|
| Code name | Ghostfish | Sunfish | Zebrafish | Humufish | Triggerfish | Whalefish | Icefish |
| Time | 4Q25 | 4Q26 | 4Q26 | 4Q27 | 4Q27 | 1Q28 | 4Q28 |
| Design Service - Compute | BRCM | BRCM | GOOG | GOOG | GOOG | BRCM | GOOG |
| Design Service - I/O | BRCM | BRCM | MTK | MTK | MTK | BRCM | MTK |
| Design Service - back-end | BRCM | BRCM | MTK | MTK | MTK | BRCM | GOOG or MTK |
| Compute | 2*N3E | 2*N3P | 1*N3P | 4*N2P | 4*N2P | 2*N3P | A14/N2P8+ N2P16 |
| I/O | 1*N5 | 1*N4 | 1*N4P | 4*N3P | 4*N3P | 2*N4 | N2P*6 |
| Memory | 8*HBM3e | 8*HBM3e | 6*HBM3e | (6*HBM4 8Hi) | (6*HBM4e 8Hi) | (6*HBM4e 8Hi) | 16*HBM5 |
| Memory spec | 192GB | 288GB | 216GB | 288GB | 384GB | 384GB | |
| Memory BW (TB/s) | 7.4 | 8.6 | 6.5 | ||||
| Back-end | CoWoS-S | CoWoS-L | CoWoS-S | EMIB-T | EMIB-T | CoWoS-S/SOIC | EMIB-T or CoWoS |
Sources: Company data, GF Securities (Hong Kong) Brokerage
Please be sure to read the disclosures at the end of this report carefully.
Figure 5: Meta ASIC Roadmap
| MTIA 300 | MTIA 400 | MTIA 400+ | MTIA 450 | MTIA 500 | |
|---|---|---|---|---|---|
| Code name | Athena Iris | Plus | Iris Plus+ | ARKE | Astrid |
| Time | 2Q26 | 2Q26 | 3Q26 | 1Q27 | 3Q27 |
| Design Service - compute | BRCM | BRCM | BRCM | BRCM | BRCM |
| Design Service - I/O | BRCM | BRCM | BRCM | BRCM | BRCM |
| Design Service - back-end | BRCM | BRCM | BRCM | BRCM | BRCM |
| Compute | 1*N3E | 1*N3 | 2*N3 | 1*N2 | N2 |
| I/O | 2*N4 | 2*N4 | 2*N3 +1 N3 SoC | 2*N3 +1 N3 SoC | N3 |
| Memory | 6*HBM3e 12Hi | 6*HBM3E 12Hi | 8*HBM3E 12Hi | 8*HBM4 12Hi | 8*HBM4 12Hi |
| Memory spec | 216GB | 216GB | 288GB | 288GB | 384GB |
| Memory BW (TB/s) | 6.1 | 9.2 | 9.2 | 12.8 | TBD |
| TDP (W) | 800 | 1000 | 1200 | 1400 | TBD |
| Back-end | CoWoS-S | CoWoS-L | CoWoS-L | CoWoS-L | CoWoS-L |
Sources: Company data, GF Securities (Hong Kong) Brokerage
Figure 6: NPO OE shipment forecast
| 2027 | 2028 | |
|---|---|---|
| Market for Nvidia's scale up 3.2T NPO (k units) | ||
| Rubin Ultra chip for NVL576(m units) | 1.0 | 6 |
| NPO Penetration rate | 60% | 95% |
| OE per GPU/switch ASIC | 4 | 4 |
| OE | 2.3 | 22.8 |
| Considering pull-in | 6 | 19 |
| Market for AWS's scale up 6.4T NPO (k units) | ||
| Trainium 4 in total (m units) | 0.8 | 4.5 |
| NPO Penetration rate | 80% | 80% |
| Trainium 4 for Scale Up (m units) | 0.6 | 3.6 |
| OE per GPU/switch ASIC | 4 | 4 |
| OE | 2.6 | 14.4 |
| Considering pull-in | 5 | 12 |
| Market for Other CSPs' scale up NPO (k units) | ||
| OE | 9.0 | |
| Market for Total scale up NPO (k units) | ||
| Total | 4.8 | 46.2 |
| Considering pull-in | 11 | 40 |
Sources: Company data, GF Securities (Hong Kong) Brokerage
Please be sure to read the disclosures at the end of this report carefully.
Figure 7: Intel's backend revenue forecast (USD bn)
Sources: Company data, GF Securities (Hong Kong) Brokerage
Risks
- 1) AI demand slowdown, 2) infrastructure deployment, 3) supply constraints, 4) competition.
Rating definitions
Benchmark: Hang Seng Index (Hong Kong)
Company ratings Buy
Stock expected to outperform benchmark by more than 10 %
Hold
Expected stock relative performance ranges between -10% and 10%
Underperform
Stock expected to underperform benchmark by more than 10%
Sector ratings
Positive
Sector expected to outperform benchmark by more than 10%
Neutral
Expected sector relative performance ranges between -10% and 10%
Cautious
Sector expected to underperform benchmark by more than 10%
Hong Kong Company
GF Securities (Hong Kong) Brokerage Limited
Address
27/F, GF Tower, 81 Lockhart Road, Wan Chai, Hong Kong
Telephone
(852) 37191111
evanlee @gfgroup.com.hk