PDF 原檔:報告_MS_OCP峰會2026硬體總結_20261018_original.pdf
圖片清單(已驗證 2026-10-19)
| 檔名 | 分類 | 親眼所見內容 |
|---|---|---|
| 報告_MS_OCP峰會2026硬體總結_20261018_001.png | 真資料圖 | 實拍:Edgecore(Accton)液冷 1.6T 交換器開蓋內部,可見冷板與水管(Exhibit 1) |
| 報告_MS_OCP峰會2026硬體總結_20261018_002.png | 真資料圖 | 實拍:Accton/Edgecore AIS1600-64O-FL2L 規格牌:Broadcom Tomahawk 6、102.4Tbps、64 x 1.6T OSFP RHS、AMD V3C48 COM Express CPU 模組、2U 全液冷(Exhibit 2) |
| 報告_MS_OCP峰會2026硬體總結_20261018_003.png | 真資料圖 | 實拍:Credo「1.6T ZeroFlap AEC」展台,紫色 AEC 線纜接測試板與監控畫面(Exhibit 3) |
| 報告_MS_OCP峰會2026硬體總結_20261018_004.png | 真資料圖 | 實拍:Credo「ZeroFlap PCIe Gen6 AEC」展台,藍色線纜與遙測畫面(Exhibit 4) |
| 報告_MS_OCP峰會2026硬體總結_20261018_005.png | 真資料圖 | 簡報照:OCP 簡報頁「CPO: Benefits and Deployment Considerations」,左欄 CPO 優點(較短高速電通道、較低電 I/O 與 retimer 功耗、較高頻寬密度),右欄系統取捨(封裝複雜、測試需求、現場可維修性下降、爆炸半徑大、元件與供應商鎖定)(Exhibit 5) |
| 報告_MS_OCP峰會2026硬體總結_20261018_006.png | 真資料圖 | 簡報照:「NPO has become the preferred short-term option for scaling up optical interconnects」,含 NPO 結構剖面(ASIC、光引擎、可插拔式連接器、光纖)與四項優點(可維護、開放解耦、可得性、產業實作成熟)(Exhibit 6) |
| 報告_MS_OCP峰會2026硬體總結_20261018_007.png | 真資料圖 | 實拍:Molex「448G Impress CPC to Insite Backplane」展示,透明盒內 CPC 纜線與連接器(Exhibit 7) |
| 報告_MS_OCP峰會2026硬體總結_20261018_008.png | 真資料圖 | 實拍:TE Connectivity CPC 伺服器托盤內部,銅纜自前面板連至晶片,紅藍水管為液冷(Exhibit 8) |
| 報告_MS_OCP峰會2026硬體總結_20261018_009.png | 真資料圖 | 實拍:Open CPX MSA 的 Co-Packaged Optics Evaluation Kit 板,標示 Samtec/Ciena 等 CPX 連接器(Exhibit 9) |
| 報告_MS_OCP峰會2026硬體總結_20261018_010.png | 真資料圖 | 實拍:Ciena Vesta CPX 板,四個 CPX 模組插座(Exhibit 10) |
| 報告_MS_OCP峰會2026硬體總結_20261018_011.png | 真資料圖 | 實拍:Alpha Networks 交換器開蓋,標示 Open CPX MSA,前面板綠色光連接器(Exhibit 11) |
| 報告_MS_OCP峰會2026硬體總結_20261018_012.png | 真資料圖 | 實拍:Astera Labs「PCIe over VCSEL NPO」展示(Scorpio smart fabric switch 驅動),螢幕顯示眼圖「RX Eyes in spec/BER 1e-12 or better」,機內可見 Lumentum、Corning 標示(Exhibit 12) |
| 報告_MS_OCP峰會2026硬體總結_20261018_013.png | 真資料圖 | 實拍:PCIe over VCSEL NPO 托盤俯視,黃色載板、散熱模組與水管(Exhibit 13) |
| 報告_MS_OCP峰會2026硬體總結_20261018_014.png | 真資料圖 | 實拍:Credo ALC(Active Light Cable)紫色線纜與兩端模組,背景可見 ams OSRAM 等標示(Exhibit 14) |
| 報告_MS_OCP峰會2026硬體總結_20261018_015.png | 真資料圖 | 實拍:Credo ALC 的 NPO 配置,SENKO 標示的光纖連接器圍繞散熱蓋板(Exhibit 15) |
| 報告_MS_OCP峰會2026硬體總結_20261018_016.png | 真資料圖 | 實拍:貿聯 shuffle box 展示,MPO 光纜分流到兩個光模組,標示 MM-MPO/SM-MPO(Exhibit 16) |
| 報告_MS_OCP峰會2026硬體總結_20261018_017.png | 真資料圖 | 簡報照:BizLink「Optical Interconnect Inspection, Metrology and Validation Capabilities」,列檢測與計量、FAU 製程(PMF 對準、雷射切割研磨、間距轉換)、光學性能驗證,附兩台量測設備(Exhibit 17) |
| 報告_MS_OCP峰會2026硬體總結_20261018_018.png | 真資料圖 | 簡報照:台達「480 VAC vs 800 VDC」比較,480VAC 電效率約 93%(4 個轉換級)對 800VDC 約 95%(3 個轉換級)(Exhibit 18) |
| 報告_MS_OCP峰會2026硬體總結_20261018_019.png | 真資料圖 | 簡報照:台達「What Does That Mean in Dollars?」,100MW IT 負載、電價 $0.08/kWh、2 點效率差,年省約 19,800 MWh、約 $1.6M/年,10GW 約 $160M/年(Exhibit 19) |
| 報告_MS_OCP峰會2026硬體總結_20261018_020.png | 真資料圖 | 簡報照:台達「800 VDC Equipment Readiness」路線圖:Option A Power Rack(Q3 2026)、Option B Power Center(Q2 2027)、Option C Power Block(Q1 2028),下列五項就緒度(Exhibit 20) |
| 報告_MS_OCP峰會2026硬體總結_20261018_021.png | 真資料圖 | 簡報照:台達「Option A: Edge Inference Upgrade」,1 座 800VDC Power Rack 搭 2 座 VR NVL72 運算機櫃,660kW、415-480VAC 輸入、800VDC 輸出(Exhibit 21) |
| 報告_MS_OCP峰會2026硬體總結_20261018_022.png | 真資料圖 | 簡報照:Megmeet「The Next Evolution in Cooling」,氣冷 3U 電源 shelf 對 2U 100% 液冷 110kW shelf,附液冷洩漏保護、元件壽命說明(Exhibit 22) |
| 報告_MS_OCP峰會2026硬體總結_20261018_023.png | 真資料圖 | 簡報照:Megmeet「Fan Cooled vs. Liquid Cooled Infrastructure」,傳統氣冷電源 shelf 對全液冷電源 shelf+運算托盤,標示可省約 10% 設施 CAPEX(Exhibit 23) |
| 報告_MS_OCP峰會2026硬體總結_20261018_024.png | 真資料圖 | 實拍:NVIDIA MGX 800 VDC 固態變壓器 Cell 展示區,可見 DG Matrix、SUNGROW、SolarEdge、台達(機櫃上方模組)等設備(Exhibit 24) |
| 報告_MS_OCP峰會2026硬體總結_20261018_025.png | 真資料圖 | 資料圖:左為資料中心功率規模演進(AI 前 5-10MW、今日 100-250MW、2026+ 約 650MW、2029 GW 級)與三種架構(LFT+AC-DC sidecar、SST 設施級 800V 微電網);右為 SST 對傳統變壓器:效率提升 2-5 ppt、空間與重量至少少 30%(Exhibit 25、26) |
| 報告_MS_OCP峰會2026硬體總結_20261018_026.png | 真資料圖 | 資料圖:Infineon 簡報,傳統變壓器約 20 噸、市場 >USD 15bn 對 SST 約 500kg(約 40x 輕、14x 小),預期 2030 年 >USD 1bn;列 Delta、DG Matrix、SolarEdge 為早期參與者(Exhibit 27) |
| 報告_MS_OCP峰會2026硬體總結_20261018_027.png | 真資料圖 | 股價與目標價歷史走勢圖(紅虛線為目標價;末值 3665,對應貿聯 3665.TW);屬股價圖,不嵌入 lib |
| 報告_MS_OCP峰會2026硬體總結_20261018_028.png | 真資料圖 | 股價與目標價歷史走勢圖(目標價末值 2800,股價末端約 2,000,對應致茂 2360.TW);屬股價圖,不嵌入 lib |
| 報告_MS_OCP峰會2026硬體總結_20261018_029.png | 真資料圖 | 股價與目標價歷史走勢圖(目標價末值 2500、前一階段 2700,股價末端約 1,650,對應台達電 2308.TW);屬股價圖,不嵌入 lib |
| 報告_MS_OCP峰會2026硬體總結_20261018_030.png | 真資料圖 | 股價與目標價歷史走勢圖(目標價末值 315,前一階段 176,股價末端約 265,對應光寶科 2301.TW);屬股價圖,不嵌入 lib |
原始內容
| Morgan Stanley Taiwan Limited+ Derrick Yang Equity Analyst D rrick.Yang@morganstanl y.com | +886 2 2730-2862 |
|---|---|
| Vivi Huang R s arch Associat Vivi.Huang@morganstanl y.com | +886 2 2730-2860 |
| Morgan Stanley Asia Limited+ Andy Meng, CFA Equity Analyst Andy.M ng@morganstanl y.com | +852 2239-7689 |
Greater China Technology Hardware
Asia Pacific Industry View In-Line
Morgan Stanley does and seeks to do business with companies covered in Morgan Stanley Research. As a result, investors should be aware that the firm may have a conflict of interest that could affect the objectivity of Morgan Stanley Research. Investors should consider Morgan Stanley Research as only a single factor in making their investment decision.
For analyst certification and other important disclosures, refer to the Disclosure Section, located at the end of this report.
= Analysts employed by non-U.S. affiliates are not registered with FINRA, may not be associated persons of the member and may not be subject to FINRA restrictions on communications with a subject company, public appearances and trading securities held by a research analyst account.
M Idea October 18, 2026 09:54 PM GMT
Greater China Technology Hardware | Asia Pacific 2026 OCP Global Summit
Takeaways
CPO/NPO and micro VCSE based optical solutions are the focus for networking, while HVDC takes center stage for power.
Higher bandwidth and better power efficiency: In the networking space, the migration into higher bandwidth continues, as p ayers ike Accton and Ce estica showcased their 1.6T network switches. We think a bigger theme is the effort to improve the power efficiency of current mainstream p uggab e optica so utions. First off, one we -discussed approach is the adoption CPO or NPO, and it seems the atter is gaining more attention due to the technica cha enges in the former. Spec standardization, such as CPX connectors, cou d further acce erate the pro iferation, in our view. Second y, copper cou d sti he p, as Credo has its 1.6T AEC cab es for inter-tray transmission whi e many other vendors (Ampheno , TE Connectivity, Mo ex, etc.) have their 448G CPC so utions for in-tray transmission. Last y, the micro VCSEL based optica modu es from Credo and ALAB represent another power efficient so ution (12W/end at 1,6T), which has re iabi ity comparab e to copper (100M hours of MTBF/MTBI) for a transmission distance of 50-100m. We be ieve this micro VCSEL based so ution cou d potentia y rep ace the AEC for shorter distance transmission when copper hits the physica imit in the medium term and be integrated with the CPO architecture in the onger term. In sum, we be ieve the above-mentioned so utions are ike y to co-exist for different use cases.
800VDC for power delivery taking the center tage: Whi e the Vera Rubin NVL72 rack a ready has the in-rack power she f reference design (110KW/she f at 3+1 redundancy), Nvidia unvei ed another reference design this time, using one 660KW 800VDC power rack to support two Vera Rubin NVL72 racks. Moreover, we a so saw a few ±400VDC reference designs as we . Our conversations with companies on the exhibition f oor indicate that the HVDC adoption shou d start from ate 2026, but ike y at a sma sca e extending into 2027. The next checkpoint wi be Vera Rubin U tra racks, where increasing power consumption and more hardware devices for inter-rack sca e-up network might take up more pace on the rack, though the iquid coo ed power she f shou d ease the space budget a bit. We be ieve both so utions are progressing and wi c ose y monitor the dynamics.
Stock pick : We be ieve that Bizlink (3665.TW) shou d be a beneficiary of the pro iferation of the micro VCSEL based optica so ution, as it is the assemb y partner for Credo and potentia y others as we . Chroma (2360.TW) shou d see drivers from power testing, CPU/GPU/TPU SLT/FT, and photonics testing (p uggab e/ CPO)too s. Delta( (2308.TW) and Lite-On (2301.TW) shou d continue to grow with the increasing power consumption of AI c usters, but more meaningfu growth upside probab y wi depend on the penetration of HVDC power racks.
M Idea
2026 OCP Global Summit
Networking dealing with higher bandwidth and better power efficiency
1.6T network switch and 1.6T transcei er/AEC
CPO remains one of the focus in the networking space during the OCP G oba Summit. Edgecore and Ce estica showcased its 1.6T network switches based on Tomahawk 6 ASIC, both for the regu ar mode and the CPO mode . Moreover, Edgecore a so had its OCS switch mode in the booth, which is based on its own LCOS techno ogy. These demonstrate that both have the capabi ity to accommodate the customer demand for network switches based on the optica architecture in the future.
On the cab e side, Credo showcased its 1.6T AEC, but did not comment on the roadmap of its 3.2T AEC. Our checks in the exhibition with industry p ayers indicate that the 3.2T AEC might be a very cha enging project, though efforts are sti in p ace.
Exhibit : Edg cor - 1.6T liquid cool d n twork switch
Exhibit 2: Edg cor - 1.6T liquid cool d switch sp c
Sourc : Morgan Stanl y R s arch Sourc : Morgan Stanl y R s arch M Idea Sourc : Morgan Stanl y R s arch Sourc : Morgan Stanl y R s arch
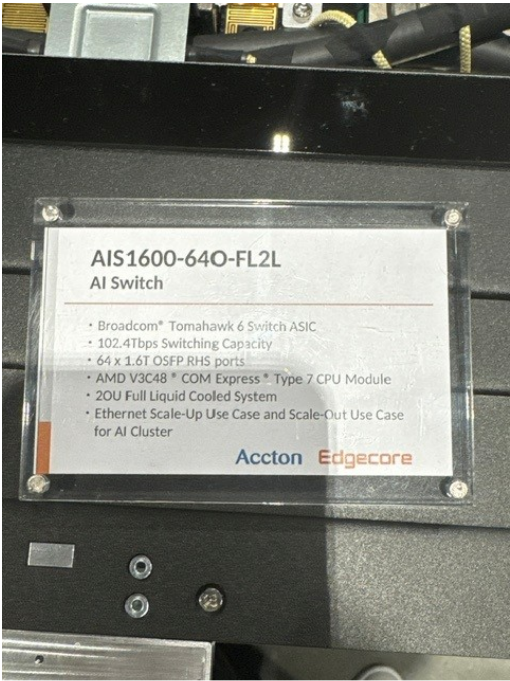
Exhibit 3: Cr do - 1.6T AEC
Exhibit 4: Cr do - PCIE G n 6 AEC
CPX and NPX all marching forward
Though CPO remains as the ho y grai in the space, its yie d issue and ower serviceabi ity sti present cha enges to the wider adoption in the near term. We be ieve that the efforts wi continue, but the industry is simu taneous y pursuing other more practica so utions to sort out the power consumption issue of the existing p uggab e transceivers, inc uding NPO (near-packaged optics), CPC (co-packaged copper) and NPC (near-packaged copper)
Compared to CPO, NPO compromises on the power consumption, but in exchange it eases the stringent requirement on a ignment and serviceabi ity. Given its better techno ogy readiness and more mature supp y chain, we think it might see good traction in the coming years.
M Idea
Exhibit 5: CPO - pros and cons
Exhibit 6: NPO - advantag s
Sourc : Nvidia
Exhibit 7: Mol x- CPC
Sourc : Huaw i
CPC is a so becoming a popu ar design in the networking space. Whi e the 448G server copper ane is imited to ess than 1m of effective transmission distance, it sti fits we into the use case of intra tray interconnects. We have seen many supp iers showcase the adoption of CPC for between the front pane and chip.
Exhibit 8: TE Conn ctivity - CPC
Sourc : Morgan Stanl y R s arch
Sourc : Morgan Stanl y R s arch
Besides, the initiative at Open CPX MSA is aiming at standardizing the connectors that cou d enab e a p uggab e architecture for CPO/CPC, though we think the structure ooks M Idea more ike NPO/NPC.
Samtec's SI-FLY and Ciena's Vesta are both manufactured based on the CPX spec. moreover, A pha Networks had a switch based on this CPX enab ed p uggab e optica modu es
We be ieve this cou d further improve the serviceabi ity of the NPO/NPC.
Exhibit 0: Ci na - V sta CPX
Exhibit 9: Samt c - SI-FLY CPX
Sourc : Morgan Stanl y R s arch Sourc : Morgan Stanl y R s arch M Idea Sourc : Morgan Stanl y R s arch
Exhibit : Alpha N tworks - CPX in n twork switch
VCSEL based optical solutions gaining more attention
In addition to CPO/NPO/CPC/NPC designs, we see the micro VCSEL based optica so utions are gaining more attention too. The va ue proposition is to everage the wide and s ow architecture for a re ative y short transmission distance of 50-100m. It can achieve 1-2 pJ/bit of power consumption vs. 5-10pJ/bit for CPO and NPO architecture. The current generation can enab e 32Gbps of bandwidth per ane and the 100-200Gbps of bandwidth per ane is in the roadmap.
M Idea
Exhibit 2: ALAB - PCIE ov r VCSEL NPO
Exhibit 3: ALAB - PCIE ov r VCSEL NPO
Sourc : Morgan Stanl y R s arch Credo is among one of the most aggressive promoters of this emerging architecture. It has been ta king about its ALC cab e for mor ethan one year, and this time we saw more concrete specs of its 1.6T ZeroF ap ALC, which comes in at the power consumption of 12W/end to support 50m of transmission distance with the copper eve re iabi ity (100m hours of MTBF/MTBI)
Sourc : Morgan Stanl y R s arch
M Idea
Exhibit 4: Cr do - ALC cabl
Sourc : Morgan Stanl y R s arch Sourc : Morgan Stanl y R s arch Biz ink is another active p ayer in the micro VCSEL optica modu e space. It has been partnering with Credo for many years in the AEC cab e assemb y and we be ieve that it wi a so co aborate with Credo on its ALC cab e. Back in ate September 2026, Biz ink had announced to partner with ams-OSRAM on the micro VCSEL based optica modu e (see the report). Longer term, we be ieve that these initiatives, a ong with the shuff e box and FA a ignment process, shou d he p its diversify its data interconnect exposure more into the optica space, vs. current concentration on copper.
Exhibit 5: Cr do - ALC in NPO configuration
M Idea
Exhibit 6: Bizlink - shuffl box
Sourc : Morgan Stanl y R s arch Sourc : Bizlink In sum, different so utions of data transmission are emerging, trying to improve the power consumption of the current y mainstream p uggab e transceivers. We be ieve that these so utions wi probab y co exist for a whi e, as different use case cou d need different combination of cost and benefits.
Exhibit 7: Bizlink - FAU alignm nt and validation
Power becoming another bottleneck in the AI deployment
HVDC adoption emerging from Vera Rubin
In the power space, HVDC has been one of the key focuses in the AI c uster, as the rapid increase in AI rack power density is creating growing cha enges for conventiona powerdistribution architectures. As rack- eve power consumption rising from tens of ki owatts to severa hundreds of KWs, e ectrica osses, cab e size, therma management requirements, and overa system comp exity increase significant y. Under traditiona owvo tage power architectures, de ivering arger amounts of power requires proportiona y higher current, which increases resistive osses and p aces greater stress on cab es, connectors, busbars, and power-conversion equipment.
At the same time, every power-conversion stage introduces efficiency osses and generates additiona heat. As AI dep oyments sca e into mu ti-megawatt and eventua y gigawatt- eve campuses, even sma efficiency improvements can trans ate into M Idea meaningfu reductions in operating costs, coo ing requirements, and infrastructure investment. Consequent y, the industry is increasing y focused on power architectures that can reduce conversion stages, ower current eve s, and improve overa powerde ivery efficiency.
Against this backdrop, high-vo tage direct current (HVDC) is emerging as one of the most important architectura upgrades for next-generation AI infrastructure. By increasing distribution vo tage, HVDC a ows the same amount of power to be de ivered at a ower current, reducing conduction osses and improving system efficiency. Higher-vo tage architectures a so improve sca abi ity for u tra-high-density rack dep oyments by a eviating some of the physica and therma constraints associated with conventiona power-distribution systems.
Exhibit 8: B tt r pow r ffici ncy for 800VDC archit ctur
Exhibit 9: B tt r ffici ncy l ads to cost savings
Sourc : D lta Sourc : D lta In a joint keynote speech by De ta and Nvidia, the roadmap i ustrates the industry's gradua migration toward higher-vo tage power architectures. Ear ier AI server generations primari y uti ized conventiona power-de ivery schemes centered around rack- eve 48V distribution. As rack power requirements increased with B ackwe -generation systems, industry participants began eva uating higher-vo tage architectures capab e of supporting substantia y greater power density. Looking ahead, the industry is increasing y converging around 800VDC as a potentia next-generation standard for arge-sca e AI dep oyments, particu ar y as rack- eve power consumption approaches severa hundred ki owatts. The transition ref ects the need to improve power-distribution efficiency whi e supporting the continued growth of AI computing infrastructure.
Though we a so saw the 800VDC power rack reference design for the Vera Rubin rack in a 1-to-2 configuration (one 660KW power rack supporting two Vera Rubin racks), we think the adoption of this so ution might be re ative y ow, since the Vera Rubin rack a so has a reference design for the in-rack power she f design M Idea
Exhibit 20: 800VDC roadmap
Exhibit 2 : 800VDC r f r nc d sign for VR
Sourc : D lta
Exhibit 22: Liquid cool d pow r sh lf
Sourc : D lta
Liquid cooled power shelf on the horizon
The next key check point to watch shou d be the Vera Rubin U tra generation, as the power consumption per rack sha continue to increase and there might be more hardware devices to enab e the inter-rack sca e up network, both cou d take up more space on the IT rack. That said, the power she f wi shift from air coo ing into iquid coo ing, which cou d narrow the power she f height by 1U to free up some space as we . Our checks indicate that both the in-rack power she f and 800VDC power rack so utions are ongoing now, and we be ieve that rack space, power redundancy and system re iabi ity are a the factors being considered. We' c ose y monitor deve opments on this front.
Exhibit 23: Liquid cool d pow r sh lf in rack
Sourc : M gm t
Sourc : M gm t
Solid state transformers on the N idia RVL for the first time
In the MGX ecosystem board, where Nvidia usua y ist the recommenced vendor ists and product samp es, we saw SST this time. De ta, Heron. DG Matrax, Sungrow, So aredge, Megmeet, Luxshare, etc.
M Idea
Exhibit 24: SST v ndors on th Nvidia MGX cosyst m board
Sourc : Morgan Stanl y
Looking further ahead, So id-State Transformers (SSTs) represent a potentia nextgeneration evo ution of power infrastructure. Un ike traditiona transformers that operate primari y as passive devices, SSTs everage power e ectronics to provide vo tage conversion, power conditioning, and bidirectiona energy management within a sing e p atform. This enab es greater contro abi ity and f exibi ity whi e supporting increasing y digita ized power networks.
A though SSTs remain at an ear y stage of commercia ization and face cha enges re ated to economics, re iabi ity, and arge-sca e dep oyment, the techno ogy a igns we with ongterm data center trends. As AI campuses evo ve into uti ity-sca e power consumers incorporating energy storage, distributed generation, and advanced power management, SSTs cou d eventua y become a key enab ing techno ogy.
M Idea
Therefore, whi e HVDC is expected to drive the next phase of power architecture upgrades, SSTs represent a onger-term techno ogy roadmap that cou d further transform how future data centers distribute and manage e ectricity.
Exhibit 25: SST nabling mor ffici nt pow r d liv ry archit ctur
Exhibit 26: SST off rs b tt r pow r ffici ncy with at l ast 30% l ss spac /w ight
Sourc : Infin on
Sourc : Morgan Stanl y R s arch
According to Infineon, SST cou d represent an emerging >$1bn market opportunity by 2030, as the techno ogy begins to rep ace a portion of the >$15bn conventiona transformer market, particu ar y in sma er-power app ications. Whi e SST penetration is expected to remain re ative y modest versus the overa transformer market, the opportunity is significant for re evant p ayers in the onger term.
Exhibit 27: SST to s initial adoption in 2030
Solid-state transformers: new application for semiconductors with significant additional market potential
Compartson refers to muti modutar inverter (dual stage with HFT) based on owm estimations.
Sourc : Infin on M Idea
Valuation Methodology and Risks
Lite-On Technology (2301.TW)
Base case: P/E mu tip e of 17x based on average 2027-28 EPS. We be ieve our target mu tip e is justified by the 47% earnings CAGR we estimate for 2025-28, imp ying a PEG of 0.4, versus the stock's 16x P/E and 2% earnings CAGR during 2022-25, which imp ied a PEG of 7.2.
Risks to Upside
- n Stronger optica business growth
- n Stronger data center/server demand
- n PC/NB demand growth
- nDowntrend in raw materia prices
Risks to Downside
- nMacro demand weakness
- nWeaker data center/server demand
- n PC/NB demand s owdown
- n Uptrend in raw materia prices
Delt Electronics Inc. (2308.TW)
Base case: P/E mu tip e of 30x based on average 2027-28 EPS. We be ieve our target mu tip e is justified by the 63% earnings CAGR we estimate for 2025-28, imp ying a PEG of 0.5, versus the stock's ~23x P/E and 23% earnings CAGR during 2022-25, which imp ied a PEG of 1.0.
Risks to Upside
- n Faster-than-expected g oba economic growth
- n Fa ing raw materia prices
- nMargin improvement
Risks to Downside
- n G oba economic s owdown
- nOngoing component supp y tightness
- n Rising raw materia prices
- nMargin contraction as a resu t of higher operating expenses or faster ASP erosion
Chrom Ate Inc. (2360.TW)
Base case, 45x 2027e P/E. We use P/E as our va uation methodo ogy because we think it better captures Chroma's earnings growth momentum. The stock traded at an average va uation of ~19x P/E during 2014-25 with an operating profit CAGR of 20%, imp ying a PEG of 1.0. We think our target mu tip e of 45x is justified by the 61% operating profit CAGR we project for 2025-28.
Risks to Upside
- n Better-than-expected macro conditions
- n Stronger semi and photonics and power testing demand
M Idea
- nMargin improvement via better product mix
- n Better opex contro
Risks to Downside
- nMacro s owdown
- n Softer-than-expected AI capex
- n S ower progress in the advanced packaging capacity expansion
- nWeaker consumer e ectronics and automobi e re ated demand
- nMargin contraction arising from ack of revenue sca e and increasing opex
Bizlink (3665.TW)
Base case, derived from 30x 2027e P/E. We think our target P/E mu tip e is justified by an earnings CAGR of 46% seen over 2025-28e, which imp ies a PEG of around 0.7. This is in ine with the average of 0.7 in 2019-24, when the stock was trading at an average 13x P/E for a 19% earnings CAGR.
Risks to Upside
- n Faster and wider AEC adoption
- nData center and semi equipment capex increases that drive stronger HPC and semi-cap business
- n Stronger recovery for automotive business
Risks to Downside
- n Lower-than-expected AEC adoption
- n Intensifying competition
- n Softer-than-expected AI capex
- n S ower-than-expected growth in the semi capita equipment market
- n Continued weakness in the auto industry
M Idea
INDUSTRY COVERAGE: Greater China Technology Hardware
| Company (Ticker) | Rating (As Of) | Price* ( 0/ 6/2026) |
|---|---|---|
| Andy Meng, CFA | ||
| AAC Te hnologies Holdings (2018.HK) | O (01/29/2024) | HK$35.70 |
| A elink Te hnologies Co. Ltd. (002281.SZ) | U (05/12/2022) | Rmb133.75 |
| BYD Ele troni s (0285.HK) | O (04/28/2023) | HK$22.04 |
| China TransInfo Te hnology Co Ltd (002373.SZ) | E (07/18/2023) | Rmb7.16 |
| Dahua Te hnology Co. Ltd. (002236.SZ) | E (12/12/2024) | Rmb14.69 |
| Eoptolink Te hnology In Ltd (300502.SZ) | O (02/27/2026) | Rmb306.91 |
| Genius Ele troni Opti al Co. Ltd. (3406.TW) | E (10/13/2026) | NT$1,085.00 |
| GoerTek In (002241.SZ) | E (08/14/2026) | Rmb19.93 |
| Gosun n Te hnology Group Co Ltd (300098.SZ) | U (11/07/2022) | Rmb3.98 |
| HIKVision Digital Te hnology (002415.SZ) | E (12/12/2024) | Rmb33.66 |
| Largan Pre ision (3008.TW) | O (10/13/2026) | NT$6,400.00 |
| LianChuang Ele troni Te hnology Co Ltd (002036.SZ) | U (06/12/2024) | Rmb5.51 |
| Lingyi Ite h Guangdong Co (002600.SZ) | U (04/23/2025) | Rmb10.01 |
| Lingyi Ite h Guangdong Co (1688.HK) | O (08/14/2026) | HK$4.73 |
| Luxshare Pre ision Industry Co., Ltd. (2475.HK) | O (08/14/2026) | HK$46.70 |
| Luxshare Pre ision Industry Co., Ltd. (002475.SZ) | O (10/24/2016) | Rmb44.67 |
| OFILM Group Co Ltd (002456.SZ) | U (06/12/2024) | Rmb6.07 |
| Q Te hnology (Group) Company Ltd (1478.HK) | U (03/23/2026) | HK$4.70 |
| Que tel Wireless Solutions Co Ltd (603236.SS) | E (10/09/2024) | Rmb66.86 |
| Shanghai Conant Opti al Co Ltd (2276.HK) | O (04/10/2026) | HK$35.16 |
| Shenzhen Transsion Holdings Co Ltd (688036.SS) | E (03/23/2026) | Rmb48.12 |
| Sunny Opti al (2382.HK) | E (03/23/2026) | HK$57.70 |
| Suzhou TFC Opti al Communi ation Co Ltd. (300394.SZ) | E (11/06/2025) | Rmb212.80 |
| Wingte h Te hnology Co Ltd (600745.SS) | U (05/18/2026) | Rmb13.72 HK$26.66 |
| Xiaomi Corp (1810.HK) | O (04/14/2021) | |
| Yangtze Opti al Fibre and Cable JSC Ltd (601869.SS) | U (10/13/2021) | Rmb331.50 |
| Yangtze Opti al Fibre and Cable JSC Ltd (6869.HK) | O (07/15/2026) | HK$124.00 |
| Yongxin Opti s Co Ltd (603297.SS) Zhejiang Crystal-Opte h Co Ltd (002273.SZ) | E (11/15/2022) O (11/15/2022) | Rmb91.96 Rmb19.40 |
| Zhongji Innolight Co Ltd (300308.SZ) | O (09/07/2026) | Rmb670.00 |
| Zhongji Innolight Co Ltd (3308.HK) | O (09/07/2026) | HK$805.00 |
| ZTE Corporation (0763.HK) | O (06/04/2026) | HK$19.47 |
| ZTE Corporation (000063.SZ) | E (06/04/2026) | Rmb27.10 |
| Derrick Yang | ||
| A ton Te hnology Corporation (2345.TW) | O (06/06/2024) | NT$1,980.00 |
| Advante h (2395.TW) | O (01/20/2021) | NT$685.00 |
| AirTAC International (1590.TW) | O (04/16/2025) | NT$1,155.00 |
| Asia Vital Components Co. Ltd. (3017.TW) | O (07/30/2024) | NT$3,315.00 |
| AU Optroni s (2409.TW) | E (02/10/2026) | NT$35.90 |
| Auras Te hnology Co Ltd (3324.TWO) | E (05/04/2023) | NT$1,425.00 |
| Bizlink (3665.TW) | O (03/10/2025) | NT$2,015.00 |
| BOE Te hnology (000725.SZ) | O (09/06/2019) | Rmb5.13 |
| Chenbro (8210.TW) | O (07/23/2025) | NT$834.00 |
| Chroma Ate In . (2360.TW) | O (10/05/2021) | NT$2,000.00 |
| Delta Ele troni s In . (2308.TW) | O (07/13/2017) | NT$1,635.00 |
| E Ink Holdings In . (8069.TWO) | E (08/10/2026) | NT$155.00 |
| Ennostar In (3714.TW) | U (09/23/2022) | NT$63.40 |
| Fositek Corp (6805.TW) | O (06/25/2025) | NT$2,250.00 |
| Hiwin Te hnologies Corp. (2049.TW) | O (03/30/2026) | NT$311.00 |
| Innolux (3481.TW) | E (04/07/2025) | NT$48.25 |
| King Slide Works Co. Ltd. (2059.TW) | O (11/08/2023) | NT$9,955.00 |
M Idea
| Lens Te hnology (300433.SZ) | E (07/22/2020) | Rmb25.26 |
|---|---|---|
| Lite-On Te hnology (2301.TW) | E (01/15/2025) | NT$264.50 |
| TCL Corp. (000100.SZ) | E (04/07/2025) | Rmb4.54 |
| Tianma Mi roele troni s (000050.SZ) | U (01/24/2018) | Rmb5.84 |
| Howard Kao | ||
| A er In . (2353.TW) | U (04/23/2025) | NT$32.25 |
| Asustek Computer In . (2357.TW) | U (11/16/2025) | NT$994.00 |
| Cat her Te hnology (2474.TW) | U (11/17/2025) | NT$196.00 |
| Compal Ele troni s (2324.TW) | U (04/23/2025) | NT$36.70 |
| Elite Material Co. (2383.TW) | O (09/14/2026) | NT$5,165.00 |
| FIT Hon Teng Ltd (6088.HK) | O (11/03/2025) | HK$4.06 |
| Fox onn Industrial Internet Co. Ltd. (601138.SS) | O (07/10/2019) | Rmb47.78 |
| Giga-Byte Te hnology Co. Ltd. (2376.TW) | E (11/16/2025) | NT$357.50 |
| Gold Cir uit Ele troni s Ltd. (2368.TW) | O (10/06/2022) | NT$1,245.00 |
| Hon Hai Pre ision (2317.TW) | O (03/15/2024) | NT$244.00 |
| Inspur Ele troni Information (000977.SZ) | E (08/28/2023) | Rmb56.53 |
| Kingboard Laminates Holdings Ltd. (1888.HK) | O (09/14/2026) | HK$39.48 |
| LandMark Optoele troni s Corporation (3081.TWO) | E (03/26/2026) | NT$2,545.00 |
| Lenovo (0992.HK) | O (07/10/2026) | HK$28.06 |
| Lotes Co. Ltd. (3533.TW) | E (05/12/2025) | NT$1,805.00 |
| Nan Ya PCB (8046.TW) | O (02/23/2026) | NT$1,355.00 |
| Pegatron Corporation (4938.TW) | E (03/25/2026) | NT$102.00 |
| Quanta Computer In . (2382.TW) | O (05/01/2023) | NT$322.00 |
| Shengyi Te hnology Co Ltd. (600183.SS) | E (05/26/2022) | Rmb114.60 |
| Shennan Cir uits Co Ltd (002916.SZ) | E (08/24/2023) | Rmb309.99 |
| Unimi ron (3037.TW) | O (02/23/2026) | NT$1,090.00 |
| Visual Photoni s Epitaxy Co Ltd (2455.TW) | E (09/11/2023) | NT$493.00 |
| Wistron Corporation (3231.TW) | O (07/12/2023) | NT$182.50 |
| Wiwynn Corp (6669.TW) | O (11/10/2025) | NT$1,845.00 |
| Yageo Corp. (2327.TW) | O (10/28/2025) | NT$567.00 |
| Zhen Ding (4958.TW) | ++ | NT$557.00 |
| Irene Yen | ||
| Co-Te h Development Corp. (8358.TWO) | O (09/14/2026) | NT$472.00 |
| Taiwan Union Te hnology Corporation (6274.TWO) | O (09/14/2026) | NT$1,615.00 |
Stock Ratings ar subj ct to chang . Pl as s lat st r s arch for ach company.
- Historical pric s ar not split adjust d.