PDF 原檔:報告_Nomura_光模組BOM美國成分65pct_20261009_original.pdf
圖片清單(已驗證 2026-10-12)
ingest 時建立的「眼見為憑」圖片索引,是 lib/ 嵌圖的唯一真相來源;嵌入時只從這裡挑分類為「真資料圖」的,不照 trimmed 引用順序猜。
| 檔名 | size | 分類 | 親眼所見內容 |
|---|---|---|---|
報告_Nomura_光模組BOM美國成分65pct_20261009_002.png |
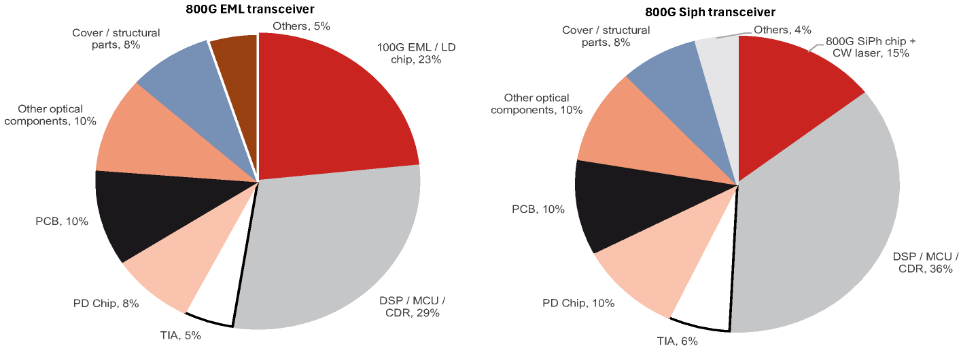
61KB | 真資料圖 | Fig.1:800G EML / 800G SiPh 收發器 BOM 成本拆解圓餅圖兩張並列(各分項百分比標示) |
報告_Nomura_光模組BOM美國成分65pct_20261009_003.png |
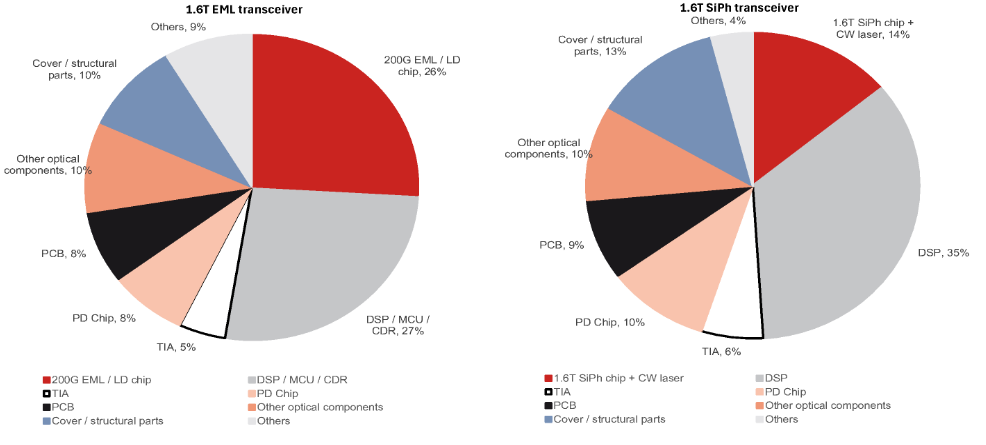
77KB | 真資料圖 | Fig.2:1.6T EML / 1.6T SiPh 收發器 BOM 成本拆解圓餅圖兩張並列(各分項百分比標示) |
原始內容
NOMURA
Global AI Trend Tracker
EQUITY: TECHNOLOGY
What if US content reaches 65% of transceiver BOM cost?
Quick Note
We have observed considerable volatility in China's optical communication stocks recently, following a Reuters report in early August on potential FCC (Federal Communications Committee) ban on Chinese optical transceivers (Reuters' report). We discussed in our previous report (link) that a lose-lose scenario would involve imposing ban on all new (next-gen) transceivers from Chinese suppliers. In recent days, many investors have been discussing a potential exception - that China's transceiver makers could still ship next-gen 3.2T transceivers to US customers if US components represent >65% of total BOM cost. If this scenario materializes, we believe it would be slightly more positive for the optical transceiver makers in China, which are primarily exposed to the US AIDC market. Business continuity for leading optical transceiver makers, i.e. InnoLight (300308 CH/ 3308 HK, Buy) and Eoptolink (300502 CH, Not rated), would not be meaningfully disrupted, although there is a risk of rising costs if they need to buy more US components.
800G/1.6T transceiver BOM cost analysis: '65% US content' is not an unrealistic goal to achieve, optical chips play a crucial role
We believe the discussion of a '65% US content' requirement for the optical transceiver industry is not without precedent, as the US government has imposed similar restrictions on the drone industry, where the 'Buy the American standard' needs 'US content' exceeding 65% (link). We note that China already has a well-established optical transceiver supply chain, and leading transceiver makers may hold more than 50% market share in 800G/1.6T transceivers. Meanwhile, some key components, i.e. DSP (Digital Signal Processor), are still dominated by US suppliers, and we think '65%' is not an unrealistic goal to achieve. Based on our estimates, optical lasers/chips, DSP, TIA (Transimpedance Amplifier)/driver chips, and PD (Photodiode) chips could make up 66%~72% of BOM costs of 800G EML/SiPh (Silicon Photonics) transceivers (Fig. 1) or 1.6T EML/SiPh transceivers (Fig. 2). Optical lasers/chips, which represent 14~23% of BOM costs, play a crucial role in meeting the '65% US content' threshold, in our view.
Supply-chain analysis: US players are better positioned for high-end chips, incumbent transceiver players may maintain leadership, but rising cost is a risk
If the '65% US content' rule is implemented, we believe US optical chip-makers might be better positioned in the high-end optical transceiver supply chain, with potential market share gains and more pricing power. The potential impact on non-US optical chip-makers remains unclear as there is no concrete information about the scope of the potential rules at this moment. For Chinese chip-makers such as Yuanjie Tech (688498 CH, Neutral), which was gaining tractions in the global market in the past 1-2 years, there would be more competitive pressure, in our view.
For the electronic chips and PD chips segment, where US companies such as Marvell (MRVL US, Not rated), Broadcom (AVGO US, Not rated), MACOM (MTSI US, Not rated) already play a leading role, we do not expect meaningful changes to the existing supply chain. For the passive optical components and PCB sectors, we do not expect much impact either as they represent a small percentage of total transceiver BOM costs and share a diversified global supply chain. We have listed the key players in the 800G/1.6T optical transceivers supply chain in Fig. 3.
For high-end transceiver products, we think incumbent optical transceiver makers such as InnoLight should be able to maintain its leadership, given its strong R&D capabilities and effective supply-chain management. However, if the key component market becomes more concentrated, supply shortages could lead to higher component costs, in our view.
Research Analysts
China Technology
Bing Duan - NIHK bing.duan1@nomura.com +852 2252 2141
Ethan Zhang - NIHK ethan.zhang@nomura.com
+852 2252 2157
Production Complete: 2026-10-09 11:56 UTC
Fig. 1: 800G transceiver BOM breakdown
Source: Company data, Nomura estimates
Fig. 2: 1.6T transceiver BOM cost breakdown
Source: Company data, Nomura estimates
Fig. 3: 800G / 1.6T transceiver key component suppliers
| 800G Component | US Suppliers | China Suppliers | Other Suppliers |
|---|---|---|---|
| 800G EML / LD chip | Lumentum, Broadcom, Coherent | Yuanjie Tech, Source Photonics | Mitsubishi Elec, Sumitomo Elec |
| 7nm or 5nm DSP | Marvell, Broadcom, Credo, Maxlinear | Sitrus Technology, Joywell Semi | N.A |
| TIA + Driver | Marvell, Broadcom, MACOM, Semtech | Youxun (优讯股份) | Mitsubishi Elec, Sumitomo Elec |
| 800G PD Chip | MACOM | PHOGRAIN (芯思杰) | GCS |
| PCB | TTMI?? | Shennan Circuits, Victory Giant | Unimicron, Zhen Ding |
| Other optical components | Coherent | TFC | Mitsubishi Elec, Sumitomo Elec |
| Cover / structural parts | CCTC | Murata, Kyocera |
| 1.6T Component | US Suppliers | China Suppliers | Other Suppliers |
|---|---|---|---|
| 200G EML / LD chip | Lumentum, Broadcom, Coherent | Source Photonics | Mitsubishi Elec, Sumitomo Elec |
| 3nm DSP | Marvell, Broadcom | N.A | N.A |
| TIA + Driver | Marvell, Broadcom, MACOM, Semtech | N.A | Mitsubishi Elec, Sumitomo Elec |
| PD Chip | MACOM | N.A | GCS |
| PCB | TTMI?? | Shennan Circuits | Unimicron, Zhen Ding |
| Other optical components | Coherent | TFC | Mitsubishi Elec, Sumitomo Elec |
| Cover / structural parts | CCTC | Murata, Kyocera |
Source: Company data, Nomura estimates
Appendix A-1
This report has been produced by Nomura International (Hong Kong) Ltd. (NIHK), Hong Kong. See Disclaimers for Nomura Group entity details.