PDF 原檔:報告_MS_MRVL_併購LITE_20261103_original.pdf
圖片清單(已驗證 2026-11-09)
| 檔名 | size | 分類 | 親眼所見內容 |
|---|---|---|---|
報告_MS_MRVL_併購LITE_20261103_001.png |
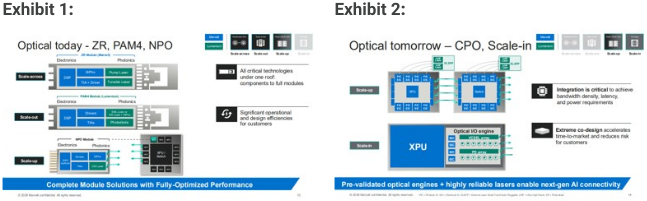
122KB | 真資料圖(架構/公司簡報) | Exhibit 1、2(Marvell 公司簡報頁):左「Optical today - ZR, PAM4, NPO」顯示 scale-across、scale-out、scale-up 三種模組內部分工,各含電子(Marvell:DSP、TIA+Driver)與光子(Lumentum:Laser、Pump Laser 等)兩層,標語 Complete Module Solutions with Fully-Optimized Performance;右「Optical tomorrow - CPO, Scale-in」顯示 scale-up CPO 與 XPU 周邊的 Optical I/O engines,標語 Pre-validated optical engines + highly reliable lasers enable next-gen AI connectivity。圖內文字小,細節以外不逐字 |
報告_MS_MRVL_併購LITE_20261103_002.png |
150KB | 真資料圖(財務,不嵌) | Marvell 簡報頁 Financially accretive combination:Marvell(FQ3'27 指引)/Lumentum(FQ1'27)/Pro Forma(不含綜效)。營收(MRQ 年化)12.6/5.1/17.7(US$bn);毛利率 58%/53%/57%;營益率 37%/42%/39%;右欄列綜效逾 US$1bn(主要 COGS)、預期交割後增厚毛利率、營益率與第一年 non-GAAP EPS |
報告_MS_MRVL_併購LITE_20261103_003.png |
40KB | 真資料圖(股價情境,不嵌) | MRVL Risk Reward 圖:現價 $171.41;12 個月 Bull $448(+161.36%,機率約 0.0%)、Base $300(+75.02%,>300 機率約 3.9%)、Bear $172(+0.34%,<172 機率約 55.6%) |
報告_MS_MRVL_併購LITE_20261103_004.png |
16KB | 真資料圖(評等分布,不嵌) | 共識評等分布:Overweight 91%、Equal-weight 9%、Underweight 0%;MS 評等標記在 Equal-weight |
報告_MS_MRVL_併購LITE_20261103_005.png |
28KB | 真資料圖(預估 vs 共識,不嵌) | MS 對 FY Jan 2027e 預估與共識均值:Sales 11,979(均值 12,071;範圍 11,941–12,398)、EBITDA 4,837(4,801)、Net income 3,822(3,758)、EPS 4.18(均值 4.22;範圍 3.92–4.34) |
報告_MS_MRVL_併購LITE_20261103_006.png |
55KB | 真資料圖(評等歷史,不嵌) | Lumentum 股價與 MS PT 歷史,2023-11 至 2026-11;PT 階梯含 45、52、50、54、61、76、83、81、40、70、76、85、100、92、145、190、304、350、420、520、595、710、900、1000,最近一次 1000;股價高點約 1,150 後回落至約 850 |
報告_MS_MRVL_併購LITE_20261103_007.png |
55KB | 真資料圖(評等歷史,不嵌) | Marvell 股價與 MS PT 歷史,2023-11 至 2026-11;PT 階梯含 65、63、84、71、77、82、120、102、113、90、73、70、80、76、112、86、95、103、172、195、234、246、268、300,最近一次 300;股價高點約 315 後回落至約 195 |
原始內容
| Morgan Stanley & Co. LLC | Morgan Stanley & Co. LLC | Morgan Stanley & Co. LLC | Morgan Stanley & Co. LLC | Morgan Stanley & Co. LLC | Morgan Stanley & Co. LLC |
|---|---|---|---|---|---|
| Joseph Moore | Joseph Moore | Joseph Moore | Joseph Moore | Joseph Moore | Joseph Moore |
| Equity Analyst | Equity Analyst | Equity Analyst | Equity Analyst | Equity Analyst | Equity Analyst |
| Meta A Marshall | Meta A Marshall | Meta A Marshall | Meta A Marshall | Meta A Marshall | Meta A Marshall |
| Equity Analyst | Equity Analyst | Equity Analyst | Equity Analyst | Equity Analyst | Equity Analyst |
| Ella Tulchinsky | Ella Tulchinsky | Ella Tulchinsky | Ella Tulchinsky | Ella Tulchinsky | Ella Tulchinsky |
| Equity Analyst | Equity Analyst | Equity Analyst | Equity Analyst | Equity Analyst | Equity Analyst |
| Ella.Tulc insky@morganstanley.com +1 212 761-2222 Mason Wayne | Ella.Tulc insky@morganstanley.com +1 212 761-2222 Mason Wayne | Ella.Tulc insky@morganstanley.com +1 212 761-2222 Mason Wayne | Ella.Tulc insky@morganstanley.com +1 212 761-2222 Mason Wayne | Ella.Tulc insky@morganstanley.com +1 212 761-2222 Mason Wayne | Ella.Tulc insky@morganstanley.com +1 212 761-2222 Mason Wayne |
| Researc Associate Mason.Wayne@morganstanley.com +1 212 761-6012 | Researc Associate Mason.Wayne@morganstanley.com +1 212 761-6012 | Researc Associate Mason.Wayne@morganstanley.com +1 212 761-6012 | Researc Associate Mason.Wayne@morganstanley.com +1 212 761-6012 | Researc Associate Mason.Wayne@morganstanley.com +1 212 761-6012 | Researc Associate Mason.Wayne@morganstanley.com +1 212 761-6012 |
| Shane Brett | Shane Brett | Shane Brett | Shane Brett | Shane Brett | Shane Brett |
| Equity Analyst | Equity Analyst | Equity Analyst | Equity Analyst | Equity Analyst | Equity Analyst |
| S ane.Brett@morganstanley.com +1 212 761-1022 | S ane.Brett@morganstanley.com +1 212 761-1022 | S ane.Brett@morganstanley.com +1 212 761-1022 | S ane.Brett@morganstanley.com +1 212 761-1022 | S ane.Brett@morganstanley.com +1 212 761-1022 | S ane.Brett@morganstanley.com +1 212 761-1022 |
| Nicole Kozhukhov | Nicole Kozhukhov | Nicole Kozhukhov | Nicole Kozhukhov | Nicole Kozhukhov | Nicole Kozhukhov |
| Researc Associate | Researc Associate | Researc Associate | Researc Associate | Researc Associate | Researc Associate |
| Nicole.Koz uk ov@morganstanley.com +1 212 761-1636 | Nicole.Koz uk ov@morganstanley.com +1 212 761-1636 | Nicole.Koz uk ov@morganstanley.com +1 212 761-1636 | Nicole.Koz uk ov@morganstanley.com +1 212 761-1636 | Nicole.Koz uk ov@morganstanley.com +1 212 761-1636 | Nicole.Koz uk ov@morganstanley.com +1 212 761-1636 |
| Cate Folan | Cate Folan | Cate Folan | Cate Folan | Cate Folan | Cate Folan |
| Researc Associate | Researc Associate | Researc Associate | Researc Associate | Researc Associate | Researc Associate |
| Marvell Technology Group Ltd (MRVL.O, MRVL US) | Marvell Technology Group Ltd (MRVL.O, MRVL US) | Marvell Technology Group Ltd (MRVL.O, MRVL US) | Marvell Technology Group Ltd (MRVL.O, MRVL US) | Marvell Technology Group Ltd (MRVL.O, MRVL US) | Marvell Technology Group Ltd (MRVL.O, MRVL US) |
| Semiconductors | Bermuda | Semiconductors | Bermuda | Semiconductors | Bermuda | Semiconductors | Bermuda | Semiconductors | Bermuda | Semiconductors | Bermuda |
| Stock Rating Equal-weight | Stock Rating Equal-weight | Stock Rating Equal-weight | Stock Rating Equal-weight | Stock Rating Equal-weight | Stock Rating Equal-weight |
| Industry View Attractive Price target $ 00.00 | Industry View Attractive Price target $ 00.00 | Industry View Attractive Price target $ 00.00 | Industry View Attractive Price target $ 00.00 | Industry View Attractive Price target $ 00.00 | Industry View Attractive Price target $ 00.00 |
| Shr price, close (Nov 2, 2026) $171.41 Mkt cap, curr (mm) $1 , 3 2-Week Range $329.88-70.69 | Shr price, close (Nov 2, 2026) $171.41 Mkt cap, curr (mm) $1 , 3 2-Week Range $329.88-70.69 | Shr price, close (Nov 2, 2026) $171.41 Mkt cap, curr (mm) $1 , 3 2-Week Range $329.88-70.69 | Shr price, close (Nov 2, 2026) $171.41 Mkt cap, curr (mm) $1 , 3 2-Week Range $329.88-70.69 | Shr price, close (Nov 2, 2026) $171.41 Mkt cap, curr (mm) $1 , 3 2-Week Range $329.88-70.69 | Shr price, close (Nov 2, 2026) $171.41 Mkt cap, curr (mm) $1 , 3 2-Week Range $329.88-70.69 |
| Josep Meta.Mars Fiscal Year Ending | .Moore@morganstanley.com all@morganstanley.com Cate.M.Folan@morganstanley.com | 01/26 | 01/27e | +1 +1 +1 01/28e | 212 761-7516 212 761-0430 212 296-3520 01/29e |
| EPS ($)** | EPS ($)** | 2.8 | 4.18 | 7.76 | 14.32 |
| Prior EPS ($)** P/E | Prior EPS ($)** P/E | - 36.8 | - 9.7 | - 26.2 | - 13.1 |
| EPS ($)§ | EPS ($)§ | 2.83 | 4.22 | 7.3 | 12.62 |
| Div yld (%) | Div yld (%) | 0.3 | 0.1 | 0.1 | 0.1 |
| Unless otherwise noted, all metrics are based on Morgan Stanley ModelWare framework ** = Based on consensus methodology | Unless otherwise noted, all metrics are based on Morgan Stanley ModelWare framework ** = Based on consensus methodology | Unless otherwise noted, all metrics are based on Morgan Stanley ModelWare framework ** = Based on consensus methodology | Unless otherwise noted, all metrics are based on Morgan Stanley ModelWare framework ** = Based on consensus methodology | Unless otherwise noted, all metrics are based on Morgan Stanley ModelWare framework ** = Based on consensus methodology | Unless otherwise noted, all metrics are based on Morgan Stanley ModelWare framework ** = Based on consensus methodology |
| Qu rterly EPS ($) | Qu rterly EPS ($) | Qu rterly EPS ($) | Qu rterly EPS ($) | Qu rterly EPS ($) | Qu rterly EPS ($) |
| § = Consensus e = Morgan Quarter | provided by Research 2026 | Refinitiv estimates 2027e | Estimates 2027e PriorCurrent | 2028e | 2028e PriorCurrent |
| Q1 | 0.62 | - | 0.80a | - | 1. 2 |
| Q2 | 0.67 | - | 0.94a | - | 1.76 |
| Q3 | 0.76 | - | 1.10 | - | 2.06 |
| Q4 | 0.80 | - | 1.33 | - | 2.41 |
e = Morgan Stanley Research estimates, a = Actual Company reported data
Morgan Stanley does and seeks to do business with companies covered in Morgan Stanley Research. As a result, investors should be aware that the firm may have a conflict of interest that could affect the objectivity of Morgan Stanley Research. Investors should consider Morgan Stanley Research as only a single factor in making their investment decision.
For analyst certification and other important disclosures, refer to the Disclosure Section, located at the end of this report.
M Idea November 3, 2026 01:07 AM GMT
Marvell Technology Group Ltd | North America
MRVL/LITE deal - an aggressive move with significant potential
The deal brings risks but also opportunities the company's very strong track record with M&A gives us comfort, and the selloff in the stock seems overdone.
告驿站 00002122
Key Takeaways
- The benefits of co designing lasers and electronics for next generation optics seem clear
- That said, laser margins are potentially more cyclical than base MRVL, and some of MRVL's DSP customers are Lumentum competitors
- The $1 bn in synergy - mostly COGS - is non trivial and will take time to play out
- Marvell's strong track record with M&A is a positive precedent, with Cavium, Inphi, and Avera all exceeding revenue and cost synergy targets
Our view: Marvell has a strong record of buying into technology inflections and successfully retaining key talent and driving accelerated growth, and we see the potential that the Lumentum (covered by Meta Marshall) deal follows the same playbook. Inphi is the clearest precedent. It looked expensive at announcement and Marvell s shares fell afterward, but that business is on track to have grown more than 10x since. The bar is higher here. At $115bn of enterprise value, the deal is more than 10x the size of Inphi and the largest semiconductor acquisition ever agreed. Cavium and Avera are also deals where Marvell exceeded all cost and revenue synergy targets, all of which gives us some comfort around a deal that certainly will require strong execution.
We see the benefits of co-designing lasers and electronics for next-generation optics, which is the core of the strategic case. In scale-up, customers are already asking for integrated solutions from a single supplier. The $1bn+ run-rate cost synergy target, primarily COGS, comes from pulling each company s content into the solutions the other already sells to customers. The opportunity should grow with revenue and, over time, with co-optimized roadmaps. However, delivering the synergies depends on Marvell winning that content without pushing competing module makers toward other DSP suppliers.
We also see two broader risks. Lumentum is earning margins above its own target model on tight InP supply, and the valuation assumes those economics hold well beyond a 1H28 close. The deal also needs Chinese approval, and China-based module makers, which buy Marvell s DSPs and compete with Lumentum, account for most transceiver supply. The strategic logic is sound, but the price leaves little room for error.
Deal Summary
告驿站 00002122
报
M Idea
Marvell will acquire Lumentum in an all stock transaction at a fixed exchange ratio of 4.5 Marvell shares for each Lumentum share. The deal implies approximately $115 billion of enterprise value, or roughly $1,132 per Lumentum share, representing a 23.9% premium to Lumentum s unaffected October 28 closing price. Marvell shareholders will own approximately 67% of the combined company, with Lumentum shareholders owning approximately 33%. Closing is expected in the first half of calendar 2028.
告驿站 00002122
Marvell highlights a combined 2030 TAM of $550 billion, more than $1 billion of annual run rate cost synergies, and expected accretion to non GAAP EPS in year one post close.
Strategic Rational
Our view is that the deal has a strong technology basis in scale-up and scale-in, where future optical architectures will require lasers and electronics to be codesigned. In today s scale-out market, the combination creates an opportunity to pull each company s content into the other s products, but is also a risk to Marvell s position as a neutral supplier.
Lumentum brings hard-to-replicate InP laser, optical switching and manufacturing capabilities, while Marvell brings the switches, NPO products, DSPs and custom silicon. Together, the companies can co-design light sources and optical engines directly into the switch and XPU, improving performance, reducing qualification time and potentially increasing content per link. Lumentum s current positions support this case. It leads in 200G EMLs used in 1.6T pluggables and holds 70-80% share in pump lasers. In optical switching, it is the leading merchant OCS supplier and has a multiyear, multi-billion-dollar OCS agreement. In CPO, it supplies UHP lasers into Nvidia s switches, and Nvidia invested $2 billion in Lumentum alongside a multibillion-dollar purchase commitment. Lumentum also announced today its second major NPO/CPO win, which management expects to generate over $5 billion of revenue with shipments starting in 2H CY27.
Why not just partner? A partnership could have captured some of the technology benefits at a much lower cost, particularly because Marvell and Lumentum already collaborate across parts of the optical stack. The counterargument is that scale-up changes the model. In scale-out, customers can qualify a switch and module from separate suppliers, while in scale-up the switch, optical engine and light source need to be co-designed with shared roadmaps and tighter systems integration. Ownership also secures priority access to scarce InP capacity to support growth.
On the opportunity side, management expects more than $1bn of annual run-rate synergies, primarily from COGS, by pulling each company s content into the other s products, and expects the synergies to grow as the combined company scales. These savings come where one company s content is not used today, for example a Lumentum module built with another vendor s DSP. Replacing a third-party supplier captures that supplier s margin and is a real saving. However, Lumentum is already a big customer of Marvell. Those existing sales are eliminated in consolidation and add no earnings, and they also shrink the pool of third-party content left to replace. Management did not provide detail on the split of the $1bn and did not quantify opex synergies. We assume none near-term given the employee base needed to
2 告驿站 00002122
报
M Idea
support growth. No revenue synergies were quantified. Over time, co-designed scale-up engines using internal lasers and DSPs should carry structurally lower COGS, which we view as margin on new revenue rather than a synergy against today s cost base. Despite limited information, this is an area where management's track record gives us optimism.
In our view, the main scale-out risk is supplier neutrality. Marvell already supplies DSPs and analog components to module makers that compete with Lumentum, which creates a real supplier neutrality risk and could encourage customers to shift DSP volume to other suppliers. Marvell is the leader in merchant PAM4 DSPs, so even modest share loss at competing module makers would matter. That said, management indicated it would continue selling components across the entire ecosystem. Marvell already sells its own DCI modules while supplying coherent DSPs to competing module makers, and Lumentum already sells lasers to most of its module competitors. Management also said module makers have expressed support since the announcement. We find these precedents encouraging but not conclusive. DCI is a much smaller market than scale-out PAM4, and Lumentum s laser customers have had few alternatives while capacity is tight. The clearest evidence will be next-generation DSP design wins, which module makers will award during the deal s pendency.
告驿站 00002122
Source: Company Presentation Source: Company Presentation
Pro Forma Model
Based on Marvell s FQ3 27 guidance and Lumentum s FQ1 27 results, the combined company would have $17.7 billion of annualized revenue, a 57% non GAAP gross margin and a 39% operating margin before synergies. The company also points to more than $1 billion of annual run rate synergies, primarily from COGS, and expects the transaction to be accretive to gross margin, operating margin and EPS in the first year after close. This is a current run rate snapshot rather than a forecast for the first full year, so we build our own CY29 pro forma below.
Exhibit : MRVL Pro Forma Snaps ot
告驿站 00002122
报
M Idea
告驿站 00002122
| (in $ billions) | Marvell (FQ327 Guidance**) | Lumentum (FQ1'27) | Pro Forma (excl. Synergies) |
|---|---|---|---|
| Revenue (MRQ Annualized) | $12.6 | $5.1 | $17.7 |
| Gross Margin* | 58% | 53% | 57% |
| Operating Margin* | 37% | 42% | 39% |
Source: Company Presentation
Our model: Assuming the transaction closes during CY28, we use CY29 as the first full calendar year in our pro forma analysis. We model approximately $71.0 billion of revenue, $41.1 billion of gross profit, a 57.8% gross margin, a 46.8% operating margin and $20.27 of pro forma non GAAP EPS. Our CY29 pro forma includes $700 million of COGS synergies but no operating expense or revenue synergies.
Against CY29 consensus EPS of $19.76, our pro forma is approximately 3% accretive. Given how far out the transaction is, the range of estimation error is wide. The outcome will depend on company performance, how quickly synergies are realized and when the deal closes. Our standalone Marvell CY29 EPS estimate is $21.55, above consensus, so the deal is slightly dilutive based on our higher estimates for MRVL, but we would agree that there is accretion potential vs. consensus.
4 告驿站 00002122
报
M Idea
Exhibit 4: Marvell + Lumentum: Pro Forma Financial Summary
($ in millions, except per share; calendar year, non-GAAP)
告驿站 00002122
| CY2027E STANDALONE - MARVELL | CY2027E STANDALONE - LUMENTUM | PRO FORMA - CY2029E | |
|---|---|---|---|
| MARVELL REVENUE | 20,294 | 53,587 | |
| LUMENTUM REVENUE | 8,635 | 17,423 | |
| REVENUE SYNERGIES / ELIMINATIONS | -- | ||
| TOTAL REVENUE | 20,294 | 8,635 | 71,010 |
| % Y/Y | 69.4% | 85.0% | |
| GROSS PROFIT | 11,713 | 4,697 | 41,068 |
| GROSS MARGIN | 57.7% | 54.4% | 57.8% |
| INCL. COGS SYNERGIES | 700 | ||
| OPERATING EXPENSES | 3,308 | 692 | 7,854 |
| % OF REVENUE | 16.3% | 8.0% | 11.1% |
| OPERATING INCOME | 8,405 | 4,005 | 33,214 |
| OPERATING MARGIN | 41.4% | 46.4% | 46.8% |
| INTEREST & OTHER INCOME (EXPENSE), NET | (159) | 66 | (57) |
| PRE-TAX INCOME | 8,246 | 4,071 | 33,157 |
| INCOME TAX | 1,072 | 672 | 4,974 |
| TAX RATE | 13.0% | 16.5% | 15.0% |
| NET INCOME | 7,174 | 3,399 | 28,184 |
| NET MARGIN | 35.4% | 39.4% | 39.7% |
| DILUTED SHARES (MM) | 924.7 | 103.9 | 1,390.4 |
| DILUTED EPS ($) | $7.76 | $32.70 | $20.27 |
Source: Morgan Stanley Researc
Note: CY2027E standalone figures are Morgan Stanley Researc estimates for eac company on a calendar-year, non-GAAP basis (Marvell fiscal year ends January; Lumentum fiscal year ends June).
CY2029E pro forma reflects t e first full year following t e expected 1H CY2028 close; all-stock consideration of 4.5 MRVL s ares per LITE s are.
Includes COGS synergies of $700mm in CY2029E (company target: $1bn+ run-rate); pro forma tax rate of 15%.
Other key con ideration
Peak La er Economic . Lumentum is already operating above its original target model. Its March 2026 OFC framework called for a 49-52% gross margin and 3842% operating margin at an $8 billion annualized revenue run rate. In FQ1'27 it reported a 53.2% gross margin and 42.3% operating margin at a $5 billion run rate, and it guided to a 45-46% operating margin for FQ2'27. Lumentum's gross margin has expanded by more than 2,000bp over the last eight quarters, driven by pricing, 200G EML mix, pump laser pricing and fab utilization. All incremental EML capacity is covered by long-term agreements through CY27.
The risk is that Marvell is paying for scarcity economics that normalize before closing or before new capacity is fully loaded. Lumentum's margins are well above historical levels and could normalize through Chinese competition or if more of the scale-up opportunity goes to VCSELs. Management argues that supply tightness is a byproduct of a durable architectural shift, and that the number of lasers required for scale-up and scale-in is massive. We agree the architectural transition is real, but the valuation leaves limited room for a slowdown in AI spending, pricing or utilization.
CPO and NPO timing. Lumentum's second major NPO and CPO win is an important proof point. Management said timing is consistent with its largest CPO customer, with shipments in 2H CY27, and that volume is high because the customer's optical lane density is very high. Lumentum expects its first scale-up CPO shipments by late CY27 and sizes the first phase of scale-up CPO at 3-4x scale-out CPO. Most of the
告驿站 00002122
报
M Idea
upside in this deal comes from these newer opportunities and from more tightly integrated optics and electronics. The deal isn't expected to close until 2028, but the timing of these next-generation optical opportunities matters for the deal's value to be realized.
Capital inten ity, cyclicality, and new management challenge . Lumentum adds a more capital-intensive manufacturing model. Its capex was ~15% of revenue in FY26, versus mid-to-high single digits for Marvell. Lumentum is running at mid-teens and would normalize to ~10%. Lumentum's margins are influenced by fab utilization, product mix, pricing and capacity additions. The company has also indicated that a new fab can require approximately $650 million of investment. Its Greensboro, NC fab, which begins ramping UHP lasers in 2028, adds more than $5 billion of revenue capacity, per management. The opportunity is attractive if demand remains structurally above supply, but the combined company will carry more fixed-cost and working-capital risk if the cycle turns.
告驿站 00002122
Regulatory approval. The transaction requires approval in the United States and China. Lumentum has noted that 60-65% of transceivers come from China-based vendors. Any concern that Marvell could restrict DSP access or favor its own modules could create pressure from customers or regulators. That said, there is little overlap between the companies and management has indicated that it received positive feedback from ecosystem partners, including in China, and has allowed ample time to complete the process.
What the Price Require
At $115 billion of enterprise value, Marvell is paying approximately 22x Lumentum s current annualized quarterly revenue and roughly 38x fiscal 2026 revenue. Historical optical acquisitions were generally completed at approximately 2x to 11x LTM revenue, although most of those targets were smaller and less exposed to AI infrastructure. The premium reflects Lumentum s growth, InP capacity and strategic scarcity, and it means the deal requires substantial execution beyond combining two existing businesses.
We continue to model Marvell on a standalone basis given the long path to closing. The deal is expected to close in 1H CY28, with an outside date that can extend to August 2028, and requires shareholder approval at both companies and regulatory approval in the US and China.
The strategic case is strongest if scale-up optics develop into a large integrated market in which customers prefer one supplier across switches, optical engines and light sources. Our bottom line is that the transaction is strategically logical but financially demanding. The key proof point will be whether Marvell and Lumentum can convert scale-up engagements into repeatable, high-margin, co-designed platforms without losing Marvell s DSP share at competing module makers. The deal carries real execution risk, but Marvell s M&A track record gives us comfort, and we think the selloff in the stock is overdone.
6 告驿站 00002122
报
M Idea
Risk Reward - Marvell Technology Group Ltd (MRVL.O) Risk Reward - Marvell Technology Group Ltd (MRVL.O)
Attractive growth capability but valuation leaves us EW
$300.00 PRICE TARGET
- ~46X CY27e Base Case MW EPS $6.54, a premium to high growth AI semis
$338.60
告驿站 00002122
Consensus Price Target Distribution
$229.95
$450.00
Source: Refinitiv, Morgan Stanley Research Morgan Stanley Estimates MS PT
■
Mean
RISK REWARD CHART AND OPTIONS IMPLIED PROBABILITIES (12M)
Source: Refinitiv, Morgan Stanley Research, Morgan Stanley Institutional Equities Division. The probabilities of our Bull, Base, and Bear case scenarios playing out were estimated with implied volatility data from the options market as of 2 Nov 2026. All figures are approximate risk-neutral probabilities of the stock reaching beyond the scenario price in either three-months ' or one-years ' time. View explanation of Options Probabilities methodology here
BULL CASE
BASE CASE
EQUAL-WEIGHT THESIS
- ▪The company has AI related opportunity, primarily the higher speed elements of the Inphi optical businesses (PAM4 and 400ZR), and longer term cloud custom silicon. We do expect this growth to play out, in particular on the optical side, and we expect MRVL to outgrow data center spending overall. We remain EW given valuation as well as high stock compensation expense that weighs on enthusiasm.
BEAR CASE
$448.00
60X Bull Case CY27e MW EPS of $7.46
- CY27 Revenue comes in at $17bn+
- Marvell's AI opportunity comes in larger than expected, helping drive upside to revenue estimates as well as drive multiple expansion
- The company hits on a number of cloud growth opportunities that drive the multiple higher
告驿站 00002122
$300.00
46X Base Case CY27e MW EPS of $6.54
- strong growth from optics and initial XPUXPUA attach programs starting to ramp
$172.00
30X Bear Case CY27e MW EPS of $5.73
- Storage and enterprise data center remain weak, with little line of sight for a recovery
- Networking continues to be a headwind, as inventory both at customers and in the channel continue to offset tailwinds in the custom ASIC business
- Stock overshoots to the downside closer to its tangible book value
报
M Idea
Risk Reward - Marvell Technology Group Ltd (MRVL.O)
KEY EARNINGS INPUTS
告驿站 00002122
| Drivers | Jan 2026 | Jan 2027e | Jan 2028e | Jan 2029e |
|---|---|---|---|---|
| GAAP Revenue ($, mm) | 8,195 | 11,979 | 20,294 | 35,869 |
| MW Gross Margin (%) | 58.9 | 57.8 | 57.4 | 57.3 |
| MW EPS ($) | 2.15 | 2.87 | 6.54 | 13.08 |
| Inventory ($, mm) | 1,388 | 1,802 | 2,903 | 5,176 |
| DOI | 126.2 | 116.8 | 115.0 | 119.0 |
INVESTMENT DRIVERS
- Company sees revenue growth in Storage and Networking resuming driven by the enterprise and storage markets
- Accretion from the Aquantia and Avera acquisitions come in above expectations
GLOBAL REVENUE EXPOSURE
Source: Morgan Stanley Research Estimate View explanation of regional hierarchies here
MS ALPHA MODELS
| 5/5 | 24 Month | 5/5 | 3 Month |
|---|---|---|---|
| BEST | Horizon | MOST | Horizon |
Source: Refinitiv, FactSet, Morgan Stanley Research; 1 is the highest favored Quintile and 5 is the least favored Quintile
8 告驿站 00002122
RISKS TO PT/RATING
RISKS TO UPSIDE
- AI opportunities (Inphi optical businesses) realize earlier than expected
- Cloud custom silicon projects are larger than expected
- The storage market recovers
RISKS TO DOWNSIDE
- AI opportunities are smaller than expected
- The strength we estimate for Storage and Networking surprise to the downside
- Enterprise DC and Networking continue to weigh on results
OWNERSHIP POSITIONING
| Inst. Owners, % Active | 46.5% |
|---|---|
| HF Sector Long/Short Ratio | 2.2x |
| HF Sector Net Exposure | 30.6% |
Refinitiv; MSPB Content. Includes certain hedge fund exposures held with MSPB. Information may be inconsistent with or may not reflect broader market trends. Long/Short Ratio = Long Exposure / Short exposure. Sector % of Total Net Exposure = (For a particular sector: Long Exposure - Short Exposure) / (Across all sectors: Long Exposure - Short Exposure).
MS ESTIMATES VS. CONSENSUS
Source: Refinitiv, Morgan Stanley Research
报
M Idea
Valuation Methodology and Risks
告驿站 00002122
告驿站 00002122
Lumentum Holdings Inc (LITE.O)
25x CY28 P/E of ~$40. ~25x is a premium to historical trading range given AI growth outlook
Risks to Upside
- nDatacom ramps and revenue mix more attractive vs. expectations
- nOCS ramps quickly, bringing additional revenue / profitability source
- n AI demand remains strong, causing EML business to outperform and drive profitability
- n CPO / NPO ramp faster than expected
Risks to Downside
- n EML pricing falls given oversupply on reduced AI demand
- n CW takes share from EML
- n Cloud Light hurts ability to improve margins
- n Pushout in CPO timing
报
M Idea
Risk Reward Reference links
告驿站 00002122
10 告驿站 00002122
- View explanation of Options Probabilities methodology -
Options_Probabilities_Exhibit_Link.pdf
- View descriptions of Risk Rewards Themes - RR_Themes_Exhibit_Link.pdf
- View explanation of regional hierarchies - GEG_Exhibit_Link.pdf
- View explanation of Theme/Exposure methodology -
ESG_Sustainable_Solutions_External_Link.pdf
- View explanation of HERS methodology - ESG_HERS_External_Link.pdf
报
M Idea
INDUSTRY COVERAGE: Semiconductors
告驿站 00002122
报
M Idea
告驿站 00002122
16 告驿站 00002122
| Company (Ticker) | Rating (As Of) | Price* (11/02/2026) |
|---|---|---|
| Ella Tulchinsky | ||
| Infleqtion, Inc. (INFQ.N) | E (10/1 /2026) | $8.1 |
| Xanadu Quantum Technologies Limited (XNDU.O) | E (10/1 /2026) | $2.60 |
| Joseph Moore | ||
| Advanced Micro Devices (AMD.O) | E (06/09/2024) | $466.84 |
| Aeva Technologies Inc (AEVA.O) | E (07/19/2021) | $8.60 |
| Allegro Microsystems Inc (ALGM.O) | O (02/13/2026) | $32.1 |
| Ambarella Inc (AMBA.O) | O (03/29/2016) | $61.67 |
| Amkor Technology Inc (AMKR.O) | E (11/08/2023) | $36.96 |
| Analog Devices Inc. (ADI.O) | O (11/16/2023) | $412.8 |
| Astera Labs Inc (ALAB.O) | O (0 /11/202 ) | $229.67 |
| Broadcom Inc. (AVGO.O) | O (06/09/2024) | $322.23 |
| Cerebras Systems (CBRS.O) | O (06/08/2026) | $96.36 |
| GlobalFoundries Inc (GFS.O) | E (10/28/2024) | $41.82 |
| Intel Corporation (INTC.O) | E (02/22/2023) | $ 9.97 |
| IonQ Inc (IONQ.N) | E (04/2 /2023) | $28.17 |
| Marvell Technology Group Ltd (MRVL.O) | E (09/14/201 ) | $171.41 |
| Microchip Technology Inc. (MCHP.O) | E (07/10/2024) | $76.11 |
| Micron Technology Inc. (MU.O) | O (10/06/202 ) | $833. 9 |
| Navitas Semiconductor Corp (NVTS.O) | U (04/06/202 ) | $7.93 |
| NVIDIA Corp. (NVDA.O) | O (03/16/2023) | $202.06 |
| NXP Semiconductor NV (NXPI.O) | O (02/11/202 ) | $2 7.24 |
| ON Semiconductor Corp. (ON.O) | ++ | $70.11 |
| Qualcomm Inc. (QCOM.O) | E (06/24/2026) | $162.08 |
| Quantinuum (QNT.O) | O (10/1 /2026) | $30.9 |
| SanDisk Corporation. (SNDK.O) | O (03/03/202 ) | $1,07 .08 |
| Semtech Corp. (SMTC.O) | E (04/06/202 ) | $122.38 |
| Silicon Laboratories Inc. (SLAB.O) | E (01/19/2021) | $222.10 |
| SiTime Corporation (SITM.O) | O (09/16/2026) | $417.90 |
| Skyworks Solutions Inc (SWKS.O) | E (11/28/2018) | $8 .17 |
| Texas Instruments (TXN.O) | U (04/13/2020) | $302.02 |
| Wolfspeed, INC (WOLF.N) | NR (04/06/202 ) | $20.8 |
| Lee Simpson | ||
| Arm Holdings plc (ARM.O) | E (04/07/2026) | $196.79 |
| Cadence Design Systems Inc (CDNS.O) | O (02/14/2024) | $329. 1 |
| PDF Solutions Inc (PDFS.O) | O (09/08/2026) | $38.97 |
| Synopsys Inc. (SNPS.O) | O (09/08/2026) | $466.08 |
Stock Ratings are subject to c ange. Please see latest researc for eac company.
- Historical prices are not split adjusted.
INDUSTRY COVERAGE: Telecom & Networking Equipment
| Company (Ticker) | Rating (As Of) | Price* (11/02/2026) |
|---|---|---|
| Meta A Marshall | ||
| Arista Networks (ANET.N) | O (10/31/2023) | $164.14 |
| Axon Enterprise Inc (AXON.O) | O (12/03/2024) | $42 .43 |
| Ciena Corporation (CIEN.N) | E (10/10/202 ) | $284.34 |
| Cisco Systems Inc (CSCO.O) | O (04/08/2024) | $101.61 |
| Coherent Corp (COHR.N) | E (12/13/2023) | $199.9 |
| Corning Inc (GLW.N) | E (06/13/2024) | $123.20 |
| F Inc (FFIV.O) | E (04/12/2022) | $324. |
| Keysight Technologies Inc (KEYS.N) | O (07/13/2026) | $298.94 |
| Lumentum Holdings Inc (LITE.O) | E (0 /12/2021) | $684.40 |
报
M Idea
| Motorola Solutions Inc (MSI.N) | O (12/17/202 ) | $487.31 |
|---|---|---|
| Zebra Technologies Corporation (ZBRA.O) | E (12/02/2024) | $361.13 |
Stock Ratings are subject to c ange. Please see latest researc for eac company.
- Historical prices are not split adjusted.
© 2026 Morgan Stanley
告驿站 00002122
告驿站 00002122
报