PDF 原檔:報告_Daiwa_雙鴻3324_3Q26前瞻_20261028_original.pdf
原始內容
AURAS Technology (3324 TT)
Target price: TWD2,180.00 (from TWD1,600.00)
Shareprice(28Oct):TWD1,435.00 | Up/downside:+51.9%
Stronger-than-expected 2027 outlook
- 3Q26 gross margin likely impacted by weaker-than-expected revenue
- However, we expect intact 4Q26/2027 revenue and earnings
- Reiterating our Buy (1) rating; raising 12-month TP to TWD2,180
What's new: We preview Auras' 3Q26 results. We reaffirm our Buy (1) rating, as we believe Auras' liquid-cooling capability will continue to help it gain order share in GPU and ASIC AI servers in the coming years.
What's the impact: 3Q26 preview. Auras' 3Q26 revenue of TWD9,791m (+12.5% QoQ, +64.3% YoY), announced earlier, accounts for 94.5% and 95.5% of our previous forecast (TWD10,365m, +19.1% QoQ and +74.0% YoY) and the consensus forecast, respectively. We attribute the revenue miss to delayed shipments in September (to 4Q26) and the flood impact in Thailand. Thus, we now forecast Auras' 3Q26 gross margin to be 28.5%, down from 30.0% (vs. 28.4% in 2Q26, 29.8% in 3Q25 and consensus forecast of 30.0%), mainly as we expect a reduced sales scale and lowerthan-expected gross margin on Auras' VGA and PC segments.
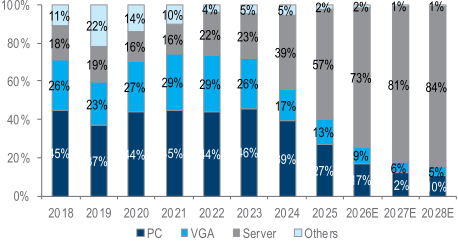
We forecast 3Q26 operating profit of TWD1.63bn (+17.3% QoQ, +64.3% YoY), 14% lower than the consensus forecast of TWD1.89bn, and operating margin of 16.7% (vs. 16.0% in 2Q26 and 16.7% in 3Q25). Overall, we forecast 3Q26 net profit of TWD1.24bn (+27.7% QoQ, +27.1% YoY), 16% lower than the consensus of TWD1.47bn. 3Q26 product mix by revenue: server 81% (+122% YoY), PC 14% (-15% YoY), VGA 4% (-40% YoY) and others 1% (-18% YoY). Liquid cooling accounted for 62% of Auras' 3Q26 revenue (vs. 55% in 2Q26 and 1Q26).
Much stronger 4Q26 and 2027 outlook, with rising liquid-cooling revenue exposure. We now forecast Auras' 4Q26 revenue to grow by 17.1% QoQ, raising from +5.1% QoQ, driven by a US ASIC project kicking off with liquid cooling component adoption; we expect stronger monthly revenue momentum in the coming months. We also see a chance for Auras to obtain a new US ASIC project in 2H27, with its liquid cooling revenue % rising further YoY, which should bode well for its gross margin expansion. We raise our 2027-28E EPS by 30-33% on more aggressive revenue and gross- and operating-margins forecasts.
What we recommend: We reiterate our Buy (1) call and raise our 12M TP to TWD2,180 (from TWD1,600), still based on a target PER of 22x (0.4x PEG over 2026-28E), close to the mid-point of its past-3-year range of 1038x (average PER: 19x), on our 1-year forward EPS (2027E). Key downside risks: softer-than-expected end-market demand, penetration rate of new specs and liquid-cooling development.
How we differ: Our 2027-28E EPS are 25-29% above the Bloomberg consensus, likely as we are more aggressive on our revenue and gross and operating margin assumptions.
5
4
3
2
1
Helen Chien
(886) 2 8758 6254
helen.chien@daiwacm-cathay.com.tw
Neil Teng, CFA (886) 2 8758 6256 neil.teng@daiwacm-cathay.com.tw
Forecast revisions (%)
| Year to 31 Dec | 26E | 27E | 28E |
|---|---|---|---|
| Revenue change | - | 23.7 | 24.6 |
| Net profit change | (2.8) | 28.4 | 25.7 |
| Core EPS (FD) change | - | 33.1 | 30.3 |
Source: Daiwa forecasts
| 12-month range | 820.00-1,710.00 |
|---|---|
| Market cap (USDbn) | 4.11 |
| 3m avg daily turnover (USDm) | 148.07 |
| Shares outstanding (m) | 93 |
| Major shareholder | Management (20.1%) |
Financial summary (TWD)
| Year to 31 Dec | 26E | 27E | 28E |
|---|---|---|---|
| Revenue (m) | 38,511 | 58,722 | 71,240 |
| Operating profit (m) | 6,777 | 11,744 | 15,174 |
| Net profit (m) | 5,158 | 9,279 | 11,857 |
| Core EPS (fully-diluted) | 55.089 | 99.110 | 126.648 |
| EPS change (%) | 99.6 | 79.9 | 27.8 |
| Daiwa vs Cons. EPS (%) | (2.4) | 24.8 | 28.5 |
| PER (x) | 26.0 | 14.5 | 11.3 |
| Dividend yield (%) | 1.5 | 2.8 | 3.6 |
| DPS | 22.2 | 39.9 | 51.0 |
| PBR (x) | 9.1 | 6.3 | 4.7 |
| EV/EBITDA (x) | 18.4 | 11.2 | 8.6 |
| ROE (%) | 40.0 | 51.8 | 47.9 |
Source: FactSet, Daiwa forecasts
Auras: revenue and earnings forecasts revisions
| (TWDm) | 2026E - New | 2026E - Previous | 2026E - Change | 2027E - New | 2027E - Previous | 2027E - Change | 2028E - New | 2028E - Previous | 2028E - Change |
|---|---|---|---|---|---|---|---|---|---|
| Sales | 38,511 | 38,511 | 0.0% | 58,722 | 47,487 | 23.7% | 71,240 | 57,197 | 24.6% |
| Gross profit | 11,361 | 11,476 | -1.0% | 18,263 | 14,484 | 26.1% | 22,441 | 18,017 | 24.6% |
| Gross margin | 29.5% | 29.8% | -0.3pp | 31.1% | 30.5% | 0.6pp | 31.5% | 31.5% | 0pp |
| Operating profit | 6,777 | 6,892 | -1.7% | 11,744 | 9,213 | 27.5% | 15,174 | 12,183 | 24.6% |
| Operating margin | 17.6% | 17.9% | -0.3pp | 20.0% | 19.4% | 0.6pp | 21.3% | 21.3% | 0pp |
| Net profit | 5,158 | 5,308 | -2.8% | 9,279 | 7,228 | 28.4% | 11,857 | 9,434 | 25.7% |
| Net margin | 13.4% | 13.8% | -0.4pp | 15.8% | 15.2% | 0.6pp | 16.6% | 16.5% | 0.1pp |
| Fully-diluted EPS (TWD) | 55.09 | 55.12 | 0.0% | 99.11 | 74.45 | 33.1% | 126.65 | 97.17 | 30.3% |
Source: Daiwa forecasts
Auras: 3Q26 results preview
| (TWDm) | Daiwa's 3Q26 forecasts | Our previous forecasts | Differ | Bloomberg consensus | Differ |
|---|---|---|---|---|---|
| Revenue | 9,791 | 10,365 | -5.5% | 10,183 | -3.8% |
| Gross profit | 2,790 | 3,110 | -10.3% | 3,051 | -8.5% |
| Operating profit | 1,630 | 1,950 | -16.4% | 1,892 | -13.8% |
| Profit before tax | 1,607 | 1,996 | -19.5% | 1,913 | -16.0% |
| Net profit | 1,237 | 1,557 | -20.5% | 1,470 | -15.8% |
| EPS | 13.30 | 16.72 | -20.5% | 15.68 | -15.2% |
| Margin | |||||
| Gross margin | 28.5% | 30.0% | -1.5pp | 30.0% | -1.5pp |
| Operating margin | 16.7% | 18.8% | -2.2pp | 18.6% | -1.9pp |
| Pre-tax margin | 16.4% | 19.3% | -2.8pp | 18.8% | -2.4pp |
| Net margin | 12.6% | 15.0% | -2.4pp | 14.4% | -1.8pp |
Source: Company, Bloomberg, Daiwa forecasts
Auras: quarterly and annual P&L
| (TWDm) | 2026E - 1Q26 | 2026E - 2Q26 | 2026E - 3Q26E | 2026E - 4Q26E | 2027E - 1Q27E | 2027E - 2Q27E | 2027E - 3Q27E | 2027E - 4Q27E | 2026E | 2027E | 2028E |
|---|---|---|---|---|---|---|---|---|---|---|---|
| Revenue | 8,552 | 8,700 | 9,791 | 11,468 | 12,000 | 13,500 | 15,000 | 18,222 | 38,511 | 58,722 | 71,240 |
| Gross profit | 2,537 | 2,472 | 2,790 | 3,561 | 3,696 | 4,185 | 4,680 | 5,702 | 11,361 | 18,263 | 22,441 |
| Operating profit | 1,520 | 1,390 | 1,630 | 2,236 | 2,396 | 2,735 | 3,080 | 3,533 | 6,777 | 11,744 | 15,174 |
| Pre-tax profit | 1,570 | 1,317 | 1,607 | 2,283 | 2,447 | 2,786 | 3,131 | 3,585 | 6,776 | 11,949 | 15,379 |
| Net profit | 1,164 | 969 | 1,237 | 1,787 | 1,882 | 2,157 | 2,436 | 2,804 | 5,158 | 9,279 | 11,857 |
| Basic EPS (TWD) | 12.61 | 10.41 | 13.30 | 19.20 | 20.22 | 23.17 | 26.17 | 30.12 | 55.51 | 99.69 | 127.39 |
| Margin | |||||||||||
| Gross margin | 29.7% | 28.4% | 28.5% | 31.1% | 30.8% | 31.0% | 31.2% | 31.3% | 29.5% | 31.1% | 31.5% |
| Operating margin | 17.8% | 16.0% | 16.7% | 19.5% | 20.0% | 20.3% | 20.5% | 19.4% | 17.6% | 20.0% | 21.3% |
| Pre-tax margin | 18.4% | 15.1% | 16.4% | 19.9% | 20.4% | 20.6% | 20.9% | 19.7% | 17.6% | 20.3% | 21.6% |
| Net margin | 13.6% | 11.1% | 12.6% | 15.6% | 15.7% | 16.0% | 16.2% | 15.4% | 13.4% | 15.8% | 16.6% |
| YoY | |||||||||||
| Revenue | 93.7% | 64.0% | 64.3% | 50.9% | 40.3% | 55.2% | 53.2% | 58.9% | 65.4% | 52.5% | 21.3% |
| Gross profit | 109.9% | 78.3% | 57.4% | 77.7% | 45.7% | 69.3% | 67.7% | 60.1% | 78.3% | 60.8% | 22.9% |
| Operating profit | 169.7% | 119.4% | 64.3% | 109.1% | 57.7% | 96.7% | 88.9% | 58.0% | 107.9% | 73.3% | 29.2% |
| Pre-tax profit | 135.6% | 524.9% | 33.4% | 90.9% | 55.9% | 111.5% | 94.9% | 57.1% | 106.8% | 76.3% | 28.7% |
| Net profit | 127.7% | 512.8% | 27.1% | 92.4% | 61.7% | 122.6% | 96.9% | 56.9% | 100.5% | 79.9% | 27.8% |
| QoQ | 38,511 | 58,722 | 71,240 | ||||||||
| Revenue | 12.6% | 1.7% | 12.5% | 17.1% | 4.6% | 12.5% | 11.1% | 21.5% | |||
| Gross profit | 26.6% | -2.5% | 12.9% | 27.6% | 3.8% | 13.2% | 11.8% | 21.8% | |||
| Operating profit | 42.1% | -8.5% | 17.3% | 37.2% | 7.1% | 14.1% | 12.6% | 14.7% | |||
| Pre-tax profit | 31.3% | -16.1% | 22.0% | 42.1% | 7.2% | 13.9% | 12.4% | 14.5% | |||
| Net profit | 25.3% | -16.8% | 27.7% | 44.4% | 5.3% | 14.6% | 13.0% | 15.1% |
Source: Company, Daiwa forecasts
Auras: product mix
Auras: 1-year forward PER
Source: Company, Daiwa forecasts
Source: Bloomberg, Daiwa forecasts
Financial summary
Key assumptions
| Year to 31 Dec | 2021 | 2022 | 2023 | 2024 | 2025 | 2026E | 2027E | 2028E |
|---|---|---|---|---|---|---|---|---|
| Server revenue YoY growth (%) | 17.7 | 37.7 | (5.8) | 109.7 | 117.9 | 110.0 | 70.0 | 25.0 |
| PC revenue YoY growth (%) | 20.5 | (4.9) | (4.6) | 5.4 | 1.7 | 5.0 | 5.0 | 5.0 |
| VGA revenue YoY growth (%) | 26.6 | (2.3) | (17.6) | (20.5) | 18.1 | 5.0 | 5.0 | 5.0 |
| Others revenue YoY growth (%) | (15.2) | (58.5) | 5.2 | 35.7 | (37.7) | 10.0 | 10.0 | 10.0 |
Profit and loss (TWDm)
| Year to 31 Dec | 2021 | 2022 | 2023 | 2024 | 2025 | 2026E | 2027E | 2028E |
|---|---|---|---|---|---|---|---|---|
| Server | 2,257 | 3,107 | 2,927 | 6,139 | 13,375 | 28,088 | 47,749 | 59,687 |
| PC | 6,422 | 6,106 | 5,824 | 6,138 | 6,242 | 6,554 | 6,882 | 7,226 |
| Other Revenue | 5,579 | 4,643 | 3,962 | 3,502 | 3,659 | 3,868 | 4,091 | 4,328 |
| Total Revenue | 14,258 | 13,857 | 12,713 | 15,779 | 23,276 | 38,511 | 58,722 | 71,240 |
| Other income | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| COGS | (11,595) | (11,135) | (9,708) | (11,753) | (16,904) | (27,150) | (40,460) | (48,800) |
| SG&A | (771) | (914) | (951) | (1,201) | (1,702) | (2,657) | (3,876) | (4,417) |
| Other op.expenses | (513) | (635) | (678) | (914) | (1,411) | (1,927) | (2,643) | (2,850) |
| Operating profit | 1,379 | 1,173 | 1,376 | 1,911 | 3,259 | 6,777 | 11,744 | 15,174 |
| Net-interest inc./(exp.) | (22) | (29) | (5) | 9 | (34) | (95) | (95) | (95) |
| Assoc/forex/extraord./others | 64 | 483 | 197 | 446 | 53 | 95 | 300 | 300 |
| Pre-tax profit | 1,421 | 1,628 | 1,568 | 2,366 | 3,277 | 6,776 | 11,949 | 15,379 |
| Tax | (268) | (341) | (329) | (434) | (580) | (1,288) | (2,270) | (2,922) |
| Min. int./pref. div./others | (21) | (23) | (7) | (39) | (126) | (331) | (400) | (600) |
| Net profit (reported) | 1,133 | 1,264 | 1,232 | 1,893 | 2,572 | 5,158 | 9,279 | 11,857 |
| Net profit (adjusted) | 1,133 | 1,264 | 1,232 | 1,893 | 2,572 | 5,158 | 9,279 | 11,857 |
| EPS (reported)(TWD) | 13.117 | 14.676 | 14.281 | 21.227 | 28.256 | 55.512 | 99.691 | 127.390 |
| EPS (adjusted)(TWD) | 13.117 | 14.676 | 14.281 | 21.227 | 28.256 | 55.512 | 99.691 | 127.390 |
| EPS (adjusted fully-diluted)(TWD) | 12.596 | 14.044 | 13.678 | 20.688 | 27.598 | 55.089 | 99.110 | 126.648 |
| DPS (TWD) | 6.000 | 6.500 | 6.350 | 10.000 | 12.000 | 22.205 | 39.949 | 51.048 |
| EBIT | 1,379 | 1,173 | 1,376 | 1,911 | 3,259 | 6,777 | 11,744 | 15,174 |
| EBITDA | 1,899 | 1,709 | 1,847 | 2,420 | 3,931 | 7,448 | 12,416 | 15,846 |
Cash flow (TWDm)
| Year to 31 Dec | 2021 | 2022 | 2023 | 2024 | 2025 | 2026E | 2027E | 2028E |
|---|---|---|---|---|---|---|---|---|
| Profit before tax | 1,421 | 1,628 | 1,568 | 2,366 | 3,277 | 6,776 | 11,949 | 15,379 |
| Depreciation and amortisation | 520 | 536 | 470 | 509 | 672 | 672 | 672 | 672 |
| Tax paid | (149) | (271) | (368) | (468) | (417) | (1,288) | (2,270) | (2,922) |
| Change in working capital | (233) | (769) | 296 | (667) | (3,812) | (4,040) | (7,934) | (3,690) |
| Other operational CF items | (115) | 116 | 6 | (97) | (315) | 95 | 95 | 95 |
| Cash flow from operations | 1,444 | 1,240 | 1,971 | 1,643 | (594) | 2,216 | 2,512 | 9,535 |
| Capex | (1,030) | (615) | (835) | (1,436) | (2,234) | (1,800) | (1,800) | (1,800) |
| Net (acquisitions)/disposals | 96 | 11 | (85) | (41) | (370) | (376) | (376) | (376) |
| Other investing CF items | (105) | (28) | (134) | (90) | (90) | 0 | 0 | 0 |
| Cash flow from investing | (1,038) | (633) | (1,053) | (1,567) | (2,695) | (2,176) | (2,176) | (2,176) |
| Change in debt | 677 | (61) | (386) | 1,608 | 2,762 | 200 | 1,300 | 200 |
| Net share issues/(repurchases) | (447) | 0 | 0 | 167 | 155 | 0 | 0 | 0 |
| Dividends paid | (482) | (517) | (577) | (571) | (903) | (1,108) | (2,063) | (3,712) |
| Other financing CF items | (51) | (52) | (43) | 160 | (64) | 0 | 0 | 0 |
| Cash flow from financing | (303) | (629) | (1,007) | 1,364 | 1,950 | (908) | (763) | (3,512) |
| Forex effect/others | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| Change in cash | 102 | (22) | (89) | 1,441 | (1,338) | (868) | (427) | 3,847 |
| Free cash flow | 414 | 625 | 1,136 | 208 | (2,828) | 416 | 712 | 7,735 |
Source: FactSet, Daiwa forecasts
Financial summary continued …
Balance sheet (TWDm)
| Year to 31 Dec | 2021 | 2022 | 2023 | 2024 | 2025 | 2026E | 2027E | 2028E |
|---|---|---|---|---|---|---|---|---|
| Cash & short-term investment | 1,494 | 1,484 | 1,366 | 2,809 | 1,439 | 571 | 144 | 3,991 |
| Inventory | 2,301 | 2,081 | 2,391 | 2,934 | 6,179 | 8,231 | 13,413 | 15,425 |
| Accounts receivable | 4,849 | 4,570 | 4,613 | 5,462 | 10,128 | 14,954 | 24,102 | 28,451 |
| Other current assets | 334 | 286 | 284 | 475 | 842 | 842 | 842 | 842 |
| Total current assets | 8,978 | 8,420 | 8,653 | 11,680 | 18,587 | 24,597 | 38,500 | 48,709 |
| Fixed assets | 2,442 | 2,715 | 3,126 | 4,083 | 6,150 | 6,750 | 7,350 | 7,950 |
| Goodwill & intangibles | 125 | 173 | 187 | 212 | 197 | 197 | 197 | 197 |
| Other non-current assets | 350 | 435 | 646 | 951 | 1,190 | 1,190 | 1,190 | 1,190 |
| Total assets | 11,895 | 11,743 | 12,612 | 16,926 | 26,125 | 32,734 | 47,237 | 58,046 |
| Short-term debt | 416 | 1,498 | 232 | 475 | 2,678 | 2,678 | 2,678 | 2,678 |
| Accounts payable | 4,938 | 3,668 | 4,136 | 5,019 | 9,311 | 12,175 | 18,598 | 21,296 |
| Other current liabilities | 315 | 454 | 419 | 407 | 534 | 122 | 122 | 122 |
| Total current liabilities | 5,670 | 5,620 | 4,787 | 5,902 | 12,523 | 14,975 | 21,397 | 24,096 |
| Long-term debt | 350 | 255 | 172 | 313 | 630 | 830 | 2,130 | 2,330 |
| Other non-current liabilities | 967 | 58 | 786 | 1,423 | 1,477 | 1,477 | 1,477 | 1,477 |
| Total liabilities | 6,986 | 5,933 | 5,745 | 7,638 | 14,630 | 17,282 | 25,004 | 27,903 |
| Share capital | 884 | 884 | 895 | 918 | 931 | 929 | 929 | 929 |
| Reserves/R.E./others | 3,859 | 4,682 | 5,741 | 8,043 | 10,154 | 13,782 | 20,163 | 27,473 |
| Shareholders' equity | 4,743 | 5,566 | 6,635 | 8,961 | 11,085 | 14,711 | 21,092 | 28,402 |
| Minority interests | 166 | 244 | 231 | 327 | 410 | 741 | 1,141 | 1,741 |
| Total equity & liabilities | 11,895 | 11,743 | 12,612 | 16,926 | 26,125 | 32,734 | 47,237 | 58,046 |
| EV | 133,001 | 134,075 | 132,832 | 131,870 | 135,841 | 137,241 | 139,368 | 136,321 |
| Net debt/(cash) | (728) | 269 | (961) | (2,020) | 1,869 | 2,937 | 4,664 | 1,017 |
| BVPS (TWD) | 53.654 | 62.968 | 74.140 | 97.655 | 119.093 | 158.341 | 227.017 | 305.698 |
Key ratios (%)
| Year to 31 Dec | 2021 | 2022 | 2023 | 2024 | 2025 | 2026E | 2027E | 2028E |
|---|---|---|---|---|---|---|---|---|
| Sales (YoY) | 16.7 | (2.8) | (8.3) | 24.1 | 47.5 | 65.4 | 52.5 | 21.3 |
| EBITDA (YoY) | (3.9) | (10.0) | 8.0 | 31.1 | 62.4 | 89.5 | 66.7 | 27.6 |
| Operating profit (YoY) | (11.7) | (14.9) | 17.3 | 38.8 | 70.6 | 107.9 | 73.3 | 29.2 |
| Net profit (YoY) | 1.9 | 11.6 | (2.5) | 53.6 | 35.9 | 100.5 | 79.9 | 27.8 |
| Core EPS (fully-diluted) (YoY) | (0.2) | 11.5 | (2.6) | 51.3 | 33.4 | 99.6 | 79.9 | 27.8 |
| Gross-profit margin | 18.7 | 19.6 | 23.6 | 25.5 | 27.4 | 29.5 | 31.1 | 31.5 |
| EBITDA margin | 13.3 | 12.3 | 14.5 | 15.3 | 16.9 | 19.3 | 21.1 | 22.2 |
| Operating-profit margin | 9.7 | 8.5 | 10.8 | 12.1 | 14.0 | 17.6 | 20.0 | 21.3 |
| Net profit margin | 7.9 | 9.1 | 9.7 | 12.0 | 11.1 | 13.4 | 15.8 | 16.6 |
| ROAE | 24.3 | 24.5 | 20.2 | 24.3 | 25.7 | 40.0 | 51.8 | 47.9 |
| ROAA | 10.3 | 10.7 | 10.1 | 12.8 | 11.9 | 17.5 | 23.2 | 22.5 |
| ROCE | 26.5 | 17.7 | 18.6 | 22.0 | 26.2 | 40.1 | 51.1 | 48.8 |
| ROIC | 29.9 | 18.1 | 18.2 | 23.7 | 26.0 | 34.6 | 42.0 | 42.3 |
| Net debt to equity | n.a. | 4.8 | n.a. | n.a. | 16.9 | 20.0 | 22.1 | 3.6 |
| Effective tax rate | 18.8 | 21.0 | 21.0 | 18.4 | 17.7 | 19.0 | 19.0 | 19.0 |
| Accounts receivable (days) | 122.0 | 124.1 | 131.8 | 116.5 | 122.2 | 118.9 | 121.4 | 134.6 |
| Current ratio (x) | 1.6 | 1.5 | 1.8 | 2.0 | 1.5 | 1.6 | 1.8 | 2.0 |
| Net interest cover (x) | 63.6 | 40.9 | 255.1 | n.a. | 95.8 | 71.2 | 123.4 | 159.5 |
| Net dividend payout | 45.7 | 44.3 | 44.5 | 47.1 | 42.5 | 40.0 | 40.1 | 40.1 |
| Free cash flow yield | 0.3 | 0.5 | 0.9 | 0.2 | n.a. | 0.3 | 0.5 | 5.8 |
Source: FactSet, Daiwa forecasts
Company profile
Founded in 1998 and listed on Taiwan's OTC stock board in May 2005, AURAS Technology (Auras) is a leading global thermal solutions provider that offers a one-stop shopping model. Its major clients include Quanta, Compal, HP, Lenovo, Dell, Amazon and Meta. Major applications for the company's products are notebooks (consumer, commercial and gaming), desktops, VGA, servers and others.
ESG analysis
ESG risks
| Risks | Risks | Management | Analystcomments |
|---|---|---|---|
| G | Executive/board quality | 2 | The CEO and Chairperson of Auras are the same individual, and we see the Chairperson has served as Auras' vice president for 14 years, which is a positive sign from an executive perspective. We see no issue with its board quality. |
| G | Capital management | 2 | Auras' dividend payout ratio was 42-47% over 2019-25, which we consider reasonable as the company is at a fast-growing stage. |
| G | Related party & transaction | 2 | Cost of goods generated from related-party transactions was less than 1% of total COGS during 2022-25, and we found no suspicious activity. |
| E | Supplychain management | 1 | Auras has a complete process to select and review its supply chain to make sure its supply- chain management meets ESG requirements. For example, those who submit ICP testing report and have ISO9001, QC080000 and ESG-related certifications would be the preferred choice as suppliers. |
| E | Datasecurity | 2 | To protect business information, Auras introduced the ISO 27001 management system in 2022, improving its information security system. Thus, when the company's business activities are affected by major disasters or equipment failure, Auras can effectively reduce the damage to an acceptable level, and ensure that the information operation process can be rebuilt. |
Note: Management score represents a company's ability to manage/benefit from certain ESG topics. The scores range from 1 to 3, with 1 being the strongest.
Update Date: 28 Oct 2026
Source: Daiwa, Company
圖片清單(已驗證 2026-10-29)
| 檔名 | size | 分類 | 親眼所見內容 |
|---|---|---|---|
報告_Daiwa_雙鴻3324_3Q26前瞻_20261028_001.png |
29KB | 真資料圖 | 「Share price performance」:雙鴻股價(藍,左軸 TWD)與相對加權指數(黃,右軸 %)Oct-25 至 Oct-26,股價自約 1,100 回落至 800 附近後 2026 年 7-9 月急升至約 1,700,再回落約 1,300-1,400(財務股價類) |
報告_Daiwa_雙鴻3324_3Q26前瞻_20261028_002.png |
39KB | 真資料圖 | 「Auras: product mix」營收組合堆疊(PC/VGA/Server/Others):Server 2025 57%、2026E 73%、2027E 81%、2028E 84%;PC 2025 27%、2026E 17%、2027E 12%、2028E 10%;VGA 2026E 9%、2027E 6%、2028E 5%(產品組合類,數字照圖標) |
報告_Daiwa_雙鴻3324_3Q26前瞻_20261028_003.png |
30KB | 真資料圖 | 「Auras: 1-year forward PER」:股價對 8x/12x/16x/20x/24x 倍數帶,Oct-19 至 Oct-26,2026 年股價落在約 16x-20x 帶之間(財務估值類) |