PDF 原檔:報告_Daiwa_台達電2308_20260930_original.pdf
圖片清單(已驗證 2026-10-01)
| 檔名 | size | 分類 | 親眼所見內容 |
|---|---|---|---|
報告_Daiwa_台達電2308_20260930_001.png |
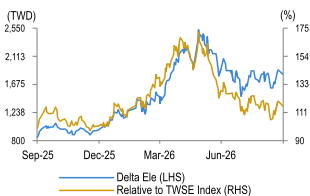
22,866B | 真資料圖 | 股價走勢折線圖:Delta Ele 股價(左軸,TWD 800-2,550)與相對 TWSE 指數表現(右軸,%),橫軸 2025/9–2026/6 |
報告_Daiwa_台達電2308_20260930_002.png |
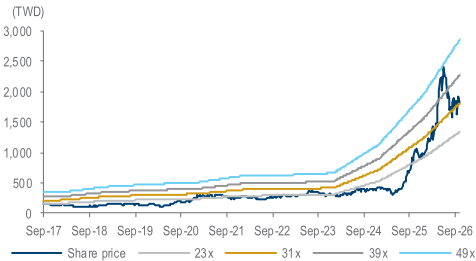
31,334B | 真資料圖 | 1 年期前瞻 PER band 圖:股價線(深藍)對應 23x/31x/39x/49x 四條本益比軌跡線,橫軸 2017/9–2026/9;trimmed 文字將此圖誤標在「product mix (yearly)」標題下,圖片實際內容為 PER band(非產品組合長條圖),以親眼所見為準 |
本份報告僅 2 張圖,均 <40KB 但內容清晰可辨,逐張 Read 確認均為真資料圖,無裝飾/文字卡。
原始內容
Delta Electronics (2308 TT)
Target price: TWD3,088.00 (from TWD2,988.00)
Shareprice(29Sep):TWD1,835.00 | Up/downside:+68.3%
Key beneficiary of the AI ASIC server trend
- Better-than-expected DC-DC AI server contribution from 2026E
- HVDC adoption rate should be higher-than-expected in 2028E
- Reaffirming our Buy (1) rating and raising 12M TP to TWD3,088
What's new: We provide our views on Delta after c.4 months of share price weakness, driven by investor concerns on HVDC delays, and a slowdown in power consumption trend amid deceleration in Nvidia's GPU shipment growth YoY. We remain positive on Delta over 2026-28E, as rising AI ASIC server trend should drive a meaningful increase in DC-DC power module ASPs (vs. Nvidia's discrete form factor). We expect higher HVDC adoption from 2028E, driven by IT rack and power supply architecture changes.
What's the impact: Component shortages are the key near-term bottleneck. We attribute the recent share-price weakness to slower-thanexpected revenue momentum in both 2Q26, due to vendor-sanction issue at Delta Thailand, and 3Q26E, due to a worsening shortage of power semiconductors. We believe the 2Q26 revenue shortfall was a one-off event, though 3Q26E growth is likely to remain constrained by the powersemi shortage. While supply capacity should improve, the supply-demand gap will likely persist for some time. That said, end-demand should remain sound. Given the continued improvement in revenue momentum, we still expect operating margin to reach a record-high of 18.3% in 3Q26.
Long-term growth drivers. We see Delta as a key beneficiary of the AI ASIC server trend. We were previously concerned that rising AI ASIC adoption could hurt Delta, as ASICs have lower thermal design power (TDP) than Nvidia GPUs, but now believe that Delta will benefit from rising content value of DC-DC power modules, as hyperscalers are more willing to spend on DC-DC modules (vs. discrete) despite higher initial cost given their superior energy efficiency. We forecast DC-DC power module revenue to reach c.TWD60bn in 2026E (vs. TWD9bn in 2025 and our prior estimate of c.TWD20bn for 2026E). This figure could increase further with rising ASIC usage in 2027. We also believe HVDC adoption rate could reach at least 50% in 2028E (vs. our prior expectation of 30%), as power supply architecture is becoming increasingly bulky (to accommodate aluminium capacitors inside power supply amid the super capacitor shortage). Limited space in IT racks would force customers to adopt more power racks and likely equip them with high voltage versions to improve efficiency.
What we recommend: We raise our 2026-28E EPS by 2-15% on higher HVDC contribution. We lift our 12M TP to TWD3,088 (from TWD2,988) based on a lower target PER of 49x (from 55x) to reflect market sentiment, (at the high-end of its past-3-year range of 11-50x) applied to our 1-yearforward EPS. Key downside risk: lower-than-expected demand.
How we differ: Our 2028E earnings is 21% above the Bloomberg consensus, likely due to our more bullish assumption for HVDC adoption.
3
2
1
(unchanged)
Sheng Cheng (886) 2 8758 6253
sheng.cheng@daiwacm-cathay.com.tw
Thomas Kim (886) 2 8758 6249 thomas.kim@daiwacm-cathay.com.tw
Forecast revisions (%)
| Year to 31 Dec | 26E | 27E | 28E |
|---|---|---|---|
| Revenue change | 1.9 | 5.0 | 14.2 |
| Net profit change | 1.7 | 3.1 | 14.6 |
| Core EPS (FD) change | 1.7 | 3.1 | 14.6 |
Source: Daiwa forecasts
Share price performance
| 12-month range | 854.00-2,520.00 |
|---|---|
| Market cap (USDbn) | 149.32 |
| 3m avg daily turnover (USDm) | 663.47 |
| Shares outstanding (m) | 2,598 |
| Major shareholder | HsiangTa International (10.3%) |
Financial summary (TWD)
| Year to 31 Dec | 26E | 27E | 28E |
|---|---|---|---|
| Revenue (m) | 772,369 | 1,130,604 | 1,830,517 |
| Operating profit (m) | 139,487 | 228,659 | 406,934 |
| Net profit (m) | 104,917 | 165,332 | 296,181 |
| Core EPS (fully-diluted) | 40.391 | 63.649 | 114.023 |
| EPS change (%) | 74.5 | 57.6 | 79.1 |
| Daiwa vs Cons. EPS (%) | (0.6) | (0.5) | 20.7 |
| PER (x) | 45.4 | 28.8 | 16.1 |
| Dividend yield (%) | 0.6 | 1.1 | 1.6 |
| DPS | 11.6 | 20.0 | 30.0 |
| PBR (x) | 12.9 | 9.5 | 6.4 |
| EV/EBITDA (x) | 28.2 | 18.0 | 10.4 |
| ROE (%) | 32.9 | 38.1 | 47.6 |
Source: FactSet, Daiwa forecasts
Delta Electronics: revenue and earnings forecasts - Daiwa vs. consensus
| (TWDm) | 2026E - Previous | 2026E - New | 2026E - Consensus | 2027E - Previous | 2027E - New | 2027E - Consensus | 2028E - Previous | 2028E - New | 2028E - Consensus |
|---|---|---|---|---|---|---|---|---|---|
| Revenue | 758,318 | 772,369 | 776,290 | 1,077,026 | 1,130,604 | 1,041,896 | 1,603,479 | 1,830,517 | 1,547,778 |
| Diff (%) | 1.9% | -0.5% | 5.0% | 8.5% | 14.2% | 18.3% | |||
| Gross Margin (%) | 36.3% | 36.4% | 36.3% | 36.4% | 36.6% | 37.3% | 36.8% | 37.4% | 37.8% |
| Operating profit | 136,739 | 139,487 | 140,319 | 218,460 | 228,659 | 226,483 | 354,257 | 406,934 | 337,447 |
| Op Margin (%) | 18.0% | 18.1% | 18.1% | 20.3% | 20.2% | 21.7% | 22.1% | 22.2% | 21.8% |
| Net profit | 103,133 | 104,917 | 105,513 | 160,325 | 165,332 | 166,236 | 258,555 | 296,181 | 245,392 |
| EPS | 39.70 | 40.39 | 40.62 | 61.72 | 63.65 | 64.00 | 99.54 | 114.02 | 94.47 |
| Diff (%) | 1.7% | -0.6% | 3.1% | -0.5% | 14.6% | 20.7% |
Source: Bloomberg, Daiwa forecasts
Delta: quarterly and annual P&L statement
| (TWDm) | 2026E - 1Q | 2026E - 2Q | 2026E - 3QE | 2026E - 4QE | 2027E - 1QE | 2027E - 2QE | 2027E - 3QE | 2027E - 4QE | 2025 | 2026E | 2027E | 2028E |
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Net revenue | 159,353 | 183,256 | 203,032 | 226,728 | 227,803 | 262,584 | 301,325 | 338,892 | 554,885 | 772,369 | 1,130,604 | 1,830,517 |
| COGS | -100,392 | -117,948 | -129,236 | -144,028 | -144,973 | -165,994 | -189,980 | -215,565 | -364,729 | -491,604 | -716,512 | -1,146,765 |
| Gross profit | 58,961 | 65,308 | 73,796 | 82,700 | 82,830 | 96,590 | 111,345 | 123,327 | 190,157 | 280,765 | 414,092 | 683,753 |
| Operating expenses | -30,544 | -34,738 | -36,546 | -39,451 | -39,638 | -44,114 | -48,815 | -52,867 | -106,224 | -141,278 | -185,434 | -276,818 |
| Operating profit | 28,417 | 30,570 | 37,250 | 43,250 | 43,193 | 52,476 | 62,531 | 70,460 | 83,932 | 139,487 | 228,659 | 406,934 |
| Non-operating profit | 2,676 | 4,430 | 1,695 | 1,709 | 1,218 | 1,210 | 1,208 | 1,411 | 3,934 | 10,510 | 5,047 | 5,344 |
| Pretax profit | 31,093 | 35,000 | 38,946 | 44,959 | 44,410 | 53,686 | 63,739 | 71,871 | 87,866 | 149,997 | 233,706 | 412,278 |
| Income taxes | -7,258 | -7,831 | -8,568 | -9,891 | -9,770 | -11,811 | -14,023 | -15,812 | -19,930 | -33,548 | -51,415 | -88,640 |
| Net profit | 20,556 | 25,136 | 27,332 | 31,894 | 31,223 | 37,936 | 45,196 | 50,976 | 60,108 | 104,917 | 165,332 | 296,181 |
| Net EPS (TWD) | 7.91 | 9.68 | 10.52 | 12.28 | 12.02 | 14.60 | 17.40 | 19.62 | 23.14 | 40.39 | 63.65 | 114.02 |
| Operating Ratios | ||||||||||||
| Gross margin | 37.0% | 35.6% | 36.3% | 36.5% | 36.4% | 36.8% | 37.0% | 36.4% | 34.3% | 36.4% | 36.6% | 37.4% |
| Operating margin | 17.8% | 16.7% | 18.3% | 19.1% | 19.0% | 20.0% | 20.8% | 20.8% | 15.1% | 18.1% | 20.2% | 22.2% |
| Pre-tax margin | 19.5% | 19.1% | 19.2% | 19.8% | 19.5% | 20.4% | 21.2% | 21.2% | 15.8% | 19.4% | 20.7% | 22.5% |
| Net margin | 12.9% | 13.7% | 13.5% | 14.1% | 13.7% | 14.4% | 15.0% | 15.0% | 10.8% | 13.6% | 14.6% | 16.2% |
| YoY (%) | ||||||||||||
| Net revenue | 34% | 48% | 35% | 40% | 43% | 43% | 48% | 49% | 32% | 39% | 46% | 62% |
| Gross profit | 56% | 48% | 41% | 48% | 40% | 48% | 51% | 49% | 39% | 48% | 47% | 65% |
| Operating profit | 102% | 64% | 50% | 64% | 52% | 72% | 68% | 63% | 76% | 66% | 64% | 78% |
| Pretax profit | 99% | 79% | 44% | 75% | 43% | 53% | 64% | 60% | 71% | 71% | 56% | 76% |
| Net profit | 101% | 80% | 47% | 84% | 52% | 51% | 65% | 60% | 71% | 75% | 58% | 79% |
| QoQ (%) | ||||||||||||
| Net revenue | -1% | 15% | 11% | 12% | 0% | 15% | 15% | 12% | ||||
| Gross profit | 5% | 11% | 13% | 12% | 0% | 17% | 15% | 11% | ||||
| Operating profit | 8% | 8% | 22% | 16% | 0% | 21% | 19% | 13% | ||||
| Pretax profit | 21% | 13% | 11% | 15% | -1% | 21% | 19% | 13% | ||||
| Net profit | 19% | 22% | 9% | 17% | -2% | 22% | 19% | 13% |
Source: Company, Daiwa forecasts
Delta: 1-year-forward PER band
Delta: product mix (yearly)
| Product mix (TWDm) | 2025 | 2026E | 2027E | 2028E |
|---|---|---|---|---|
| Power supply | ||||
| Server | 63,046 | 76,230 | 93,520 | 113,763 |
| AI server | 61,351 | 167,394 | 317,839 | 737,386 |
| Infrastructure | ||||
| Datacentre Infra | 54,695 | 62,623 | 73,966 | 91,437 |
| liquid cooling equipment | 46,900 | 106,732 | 252,621 | 450,779 |
| BBU | 11,500 | 20,885 | 35,367 | 51,524 |
| AI-related sales | 174,446 | 357,633 | 679,792 | 1,331,125 |
| % of mix | 31% | 46% | 60% | 73% |
| Server-related sales | 237,492 | 433,863 | 773,312 | 1,444,888 |
| % of mix | 43% | 56% | 68% | 79% |
Source: TEJ, Daiwa forecasts
Source: Company, Daiwa forecasts
Financial summary
Key assumptions
| Year to 31 Dec | 2021 | 2022 | 2023 | 2024 | 2025 | 2026E | 2027E | 2028E |
|---|---|---|---|---|---|---|---|---|
| Automation revenue growth (YoY) | 18 | 19 | (0) | (3) | 5 | 10 | 7 | 6 |
| Infrastructure revenue growth (YoY) | (8) | 26 | (4) | 2 | 82 | 46 | 68 | 54 |
| Power Electronics sales growth (YoY) | 21 | 21 | 9 | (10) | 25 | 47 | 42 | 76 |
Profit and loss (TWDm)
| Year to 31 Dec | 2021 | 2022 | 2023 | 2024 | 2025 | 2026E | 2027E | 2028E |
|---|---|---|---|---|---|---|---|---|
| Power Electronics | 187,316 | 227,311 | 248,257 | 223,992 | 280,032 | 412,588 | 584,196 | 1,030,133 |
| Automation | 45,881 | 54,519 | 54,296 | 52,403 | 54,943 | 60,345 | 64,800 | 68,944 |
| Other Revenue | 81,474 | 102,613 | 98,674 | 144,752 | 219,911 | 299,436 | 481,607 | 731,441 |
| Total Revenue | 314,671 | 384,443 | 401,227 | 421,148 | 554,885 | 772,369 | 1,130,604 | 1,830,517 |
| Other income | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| COGS | (224,461) | (273,671) | (284,013) | (284,567) | (364,729) | (491,604) | (716,512) | (1,146,765) |
| SG&A | (31,642) | (37,564) | (40,215) | (47,354) | (57,482) | (75,990) | (95,620) | (141,409) |
| Other op.expenses | (27,202) | (31,770) | (36,048) | (41,575) | (48,743) | (65,288) | (89,814) | (135,409) |
| Operating profit | 31,365 | 41,439 | 40,950 | 47,652 | 83,932 | 139,487 | 228,659 | 406,934 |
| Net-interest inc./(exp.) | 134 | 38 | 899 | 1,859 | 1,501 | 1,591 | 1,567 | 1,564 |
| Assoc/forex/extraord./others | 4,128 | 4,588 | 6,793 | 1,804 | 2,433 | 8,919 | 3,480 | 3,780 |
| Pre-tax profit | 35,628 | 46,065 | 48,642 | 51,316 | 87,866 | 149,997 | 233,706 | 412,278 |
| Tax | (7,128) | (9,075) | (9,762) | (10,925) | (19,930) | (33,548) | (51,415) | (88,640) |
| Min. int./pref. div./others | (1,703) | (4,325) | (5,488) | (5,163) | (7,828) | (11,532) | (16,959) | (27,458) |
| Net profit (reported) | 26,796 | 32,666 | 33,393 | 35,229 | 60,108 | 104,917 | 165,332 | 296,181 |
| Net profit (adjusted) | 26,796 | 32,666 | 33,393 | 35,229 | 60,108 | 104,917 | 165,332 | 296,181 |
| EPS (reported)(TWD) | 10.316 | 12.576 | 12.855 | 13.562 | 23.140 | 40.391 | 63.649 | 114.023 |
| EPS (adjusted)(TWD) | 10.316 | 12.576 | 12.855 | 13.562 | 23.140 | 40.391 | 63.649 | 114.023 |
| EPS (adjusted fully-diluted)(TWD) | 10.316 | 12.576 | 12.855 | 13.562 | 23.140 | 40.391 | 63.649 | 114.023 |
| DPS (TWD) | 5.500 | 5.500 | 9.840 | 6.430 | 7.000 | 11.600 | 20.000 | 30.000 |
| EBIT | 31,365 | 41,439 | 40,950 | 47,652 | 83,932 | 139,487 | 228,659 | 406,934 |
| EBITDA | 48,516 | 60,375 | 62,540 | 72,668 | 111,771 | 168,652 | 265,796 | 451,602 |
Cash flow (TWDm)
| Year to 31 Dec | 2021 | 2022 | 2023 | 2024 | 2025 | 2026E | 2027E | 2028E |
|---|---|---|---|---|---|---|---|---|
| Profit before tax | 35,628 | 46,065 | 48,642 | 51,316 | 87,866 | 149,997 | 233,706 | 412,278 |
| Depreciation and amortisation | 17,151 | 18,936 | 21,590 | 25,016 | 27,839 | 29,164 | 37,138 | 44,667 |
| Tax paid | (7,128) | (9,075) | (9,762) | (10,925) | (19,930) | (33,548) | (51,415) | (88,640) |
| Change in working capital | (20,506) | (20,062) | 2,466 | (2,538) | (24,348) | (79,476) | (110,688) | (146,647) |
| Other operational CF items | 3,175 | 10,665 | 8,151 | 10,025 | 27,047 | (175) | (80) | (80) |
| Cash flow from operations | 28,319 | 46,529 | 71,086 | 72,895 | 98,474 | 65,964 | 108,660 | 221,579 |
| Capex | (23,027) | (21,824) | (27,830) | (33,485) | (46,091) | (71,830) | (67,836) | (87,865) |
| Net (acquisitions)/disposals | (1,953) | (2,489) | (5,421) | (304) | (2,702) | 0 | 0 | 0 |
| Other investing CF items | (1,501) | (406) | (251) | (6,571) | (4,420) | 0 | 0 | 0 |
| Cash flow from investing | (26,481) | (24,719) | (33,502) | (40,360) | (53,214) | (71,830) | (67,836) | (87,865) |
| Change in debt | 6,993 | (1,900) | 10,327 | 7,135 | 11,729 | 0 | 0 | 0 |
| Net share issues/(repurchases) | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| Dividends paid | (15,751) | (15,026) | (27,455) | (18,696) | (20,313) | (30,132) | (51,951) | (77,926) |
| Other financing CF items | 421 | (2,814) | 6,651 | 444 | (817) | 0 | 0 | 0 |
| Cash flow from financing | (8,337) | (19,739) | (10,478) | (11,118) | (9,401) | (30,132) | (51,951) | (77,926) |
| Forex effect/others | (2,358) | 9,621 | (1,198) | 8,586 | (2,146) | 0 | 0 | 0 |
| Change in cash | (8,857) | 11,692 | 25,909 | 30,003 | 33,713 | (35,998) | (11,127) | 55,788 |
| Free cash flow | 5,292 | 24,705 | 43,257 | 39,410 | 52,383 | (5,867) | 40,824 | 133,714 |
Source: FactSet, Daiwa forecasts
Financial summary continued …
Balance sheet (TWDm)
| Year to 31 Dec | 2021 | 2022 | 2023 | 2024 | 2025 | 2026E | 2027E | 2028E |
|---|---|---|---|---|---|---|---|---|
| Cash & short-term investment | 51,268 | 63,572 | 92,620 | 121,793 | 155,113 | 119,115 | 107,988 | 163,776 |
| Inventory | 69,697 | 83,980 | 81,756 | 89,706 | 108,208 | 148,085 | 222,038 | 331,596 |
| Accounts receivable | 72,700 | 89,676 | 81,706 | 92,180 | 125,020 | 172,147 | 248,968 | 367,286 |
| Other current assets | 3,213 | 3,222 | 3,877 | 7,246 | 7,440 | 7,440 | 7,440 | 7,440 |
| Total current assets | 196,878 | 240,450 | 259,958 | 310,925 | 395,781 | 446,788 | 586,434 | 870,097 |
| Fixed assets | 76,607 | 86,267 | 98,002 | 115,710 | 142,040 | 184,706 | 215,404 | 258,602 |
| Goodwill & intangibles | 73,610 | 77,170 | 78,544 | 78,783 | 75,326 | 75,326 | 75,326 | 75,326 |
| Other non-current assets | 18,017 | 21,987 | 21,242 | 26,480 | 26,472 | 26,646 | 26,726 | 26,806 |
| Total assets | 365,112 | 425,874 | 457,747 | 531,898 | 639,619 | 733,466 | 903,890 | 1,230,832 |
| Short-term debt | 4,442 | 2,119 | 5,875 | 8,121 | 17,325 | 2,364 | 2,364 | 2,364 |
| Accounts payable | 54,570 | 62,716 | 53,539 | 69,223 | 94,452 | 101,981 | 142,066 | 223,295 |
| Other current liabilities | 49,157 | 60,179 | 66,671 | 74,939 | 97,888 | 97,888 | 97,888 | 97,888 |
| Total current liabilities | 108,169 | 125,013 | 126,085 | 152,283 | 209,665 | 202,234 | 242,318 | 323,547 |
| Long-term debt | 43,914 | 44,337 | 51,420 | 56,309 | 56,703 | 56,703 | 56,703 | 56,703 |
| Other non-current liabilities | 26,904 | 31,156 | 37,506 | 43,740 | 47,861 | 47,861 | 47,861 | 47,861 |
| Total liabilities | 178,988 | 200,507 | 215,011 | 252,332 | 314,230 | 306,798 | 346,883 | 428,112 |
| Share capital | 25,975 | 25,975 | 25,975 | 25,975 | 25,975 | 25,975 | 25,975 | 25,975 |
| Reserves/R.E./others | 128,811 | 160,813 | 173,188 | 204,112 | 242,083 | 343,361 | 473,701 | 719,413 |
| Shareholders' equity | 154,787 | 186,789 | 199,164 | 230,087 | 268,058 | 369,337 | 499,677 | 745,389 |
| Minority interests | 31,338 | 38,578 | 43,572 | 49,478 | 57,331 | 57,331 | 57,331 | 57,331 |
| Total equity & liabilities | 365,112 | 425,874 | 457,747 | 531,898 | 639,619 | 733,466 | 903,890 | 1,230,832 |
| EV | 4,794,918 | 4,787,955 | 4,774,739 | 4,758,607 | 4,742,738 | 4,763,776 | 4,774,903 | 4,719,115 |
| Net debt/(cash) | (2,912) | (17,115) | (35,325) | (57,363) | (81,085) | (60,047) | (48,920) | (104,708) |
| BVPS (TWD) | 59.590 | 71.910 | 76.674 | 88.579 | 103.197 | 142.187 | 192.365 | 286.959 |
Key ratios (%)
| Year to 31 Dec | 2021 | 2022 | 2023 | 2024 | 2025 | 2026E | 2027E | 2028E |
|---|---|---|---|---|---|---|---|---|
| Sales (YoY) | 11.3 | 22.2 | 4.4 | 5.0 | 31.8 | 39.2 | 46.4 | 61.9 |
| EBITDA (YoY) | 2.6 | 24.4 | 3.6 | 16.2 | 53.8 | 50.9 | 57.6 | 69.9 |
| Operating profit (YoY) | (0.2) | 32.1 | (1.2) | 16.4 | 76.1 | 66.2 | 63.9 | 78.0 |
| Net profit (YoY) | 5.1 | 21.9 | 2.2 | 5.5 | 70.6 | 74.5 | 57.6 | 79.1 |
| Core EPS (fully-diluted) (YoY) | 5.1 | 21.9 | 2.2 | 5.5 | 70.6 | 74.5 | 57.6 | 79.1 |
| Gross-profit margin | 28.7 | 28.8 | 29.2 | 32.4 | 34.3 | 36.4 | 36.6 | 37.4 |
| EBITDA margin | 15.4 | 15.7 | 15.6 | 17.3 | 20.1 | 21.8 | 23.5 | 24.7 |
| Operating-profit margin | 10.0 | 10.8 | 10.2 | 11.3 | 15.1 | 18.1 | 20.2 | 22.2 |
| Net profit margin | 8.5 | 8.5 | 8.3 | 8.4 | 10.8 | 13.6 | 14.6 | 16.2 |
| ROAE | 17.8 | 19.1 | 17.3 | 16.4 | 24.1 | 32.9 | 38.1 | 47.6 |
| ROAA | 7.6 | 8.3 | 7.6 | 7.1 | 10.3 | 15.3 | 20.2 | 27.7 |
| ROCE | 13.8 | 16.4 | 14.3 | 14.8 | 22.6 | 31.5 | 41.5 | 55.1 |
| ROIC | 14.6 | 17.0 | 15.7 | 17.5 | 27.8 | 35.5 | 40.8 | 53.0 |
| Net debt to equity | net cash | net cash | net cash | net cash | net cash | net cash | net cash | net cash |
| Effective tax rate | 20.0 | 19.7 | 20.1 | 21.3 | 22.7 | 22.4 | 22.0 | 21.5 |
| Accounts receivable (days) | 79.7 | 77.1 | 78.0 | 75.4 | 71.4 | 70.2 | 68.0 | 61.4 |
| Current ratio (x) | 1.8 | 1.9 | 2.1 | 2.0 | 1.9 | 2.2 | 2.4 | 2.7 |
| Net interest cover (x) | n.a. | n.a. | n.a. | n.a. | n.a. | n.a. | n.a. | n.a. |
| Net dividend payout | 56.1 | 53.3 | 78.2 | 50.0 | 51.6 | 50.1 | 49.5 | 47.1 |
| Free cash flow yield | 0.1 | 0.5 | 0.9 | 0.8 | 1.1 | n.a. | 0.9 | 2.8 |
Source: FactSet, Daiwa forecasts
Company profile
Founded in 1971, Delta Electronics has been the global leader in switching power supply solutions since 2002 and DC brushless fans since 2006. Its business covers 3 key areas: power electronics (eg, power supplies, thermal management products and passive components), automation (eg, controllers, robot arms and building management systems), and infrastructure (eg, datacentre infrastructure, networking and EV charging).
ESG analysis
ESG risks
| Risks | Management | Analystcomments | |
|---|---|---|---|
| Executive/board quality | 1 | Delta's board has 7 non-independent and 5 independent directors with a term of three years. The total number of directors and ratio of independent directors appear higher than most other listed companies. Besides, according to Delta's CSR report, enhancing the board's functions is one of the key goals for the company to achieve better corporate governance; also, the board members' diversity and professionalism will be taken into consideration to ensure a good board quality. Moreover, the company evaluates all the directors in the board using internal regulations and an external independent institution each year and at least once every three years, respectively. We believe Delta has implemented relatively more enhanced measure than most listed firms to improve its board quality. | |
| G | Capital management | 2 | During 2016-19, Delta's payout ratio was stable in the range of c.70%, but fell to 56% in 2020 and 53% in 2021. For 2020, it was mainly due to a sizeable non-cash re-valuation gain after the acquisition of Delta Thailand (DET), while the company maintained more cash on hand to deal with the uncertainties caused by COVID-19. However, the DPS growth from 2016 to 2021 was limited, as Delta struggled with business diversification into new end-markets (eg, smartphone, NEV). We believe that Delta's effort started to bear fruit in recent years after its NEV business has gradually picked up. Overall, we see a stable dividend policy from Delta and expect its DPS to continue to grow YoY in the future given that they declared a TWD11.6 DPS for 2025 which equals a 50% payout ratio. |
| Related party & transaction | 1 | Revenue from related parties stood at 12% of total 2025 revenue and purchases from related parties were at 11%. We see limited risk from related party transactions. | |
| S | Supplychain management | 1 | Delta focuses on: 1) localised management, 2) supplier certification and risk management, and 3) supplier sustainability engagement as key initiatives under the scope of supply chain management. In 2019, 144 new suppliers joined Delta's supply chain system. All of them passed environmental and social evaluations, signed the declaration of "non-use of conflict materials", and complied with Responsible Business Alliance's (BRA) Code of Conduct. Also, these vendors had to implement and abide by Delta's supply chain CSR policy and code of conduct. To lower ESG risks, Delta carries out RBA audits and monitors high-risk critical suppliers each year. The suppliers that fail these audits have to provide detailed improvement plans in response to identified issues. Besides, Delta has surveyed a total of 263 suppliers with potential risk and 63 suppliers with high risk of the total 1,331 suppliers, based on its CSR policy and code of conduct. If these suppliers are flagged as high-risk and no concrete improvements are made, Delta may consider terminating cooperation and transactions with them to improve the company's engagement on supplier sustainability. Overall, we think Delta has a solid plan to improve its supply chain management with specific KPIs, including: 1) achieving supplier improvement rate of 80% in 2025, 2) reducing GHG emissions rate of critical suppliers by 10% in 2025, and 3) improving water saving rate of critical suppliers by 12% in 2025. |
| S | Datasecurity | 2 | Delta's Information Security team created Delta's Information Security Policy in November 2013 and started providing educational training to global employees in 2014. Delta gradually introduced the Information Security Management System (ISMS) in 2016 and obtained the ISO 27001 international certification in 2018. According to ISO27001, Delta has to conduct at least one internal audit on information security and appoint an independent institution to conduct audit externally. According to Delta, no major deficiencies have been found in recent years. |
Note: Management score represents a company's ability to manage/benefit from certain ESG topics. The scores range from 1 to 3, with 1 being the strongest.
Update Date: 30 Sep 2026
Source: Daiwa, Company