PDF 原檔:報告_Citi_COHR垂直整合光通訊_20260921_original.pdf
圖片清單(已驗證 2026-09-24)
| 檔名 | size | 分類 | 親眼所見內容 |
|---|---|---|---|
報告_Citi_COHR垂直整合光通訊_20260921_002.png |
87KB | 真資料圖 | "Coherent Uniquely Positioned to Deliver the Full Solution" 表格:Coherent vs 雷射/收發器/光纖/光學元件各類廠商的技術涵蓋比較 |
報告_Citi_COHR垂直整合光通訊_20260921_003.png |
235KB | 真資料圖 | PhotonLink 整合光學平台實體模組照片+規格:ELS、CPO/NPO anchor customer、100Tbps I/O、200Gbps 光道、每 100T chip 內容值上看 $15K |
報告_Citi_COHR垂直整合光通訊_20260921_004.png |
97KB | 真資料圖 | 超高功率 CW 雷射照片+三張特性曲線圖:Optical Power、Power Conversion Efficiency、Phase Noise |
報告_Citi_COHR垂直整合光通訊_20260921_005.png |
51KB | 真資料圖 | GaAs/InP 雷射產能擴充長條圖:GaAs 產能 Q4CY22→Q4CY27 達 4 倍以上、InP 產能 Q4CY25→Q4CY27 達 2 倍以上 |
報告_Citi_COHR垂直整合光通訊_20260921_006.png |
120KB | 真資料圖 | CPO 方案(Example 1)產品照片:ELS、FAU、Precision Fiber Assembly、6.4Tb/s 矽光子模組,含 >10 客戶洽談、anchor customer LTA、量產時程 Q4CY26 scale-out/2H CY27 scale-up 標註 |
報告_Citi_COHR垂直整合光通訊_20260921_007.png |
116KB | 真資料圖 | NPO 方案(Example 2A)產品照片:6.4Tb/s 矽光子 socketed NPO、FAU、Precision Fiber Assembly、ELS,量產時程 2H CY27 |
報告_Citi_COHR垂直整合光通訊_20260921_008.png |
106KB | 真資料圖 | Citi 對 COHR 評等與目標價歷史走勢圖(2023-11 至 2026-09),最新一筆 2026-04-20 目標價 $420、股價 $347.51 |
報告_Citi_COHR垂直整合光通訊_20260921_001.png |
16KB | 真資料圖 | COHR 股價走勢圖(Sep24-Jun26,約 $70→$400 區間) |
<40KB 未 Read 者免列(預設 logo);本報告全部 8 張抽圖皆已逐張 Read 確認為真資料圖,無裝飾/文字卡誤入。
原始內容
citi
21 Sep 2026 17:13:22 ET │ 15 pages
Coherent Corp (COHR.K)
ECOC 2026 - Vertical Integration Is COHR's Key Advantage
CITI'S TAKE
Citi attended day 1 of ECOC where we hosted a session with COHR EVP of Optical Components and CTO Julie Sheridan and joined COHR's PhotonLink event. Net-net, we came out of the two sessions more positive on COHR roadmap and believe the company's vertical integration remains its key moat as it allows the company to reach up to $15k of content per switch/processor chip needing 100T of I/O capacity at 200G optical lane. We recap our key takeaways below.
| EPS (US$) | Q1 | Q2 | Q3 | Q4 | FY | FC Cons | VA Cons |
|---|---|---|---|---|---|---|---|
| 2026A | 1.16A | 1.29A | 1.41A | 1.74A | 5.59A | 5.61A | 5.59A |
| 2027E | 1.99E | 2.21E | 2.55E | 2.81E | 9.57E | 9.38E | 9.39E |
| Previous | 1.99E | 2.21E | 2.55E | 2.81E | 9.57E | na | na |
| 2028E | 3.41E | 3.83E | 4.22E | 4.64E | 16.11E | 14.01E | 14.50E |
| Previous | 3.41E | 3.83E | 4.22E | 4.64E | 16.11E | na | na |
| 2029E | na | na | na | na | na | 18.66E | 18.48E |
Click here for Visible Alpha consensus data
n Buy
Price (21 Sep 26 16:00)
US$321.52
Target price US$420.00
Expected share price return
30.6%
Expected dividend yield
0.0%
Expected total return
30.6%
Market Cap US$62,964M
Price Performance (RIC: COHR.K, BB: COHR US)
Papa Sylla AC
+1-212-816-9476 papa.sylla@citi.com
Atif Malik
+1-415-951-1892
atif.malik@citi.com Strategy and positioning: Management launched PhotonLink as an architectureagnostic integrated optics platform covering CPO, NPO, and chip-to-chip optical connections. It spans the full optical chain: Generating the light, shaping and guiding it, and detecting it at the far end. Management discussed that its customers asked it to supply complete assemblies rather than individual components as stitching together lasers, fiber and passive optics is difficult. It argued that no other company holds the full portfolio in-house and that Coherent can manufacture at datacenter scale. Management expects a mix of adoption paths, with some customers going straight to CPO and others starting with NPO and moving to CPO later.
Figure 1. COHR's Portfolio of Optical AI Networking Products
Customers and content: In a full-solution example (combining the ELS, the assembly to the switch or XPU, and the assembly out to the faceplate), management said Coherent content could reach up to $15k of content per switch/processor chip needing 100T of I/O capacity at 200G optical lane. Coherent counts more than 10 customer engagements each in CPO and NPO and more than 5 in chip-to-chip, with activity going up sharply over the past six months. For CPO, management said it has an anchor customer with an LTA secured, which it identified as NVDA. It also has an anchor customer and LTA for NPO, which it did not name. Separately, management cited two LTAs for ultra-high-power CW lasers with leading hyperscale or AI datacenter customers, also unnamed.
Figure 2. PhontonLink Platform
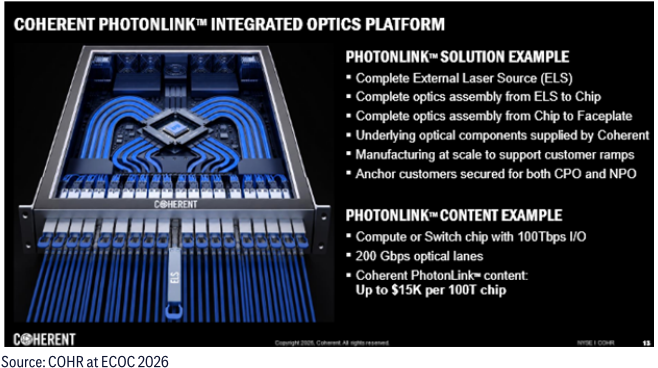
Timing: CPO for scale-out, tied to the NVIDIA agreement, begins ramping in the December quarter (calendar Q4 2026). CPO for scale-up follows in the second half of calendar 2027. NPO ramps in the second half of next calendar year, mainly for scale-up. Chip-to-chip is further out, around 2029-2030.
Light generation: The ultra-high-power CW laser sits in an external laser source that holds up to eight lasers, each feeding roughly four links. It starts ramping this quarter, with significant volume next year, on the 6-inch InP platform in Sherman, Texas. For NPO, a high-power buried-heterostructure CW laser is already shipping in millions of units per month for pluggables. VCSEL arrays come in a conventional version for ribbon fiber and a high-density 2D version that can be flip-chipped directly to drivers and TIAs with backside lenses. Photodetectors run to 200G today, with 400G in development.
Figure 3. UHP CW Laser Leader
Source: COHR at ECOC 2026
Fab footprint: Sherman runs 6-inch InP and GaAs, Sweden runs 6-inch InP. Zurich runs 6-inch GaAs and is adding 6-inch InP for high-power lasers, while Fremont runs a 3-inch line. GaAs capacity has grown fourfold since the 6-inch move about six years ago, with capacity for over one billion VCSEL arrays per year. InP capacity doubled last year, a quarter ahead of schedule, and management plans to double it again or more.
Figure 4. COHR Capacity Expansion
Shape, guide, and receive: Coherent grows garnet in the United States and says it supplies a significant fraction of the industry's garnet and isolators, with customers signing LTAs for capacity. The ELS is built on the transceiver line and is sampling now. The rest of the portfolio covers specialty fiber (polarizationmaintaining fiber production-ready, mode-matched fiber introduced at ECOC, multi-core fiber), micro-lens arrays, V-grooves, fiber array units, a detachable connector, circulators, WDM multiplexers, and fiber shuffles.
Silicon photonics and engines: Management discussed Coherent having an inhouse silicon photonics design team, uses foundries for wafers, and does assembly and test in-house. It ships 200G-per-lane silicon photonics in transceivers today and showed a 400G link at OFC with a post-deadline paper. It has a 6.4T silicon photonics NPO module (32 lanes of 200G) and a VCSEL-based NPO with 2D arrays, which management says achieves about 1.2 pJ/bit including the laser.
Architecture trade-off: Management said NPO is easier to deploy and service but costs power and signal integrity versus CPO, and that a common NPO socket can take silicon photonics or VCSELs. It positioned Coherent as an honest advisor because it can compare all the options. Chip-to-chip is a growing topic, with WDM and circulators important there.
Figure 5. COHR CPO Offerings
Source: COHR at ECOC 2026
Figure 6. COHR NPO Offerings
Source: COHR at ECOC 2026
Key takeaways from Citi discussion with management:
What is Coherent's competitive advantage in 3.2T, and will it participate? Management said it has already demonstrated the building blocks for the 3.2T generation, including 400G-per-lane EMLs and 400G silicon photonics, and expects to participate just as it enables 1.6T today. Management showed these demonstrations as early as two years ago.
What is the gross margin path, and what offsets mix pressure? Management mentioned that the 42%+ target was deliberately open-ended and that it expects to exceed it. It cautioned against expecting a step change over the next two to three quarters. Fast transceiver growth is a mix headwind, offset by overhead absorption, yield gains and factory consolidation. Management expects the 800Gto-1.6T transition to be margin-accretive, with the cutover forecast around 2028.
OCS, shipping for two to three quarters, is the first of the new platforms to generate revenue. OCS, CPO and multi-rail will contribute more to margins as mix builds.
What are the challenges and economics of the 6-inch InP transition?
Management said it announced 6-inch capability in March 2024 after years of work with substrate vendors that began before the AI boom. Output is expected to be roughly 50/50 between 3-inch and 6-inch by the end of the quarter, with all incremental capacity on 6-inch, reaching about 75% by the end of 2027. A 6-inch die costs about half as much per yielded die, and each line delivers about four times the capacity. Yields are better on modern tooling. Management cited a threeto-four-year lead over competitors and secured substrate supply from five suppliers across three continents. It also credited its 6-inch GaAs VCSEL line to a large consumer-electronics customer that demanded the larger wafer size.
Will Coherent keep external InP suppliers? COHR only sources EMLs externally and that it will keep some external supply for continuity on a critical component.
How does Coherent differ from Chinese laser suppliers? Management argued that module assembly is easier to replicate but high-speed lasers are not. It said there are no high-speed EMLs or broadband tunable lasers from China, and that Chinese CW lasers top out around 70-100 mW. It sees only one InP laser competitor worth naming and expects new Chinese module entrants to take share from existing Chinese suppliers rather than from Coherent.
Does NPO vs CPO matter for content, and can low-power lasers serve NPO?
Management said it does not matter much, because the components and dollar content are similar. Designs are custom and take 18 to 24 months to reach volume, and management reiterated scale-up production revenue in the second half of next year. Management rejected the view that NPO can use low-power lasers, arguing that coupling several weak lasers loses light and defeats the power-efficiency purpose.
What is multi-rail, and how is it progressing? Multi-rail addresses scale-across links between data centers. Management said it delivers four times the capacity in the same footprint at roughly 30% lower power per lane, enabled by a multi-chip uncooled pump that it says has no comparable competitor. Small shipments are underway and production shipments begin in the first half of next calendar year. It sells at the component, module, line-card and system level, including white-label to OEMs.
Coherent Corp
Company description
COHR is a vertically integrated manufacturing company that develops engineered materials and opto-electronic components for industrial materials processing, communications, aerospace and defense, consumer electronics, semiconductor capital equipment, life sciences and automotive end markets. COHR produces a wide variety of application-specific photonic and electronic materials and components, and deploys them in various forms, including integration with advanced software. COHR's customer base includes original equipment manufacturers, laser end users, system integrators of high-power lasers, manufacturers of equipment and devices for industrial, optical communications, consumer electronics, security and monitoring applications, U.S. government prime contractors, and various U.S. government agencies. COHR is a headquartered in Pennsylvania.
Investment strategy
We are Buy-rated on COHR. We believe that the stock's multiple will benefit from the AI appeal while its fundamentals should expand on new management's strong execution and focus on profitability.
Valuation
We value COHR at $420 or 30x forward P/E applied to FY2028 EPS of ~$16 discounted back. Our COHR valuation is nevertheless at a 10% discount to the average forward P/E of AI optics peers to reflect a lower AI sales mix and 3-year EPS CAGR vs peers such as LITE.
Risks
Downside risks to the achievement of our target price include: 1) increased competition on AI and SiC leads to limited market share growth and limited revenue upside, 2) inability to achieve synergies and margin targets established post acquisition of Finisar, and 3) prolonged economic recession leads to slower 5G build-out and lower consumer demand driving revenue of COHR down.
Upside risks to the achievement of our target price include: 1) gaining share in AI and SiC market through new product offerings and first to market status on larger wafer sizes, 2) quicker and stronger adoption of AI workloads, electric and autonomous vehicles, and 3) quicker return of margins to preFinisar acquisition levels.
If you are visually impaired and would like to speak to a Citi representative regarding the details of the graphics in this document, please call USA 1-888-500-5008 (TTY: 711), from outside the US +1-210-677-3788