PDF 原檔:報告_Citi_奇鋐3017_20261007_original.pdf
圖片清單(已驗證 2026-10-09)
| 檔名 | size | 分類 | 親眼所見內容 |
|---|---|---|---|
報告_Citi_奇鋐3017_20261007_001.png |
61KB | 真資料圖 | 「Figure 1. AVC – Quarterly sales trend」季營收柱狀圖(NT$mn)+QoQ/YoY折線,1Q21至3Q26E,2025年後營收與YoY明顯跳升 |
報告_Citi_奇鋐3017_20261007_002.png |
58KB | 真資料圖 | 「Figure 2. AVC – Monthly sales trend」月營收柱狀圖(NT$mn)+MoM/YoY折線,Jan-24至Sep-26 |
報告_Citi_奇鋐3017_20261007_003.png |
167KB | 真資料圖 | 奇鋐(3017.TW)評等與目標價歷史走勢圖+表格(2025-12-11至2026-09-17,目標價由2,055逐步調升至4,350),下半頁為Short-Term View/Catalyst Watch 標註圖 |
原始內容
[讀者資訊已遮蔽] citi
07 Oct 2026 10:51:03 ET │ 11 pages
Asia Vital Components (3017.TW)
Sep-26 Sales Lift 3Q26 Above Expectations; IBMJ Search Unrelated to Core Operations
CITI'S TAKE
AVC reported Sep-26 revenues of NT$21.0bn (+8% MoM/+45% YoY). 3Q26 revenues at NT$59.1bn (+20% QoQ/+52% YoY) beat Citi/cons (Bloomberg) forecasts by 4%/3%, mainly coming from stronger Trainium project demand and from the initial ramp of Vera Rubin. Looking into 4Q26E, we see multiple drivers supporting sequential growth, including Trainium project's shift to liquid cooling, TPU project entering mass production, and further ramp of Vera Rubin platform, while the additional capacity AVC has built will also join mass production. As such, we expect 4Q26E growth to remain solid. AVC also reported that the Investigation Bureau under the Ministry of Justice conducted a search and investigation at its Xinzhuang plant today (Oct 7). Based on our checks with mgmt, the search and interviews were related to matters during subsidiary Fositek's 2023 listing application and has no direct impact on AVC's operations. Maintain Buy.
Flash | Research
Buy
Price (07 Oct 26 13:30) NT$3,545.00
Target price NT$4,350.00
Expected share price return
22.7%
Expected dividend yield
0.6%
Expected total return Market Cap
23.3%
NT$1,392,016M
US$43,784M
Michael Hung AC
+886-2-8726-9092
michael.hung@citi.com
Laura (Chia Yi) Chen +886-2-8726-9090 laura.cy.chen@citi.com
See Appendix A-1 for Analyst Certification, Important Disclosures and Research Analyst Affiliations [讀者資訊已遮蔽]
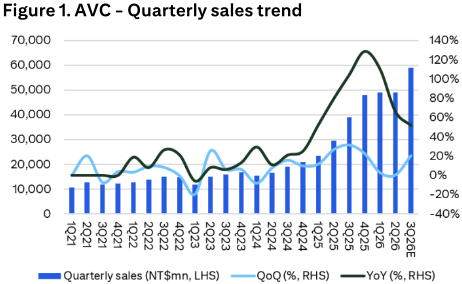
© 2026 Citigroup Inc. No redistribution without Citigroup's written permission. Source: Company Reports, Citi Research
Figure 2. AVC - Monthly sales trend
© 2026 Citigroup Inc. No redistribution without Citigroup's written permission. Source: Company Reports, Citi Research [讀者資訊已遮蔽]
Asia Vital Components
Valuation
We value AVC using a PE-based approach that factors in earnings momentum and the expansion of its addressable market. Our TP of NT$4,350 is derived from applying a 25x PE multiple on 2027E EPS, which we believe is justified given the company's entrenched positioned in the server thermal segment, rising contribution from liquid cooling, and the increasing value of thermal content per server as power density continues to climb. With these structural drivers still in place, we expect the multiple to hold at a premium relative to its historical averages.
Risks
This stock is High Risk based upon our quantitative model but assigning a High Risk rating is not supported by other qualitative factors such as cold-plate leadership and deep CSP penetration, and so a High Risk rating has not been applied. Key downside risks to our investment thesis and target price include: 1) slower adoption pace for liquid cooling adoption; 2) heightened price competition; 3) lower-than-expected share in liquid cooling components; and 4) emerging alternative cooling technologies.
[讀者資訊已遮蔽] If you are visually impaired and would like to speak to a Citi representative regarding the details of the graphics in this document, please call USA 1-888-500-5008 (TTY: 711), from outside the US +1-210-677-3788