PDF 原檔:報告_Citi_世界先進5347_20260928_original.pdf
圖片清單(已驗證 2026-09-29)
ingest 時建立的「眼見為憑」圖片索引,是 lib/ 嵌圖的唯一真相來源。
| 檔名 | size | 分類 | 親眼所見內容 |
|---|---|---|---|
報告_Citi_世界先進5347_20260928_001.png |
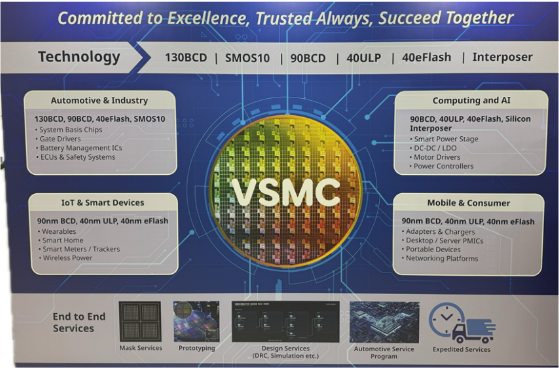
281KB | 真資料圖 | VSMC 開幕現場技術看板「Technology」:130BCD|SMOS10|90BCD|40ULP|40eFlash|Interposer;分四塊應用:Automotive & Industry(130BCD、90BCD、40eFlash、SMOS10;系統基礎晶片、閘極驅動、電池管理 IC、ECU 與安全系統)、Computing and AI(90BCD、40ULP、40eFlash、Silicon Interposer;Smart Power Stage、DC-DC/LDO、馬達驅動、電源控制器)、IoT & Smart Devices(90nm BCD、40nm ULP、40nm eFlash;穿戴、智慧家庭、智慧電表、無線電源)、Mobile & Consumer(90nm BCD、40nm ULP、40nm eFlash;充電器、桌機/伺服器 PMIC、可攜裝置、網通平台);下方 End to End Services:Mask/Prototyping/Design Services/Automotive Service Program/Expedited Services(報告 Figure 1,來源 Citi Research、Company Reports) |
報告_Citi_世界先進5347_20260928_002.png |
237KB | 文字卡 | 免責附錄頁:VIS、TSMC、NXP 的評等與目標價沿革表(含 VIS 目標價由 NT$60.01 至 NT$185.00 的歷次紀錄)與股價走勢,非新資訊 |
報告_Citi_世界先進5347_20260928_003.png |
317KB | 文字卡 | 免責附錄頁:TSMC/NXP/VIS 短期觀點(Catalyst Watch/Short-Term View)紀錄表,非新資訊 |
報告_Citi_世界先進5347_20260928_004.png |
127KB | 文字卡 | 免責附錄頁:TSMC 短期觀點紀錄表,非新資訊 |
註:002 圖實為 VIS/NXP 評等沿革(含股價走勢),屬揭露附錄,不嵌入 lib。
原始內容
Prepared for [讀者資訊已遮蔽] citi
28 Sep 2026 07:27:15 ET │ 13 pages
Vanguard International Semi. (5347.TWO)
VSMC Opening- From Buildout to Growth
CITI'S TAKE
We attended VSMC's opening ceremony in Singapore on Sep 28th. The event marked the formal transition of the VIS-NXP Singapore joint venture from construction since 2024 into an operating manufacturing platform, underscoring the strategic importance of the project for both partners. NXP highlighted the fab as a key source of 300mm capacity for automotive, industrial, mixed-signal, power management and edge-AI applications, while VIS emphasized supply-chain resilience, manufacturing excellence and long-term customer partnerships. TSMC also plays a critical role in the JV through technology transfer, employee training and operational support, and is an important customer for silicon interposer. The fab covers 130/90nm through 40nm-class specialty technologies with Phase 1 capacity ultimately reaching ~44K WPM. With TSMC's comprehensive support, particularly in the interposer business, VSMC is moving from execution risk toward utilization, product-mix improvement and earnings contribution, with 2027 set to become the first meaningful ramp year.
- Strategic JV + Ecosystem Extension - VSMC is becoming more than a normal 12-inch mature-node fab. VSMC is a VIS-NXP JV, with NXP serving as the key long-term partner and anchor customer for automotive, industrial, mixed-signal, power management and trusted edge/physical AI applications. At the same time, TSMC will become a deeper strategic partner: not only providing technology transfer, training and operational support, but also acting as a key customer for silicon interposer. Management expects to ramp up the capacity to 20kwpm by late 2027, out of the total planned capacity of 44kwpm. Moreover, management expects to achieve breakeven by the end of next year.
- ·Key Technology and Capacity: 130/90nm to 40nm. VSMC will support 130nm/90nm technology , with extension toward 40ULP, embedded Flash, mixed-signal, power management, analog and potentially other specialty platforms. On capacity, Phase 1 total capacity is now framed at around 44K WPM, with 2027 ramp potentially reaching ~20K WPM, faster than the original full-ramp schedule. Around 60% of capacity is covered by LTA; more importantly, silicon interposer is fully transferred from TSMC, with demand essentially coming from TSMC, making this less of a merchant foundry and more of a captive ecosystem-extension opportunity.
- ·AI-related revenue contribution expected to reach 25-30% in 2027. Management previously guided AI revenue exposure to reach double-digit in 2H26, but the latest messaging suggests AI exposure could rise toward
See Appendix A-1 for Analyst Certification, Important Disclosures and Research Analyst Affiliations
| Buy | |
|---|---|
| Price (24 Sep 26 15:00) | NT$170.50 |
| Target price | NT$185.00 |
| Expected share price return | 8.5% |
| Expected dividend yield | 4.2% |
| Expected total return | 12.7% |
| Market Cap | NT$320,285M |
| US$10,096M |
Laura (Chia Yi) Chen AC
+886-2-8726-9090 laura.cy.chen@citi.com
Jack Chen +886-2-8726-9091 jack1.chen@citi.com
Nicholas Lai +886-2-8726-9093 nicholas.lai@citi.com Prepared for [讀者資訊已遮蔽]
25-30% including power management IC and interposer. The profitability mix is also likely to improve because interposer is likely to be higher-margin than standard mature-node wafer revenue, while requiring limited incremental CapEx since the technology and demand are transferred from TSMC. Therefore, although depreciation will rise as VSMC enters production in 2027, margin pressure could be partly offset by higher utilization, LTA-backed loading, pricing support, and richer interposer/AI power mix. In short, 2027 could become an earnings inflection year for VSMC in Singapore rather than being burdened heavily by depreciation for VIS.
Figure 1. VIS - VSMC's Technology Offerings
© 2026 Citigroup Inc. No redistribution without Citigroup's written permission.
Source: Citi Research, Company Reports
Prepared for [讀者資訊已遮蔽]
Vanguard International Semi.
Valuation
Our target price for VIS of NT$185 is based on 25x 2027E P/E, which we see as justified by its robust PMIC sales growth momentum and increasing outflow order opportunity from TSMC with support from its consistent cash dividend policy. Our target price equates to 2026/27E P/B of 3.6x/3.5x.
Risks
Key downside risks to our target price include: 1) weaker 8-inch demand along with higher costs due to inflation or more severe ASP competition from Chinese peers; 2) lower UTR of the new capacity at the newly acquired fab, with depreciation burden; and 3) less-than-expected outsourcing opportunities from IDMs.
NXP Semiconductors NV
(NXPI.O; US$238.08; 1; 25 Sep 26; 16:00)
Valuation
Our price target of $370 is based on a 17x P/E applied to CY28 EPS, given peer multiple expansion tied to rising data center exposure.
Risks
End Market: NXP derives roughly 55% of sales from the automotive end market and roughly 18% of sales from the industrial end market. Therefore, any major changes in auto sales or industrial activity could result in upside/downside to our estimates and target price for NXP.
Competition: NXP competes with several companies in analog, digital, and microcontrollers. Consequently, any changes in market share could result in upside/downside risk to our estimates and target price.
Inventory Risk: NXP sells roughly 50-60% of its products through distributors. As a result, we believe any major fluctuations of inventory in the distribution channel could result in upside/downside risk to our estimates and target price.
Macroeconomic: NXP's geographic exposure spans multiple geographies including the U.S., Europe, and Asia. As a result, any prolonged macroeconomic strength/weakness could result in upside/downside to our estimates and target price.
TSMC
(2330.TW; NT$2475.0; 1; 24 Sep 26; 13:30)
Valuation
Our target price for TSMC shares of NT$3,800 is based on 25x the average of our 2027E EPS, higher than its three-year average forward PER, versus global peers' average of 15-23x. We believe our PER target is justified by TSMC's leading position in advanced process node and robust AI demand growth outlook. Given its continuing leadership in the semiconductor foundry industry, we believe TSMC's stable order visibility and earnings outlook make it less vulnerable than peers to a potential global economic downturn. Our target price equates to 2026E/27E P/E of 34x/25x and 2026E/27E P/B of 13x/10x.
Risks
Key downside risks that could impede the shares from achieving our target price include: 1) weakness in the global semiconductor market; 2) larger-than-expected margin contractions due to depreciation cost hikes and strong NTD; 3) competitors entering the foundry business; 4) longer-than-expected digestion of inventory in the supply chain; and 5) a slowdown in demand either from a global economic downturn or a global trade disruption triggered by tariffs.
Prepared for [讀者資訊已遮蔽] If you are visually impaired and would like to speak to a Citi representative regarding the details of the graphics in this document, please call USA 1-888-500-5008 (TTY: 711), from outside the US +1-210-677-3788