PDF 原檔:報告_Daiwa_南亞科2408_20261007_original.pdf
圖片清單(已驗證 2026-10-12)
5 張抽圖皆 <40KB,因皆為圖表仍逐張檢視;lib 嵌圖只從此清單挑「真資料圖」。
| 檔名 | size | 分類 | 親眼所見內容 |
|---|---|---|---|
報告_Daiwa_南亞科2408_20261007_001.png |
22KB | 真資料圖 | Nanya Tech 股價(左軸 TWD)與相對加權指數(右軸 %)走勢,Oct-25 至 Oct-26,股價自約 80 元升至逾 500 元 |
報告_Daiwa_南亞科2408_20261007_002.png |
18KB | 真資料圖 | 季營收(長條,TWD bn)與營益率(折線):1Q26 至 4Q27E 季度走勢,營益率自約 61% 升至約 81% 後持平 |
報告_Daiwa_南亞科2408_20261007_003.png |
31KB | 真資料圖 | 月營收(長條,TWD mn)與 YoY(折線):Sep-24 至 Sep-26,Jul-26 起三根淺藍長條約 4.4–4.5 萬 |
報告_Daiwa_南亞科2408_20261007_004.png |
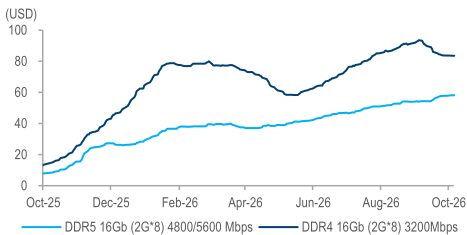
26KB | 真資料圖 | DRAM 現貨價走勢(USD):DDR5 16Gb 4800/5600Mbps 與 DDR4 16Gb 3200Mbps,Oct-25 至 Oct-26;DDR4 約 13 美元升至 Sep-26 高點約 93 美元後回落至約 83 美元,DDR5 約 8 美元升至約 58 美元 |
報告_Daiwa_南亞科2408_20261007_005.png |
29KB | 真資料圖 | 12 個月 forward PER 區間圖(Oct-19 至 Oct-26,股價線與 3.2x/4.2x/5.2x/6.2x/7.2x 五條倍數線) |
原始內容
Nanya Technology (2408 TT)
Target price: TWD700.00 (from TWD650.00)
Shareprice(7Oct):TWD514.00 | Up/downside:+36.2%
Robust revenue likely to drive earnings beat
- 3Q26E earnings to beat consensus estimate, led by DRAM prices
- DDR4 supply shortages to persist in 2027E; upcoming dividend policy
- Reaffirming our Buy (1) call and lifting our 12M TP to TWD700
What's new: Nanya announced its September revenue after market hours on 5 October. Following the significant jump in July revenue (49% MoM, 720% YoY, see our memo), it maintained stable revenue in August and September, resulting in robust revenue growth in 3Q26. We also expect its operating profit to beat consensus, led by higher DRAM prices. While demand for DDR3/DDR4 remains solid, we expect supply shortages to continue in 2027, given major memory players' focus on DDR5 production. We also expect Nanya to announce shareholder returns, primarily in the form of dividends, during its 3Q26 earnings conference call.
What's the impact: 3Q26E earnings to beat consensus. Nanya posted revenue of TWD134bn (+62% QoQ, +612% YoY) in 3Q26, beating the Bloomberg consensus by 16%. We also estimate its operating profit at TWD109bn (+79% QoQ, +9,608% YoY), above consensus. We forecast bit shipments to increase by 5% QoQ and DRAM ASPs to rise by 53% QoQ, exceeding our and market estimates. With DDR3/DDR4 demand remaining robust, we expect major memory players' focus on DDR5 production to drive supply shortages, resulting in higher prices in 3Q26. We expect further earnings improvement in 4Q26, driven by persistent price hikes.
DDR4 supply shortages to continue in 2027E; enhanced dividend policy expected. During the meeting in July, management said it expects long-term solid demand for DDR4 in eSSD and networking applications. Based on long-term agreements (LTAs) with major customers, we expect Nanya to expand its DDR4 supply for eSSD. We estimate that the 1B node will account for c.40% of DRAM output in 4Q26, with new capacity starting mass production in 3Q27. On capex, we expect the company to exceed its 2026 guidance of TWD50bn to keep up with end-market demand and LTA volumes, and to more than double capex YoY in 2027. For shareholder returns, we expect an additional policy to be announced at the 3Q26 conference call. While the company has guided for a payout ratio of c.40%, we expect it to exceed 50%, given the faster-than-expected growth. We raise our 2026-27E EPS by 30-38% to reflect higher DDR3/4 DRAM prices.
What we recommend: We reiterate our Buy (1) rating and raise our 12month TP to TWD700 (from TWD650), based on a target PER of 7.4x (from 9.2x) applied to our 2026-27E EPS. We lower our target multiple by 20% to reflect the recent derating of peer valuations. Downside risk: Delays in data centre build-outs.
How we differ: Our 2026-27E EPS are 6-13% above the Bloomberg consensus, likely as we are more positive about the DDR4 price outlook.
3
2
1
(unchanged)
SK Kim (82) 2 787 9173 sk.kim@kr.daiwacm.com
Forecast revisions (%)
| Year to 31 Dec | 26E | 27E | 28E |
|---|---|---|---|
| Revenue change | 21.0 | 32.8 | 43.1 |
| Net profit change | 27.0 | 38.2 | 71.1 |
| Core EPS (FD) change | 30.4 | 38.2 | 71.1 |
Source: Daiwa forecasts
Share price performance
| 12-month range | 86.30-543.00 |
|---|---|
| Market cap (USDbn) | 52.92 |
| 3m avg daily turnover (USDm) | 1,082.62 |
| Shares outstanding (m) | 3,274 |
| Major shareholder | Nanya Plastics Corp (29.3%) |
Financial summary (TWD)
| Year to 31 Dec | 26E | 27E | 28E |
|---|---|---|---|
| Revenue (m) | 401,091 | 625,829 | 687,408 |
| Operating profit (m) | 309,869 | 502,559 | 531,635 |
| Net profit (m) | 251,467 | 394,862 | 447,508 |
| Core EPS (fully-diluted) | 76.797 | 114.446 | 129.705 |
| EPS change (%) | n.a. | 49.0 | 13.3 |
| Daiwa vs Cons. EPS (%) | 12.6 | 6.3 | 7.6 |
| PER (x) | 6.7 | 4.5 | 4.0 |
| Dividend yield (%) | 8.2 | 12.2 | 15.1 |
| DPS | 42.2 | 62.9 | 77.8 |
| PBR (x) | 3.4 | 2.4 | 1.8 |
| EV/EBITDA (x) | 4.3 | 2.4 | 2.1 |
| ROE (%) | 44.9 | 63.3 | 51.3 |
Source: FactSet, Daiwa forecasts
Nanya: 3Q26 preview
| (TWDm) | 3Q26E | 2Q26 | QoQ growth | 3Q25 | YoY growth | BBG consensus | Diff |
|---|---|---|---|---|---|---|---|
| Revenue | 133,649 | 82,549 | 62% | 18,779 | 612% | 115,222 | 16% |
| Operating Profit | 108,647 | 60,826 | 79% | 1,119 | 9608% | 90,376 | 20% |
| OP margin | 81.3% | 73.7% | 6.0% | 78.4% |
Source: Company, Bloomberg
Note: Bloomberg consensus as of 7 October 2026, 3Q26 revenue reflects actual figures (September data announced on 5 October).
Nanya: earnings outlook
| (TWDm) | 1Q26 | 2Q26 | 3Q26E | 4Q26E | 2025 | 2026E | 2027E | 2028E |
|---|---|---|---|---|---|---|---|---|
| Revenue | 49,087 | 82,549 | 133,649 | 135,806 | 66,587 | 401,091 | 625,829 | 687,408 |
| Operating profit | 30,111 | 60,826 | 108,647 | 110,284 | 5,243 | 309,869 | 502,559 | 531,635 |
| OP margin (%) | 61.3% | 73.7% | 81.3% | 81.2% | 7.9% | 77.3% | 80.3% | 77.3% |
| Net profit | 26,059 | 50,192 | 87,301 | 87,916 | 6,603 | 251,467 | 394,862 | 447,508 |
Source: Company, Daiwa forecasts
Nanya: key assumptions
| 1Q26 | 2Q26 | 3Q26E | 4Q26E | 2025 | 2026E | 2027E | 2028E | |
|---|---|---|---|---|---|---|---|---|
| DRAM | ||||||||
| Bit growth (q-q%) | 1.0% | -2.9% | 4.8% | -5.0% | 53.8% | 32.9% | 3.2% | 16.5% |
| ASP (q-q%) | 56.3% | 68.0% | 52.7% | 7.5% | 22.7% | 348.3% | 50.0% | -5.2% |
Source: Company, Daiwa forecasts
Nanya: revenue and operating margin forecasts
Nanya: monthly revenue and growth YoY trend
Source: Company, Daiwa forecasts
DRAM spot price trend
Source: Company
Nanya: 12-month forward PER band
Source: DRAM eXchange, Daiwa
Note: As of 7 October, 2026
Nanya: peers valuation comparison
| Company | Ticker - (Bloomberg) | Recom. | Price curr) - (Local | Mkt cap (USD - $m) | FY26E | P/E (x) - FY27E | FY26E | P/BV (x) - FY27E | FY26E | ROE (%) - FY27E | EV/EBITDA - FY26E | EV/EBITDA - FY27E | Div yield (%) - FY26E | Div yield (%) - FY27E |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Coverage | ||||||||||||||
| Nanya Technology | 2408 TT | Buy | 514 | 55,870 | 6.7 | 4.5 | 3.4 | 2.4 | 44.9% | 63.3% | 4.3 | 2.4 | 8.2% | 12.2% |
| Semiconductor | ||||||||||||||
| Samsung Electronics | 005930 KS | Buy | 268,500 | 1,189,218 | 6.4 | 3.7 | 2.9 | 1.7 | 48.8% | 56.0% | 3.5 | 1.6 | 3.7% | 4.6% |
| SK Hynix | 000660 KS | Buy | 1,723,000 | 952,413 | 5.3 | 3.5 | 3.2 | 1.6 | 94.3% | 59.1% | 3.7 | 1.5 | 0.3% | 0.5% |
| Micron Technology | MU US | Buy | 1,046 | 1,180,848 | 13.8 | 5.7 | 8.6 | 3.7 | 46.3% | 48.9% | 10.1 | 3.9 | 0.0% | 0.1% |
| Winbond | 2344 TT | Not Rated | 180 | 25,279 | 6.9 | 2.6 | 3.5 | 1.8 | 64.6% | 71.1% | 4.8 | 2.0 | 4.5% | 10.4% |
| Average | 8.1 | 3.9 | 4.55 | 2.2 | 63.5% | 58.8% | 5.5 | 2.3 | 2.1% | 3.9% |
Source: Bloomberg, Daiwa forecasts
Note: Share price as of 7 October 2026, Oversea companies as of 6 October 2026
Source: Company, Bloomberg, Daiwa forecasts
Financial summary
Key assumptions
| Year to 31 Dec | 2021 | 2022 | 2023 | 2024 | 2025 | 2026E | 2027E | 2028E |
|---|---|---|---|---|---|---|---|---|
| DRAM bit growth (%) | (0.5) | (27.4) | (4.3) | 0.9 | 53.8 | 32.9 | 3.2 | 16.5 |
| DRAM ASP (%) | 50.7 | (16.8) | (44.7) | 11.3 | 22.7 | 348.3 | 50.0 | (5.2) |
| Wafer capacity per month | 73.0 | 66.3 | 55.8 | 61.3 | 60.0 | 72.5 | 86.3 | 106.3 |
Profit and loss (TWDm)
| Year to 31 Dec | 2021 | 2022 | 2023 | 2024 | 2025 | 2026E | 2027E | 2028E |
|---|---|---|---|---|---|---|---|---|
| DRAM | 85,604 | 56,952 | 29,892 | 34,132 | 66,607 | 402,584 | 625,829 | 687,408 |
| Other Revenue | n.a. | n.a. | n.a. | n.a. | n.a. | n.a. | n.a. | n.a. |
| Total Revenue | 85,604 | 56,952 | 29,892 | 34,132 | 66,587 | 401,091 | 625,829 | 687,408 |
| Other income | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| COGS | (48,560) | (35,610) | (34,375) | (34,552) | (51,602) | (74,751) | (105,419) | (138,732) |
| SG&A | (2,358) | (2,498) | (2,401) | (2,449) | (2,700) | (8,121) | (12,315) | (12,137) |
| Other op.expenses | (7,500) | (7,841) | (7,576) | (7,685) | (7,041) | (8,350) | (5,536) | (4,904) |
| Operating profit | 27,186 | 11,002 | (14,460) | (10,555) | 5,243 | 309,869 | 502,559 | 531,635 |
| Net-interest inc./(exp.) | 250 | 1,346 | 3,014 | 2,974 | 1,907 | 2,159 | 574 | 578 |
| Assoc/forex/extraord./others | 331 | 4,529 | 742 | 1,103 | 732 | 1,040 | 136 | 534 |
| Pre-tax profit | 27,767 | 16,877 | (10,705) | (6,477) | 7,882 | 313,068 | 503,269 | 532,747 |
| Tax | (4,918) | (2,258) | 3,265 | 1,055 | (1,279) | (61,602) | (108,407) | (85,240) |
| Min. int./pref. div./others | 0 | 0 | 0 | 0 | 0 | 2 | 1 | 1 |
| Net profit (reported) | 22,849 | 14,619 | (7,440) | (5,422) | 6,603 | 251,467 | 394,862 | 447,508 |
| Net profit (adjusted) | 22,849 | 14,619 | (7,440) | (5,422) | 6,603 | 251,467 | 394,862 | 447,508 |
| EPS (reported)(TWD) | 7.378 | 4.720 | (2.401) | (1.750) | 2.131 | 76.797 | 114.446 | 129.705 |
| EPS (adjusted)(TWD) | 7.378 | 4.720 | (2.401) | (1.750) | 2.131 | 76.797 | 114.446 | 129.705 |
| EPS (adjusted fully-diluted)(TWD) | 7.378 | 4.720 | (2.401) | (1.750) | 2.131 | 76.797 | 114.446 | 129.705 |
| DPS (TWD) | 1.292 | 3.703 | 0.000 | 0.000 | 1.501 | 42.239 | 62.945 | 77.823 |
| EBIT | 27,186 | 11,002 | (14,460) | (10,555) | 5,243 | 309,869 | 502,559 | 531,635 |
| EBITDA | 42,480 | 26,249 | 865 | 5,589 | 19,524 | 323,312 | 520,319 | 553,735 |
Cash flow (TWDm)
| Year to 31 Dec | 2021 | 2022 | 2023 | 2024 | 2025 | 2026E | 2027E | 2028E |
|---|---|---|---|---|---|---|---|---|
| Profit before tax | 27,767 | 16,877 | (10,705) | (6,477) | 7,882 | 313,068 | 503,269 | 532,747 |
| Depreciation and amortisation | 15,294 | 15,247 | 15,326 | 16,144 | 14,281 | 13,443 | 17,760 | 22,100 |
| Tax paid | (4,918) | (2,258) | 3,265 | 1,055 | (1,279) | (61,602) | (108,407) | (85,240) |
| Change in working capital | 130 | (6,179) | (6,486) | (8,461) | (3,638) | (57,621) | (32,239) | 1,181 |
| Other operational CF items | 6,160 | (2,251) | (7,028) | (182) | 1,528 | 19,312 | (10,479) | (10,966) |
| Cash flow from operations | 44,433 | 21,436 | (5,628) | 2,079 | 18,774 | 226,600 | 369,905 | 459,822 |
| Capex | (11,260) | (20,711) | (13,245) | (16,143) | (13,446) | (59,235) | (122,482) | (143,030) |
| Net (acquisitions)/disposals | 0 | 0 | 0 | 0 | (612) | 0 | 0 | 0 |
| Other investing CF items | 5 | (511) | (8) | (172) | (257) | (315) | (333) | (331) |
| Cash flow from investing | (11,255) | (21,222) | (13,253) | (16,315) | (14,315) | (59,551) | (122,815) | (143,360) |
| Change in debt | (71) | 2,837 | 11,117 | 14,041 | (6,102) | (2,246) | 426 | 24 |
| Net share issues/(repurchases) | 1,261 | 55 | 5 | 11 | 0 | 157,437 | 0 | 0 |
| Dividends paid | (4,000) | (11,470) | (6,600) | 0 | 0 | (4,650) | (138,308) | (217,175) |
| Other financing CF items | (250) | (3,193) | (326) | (345) | (215) | 139 | 202 | 203 |
| Cash flow from financing | (3,060) | (11,771) | 4,196 | 13,707 | (6,317) | 150,679 | (137,679) | (216,948) |
| Forex effect/others | 323 | (3,190) | 38 | (697) | (180) | (201) | 484 | 142 |
| Change in cash | 30,441 | (14,748) | (14,647) | (1,226) | (2,038) | 317,528 | 109,894 | 99,655 |
| Free cash flow | 33,173 | 724 | (18,873) | (14,063) | 5,328 | 167,365 | 247,422 | 316,792 |
Source: FactSet, Daiwa forecasts
Financial summary continued …
Balance sheet (TWDm)
| Year to 31 Dec | 2021 | 2022 | 2023 | 2024 | 2025 | 2026E | 2027E | 2028E |
|---|---|---|---|---|---|---|---|---|
| Cash & short-term investment | 80,700 | 73,593 | 58,812 | 61,903 | 58,074 | 310,848 | 434,828 | 551,120 |
| Inventory | 11,611 | 23,384 | 27,634 | 35,318 | 27,288 | 20,578 | 26,119 | 34,373 |
| Accounts receivable | 11,569 | 4,359 | 5,220 | 4,132 | 16,558 | 89,501 | 139,649 | 153,390 |
| Other current assets | 2,580 | 4,175 | 4,844 | 6,593 | 6,621 | 5,891 | 5,786 | 5,777 |
| Total current assets | 106,460 | 105,512 | 96,510 | 107,946 | 108,541 | 426,818 | 606,382 | 744,660 |
| Fixed assets | 77,914 | 89,421 | 86,263 | 88,677 | 89,257 | 130,431 | 235,153 | 356,083 |
| Goodwill & intangibles | 1,014 | 767 | 927 | 688 | 531 | 872 | 832 | 792 |
| Other non-current assets | 6,034 | 6,536 | 8,650 | 9,396 | 10,124 | 8,249 | 8,249 | 8,249 |
| Total assets | 191,421 | 202,236 | 192,351 | 206,706 | 208,453 | 566,369 | 850,616 | 1,109,784 |
| Short-term debt | 215 | 361 | 11,574 | 21,687 | 5,517 | 448 | 396 | 351 |
| Accounts payable | 15,477 | 15,818 | 8,544 | 11,093 | 13,503 | 49,964 | 73,310 | 96,476 |
| Other current liabilities | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| Total current liabilities | 15,692 | 16,179 | 20,118 | 32,780 | 19,020 | 50,412 | 73,706 | 96,827 |
| Long-term debt | 1,510 | 4,200 | 4,104 | 8,032 | 18,101 | 20,924 | 21,401 | 21,470 |
| Other non-current liabilities | 1,242 | 898 | 1,205 | 841 | 794 | 1,142 | 1,213 | 1,223 |
| Total liabilities | 18,443 | 21,278 | 25,427 | 41,653 | 37,914 | 72,477 | 96,321 | 119,521 |
| Share capital | 30,973 | 30,981 | 30,981 | 30,981 | 30,981 | 34,497 | 34,497 | 34,497 |
| Reserves/R.E./others | 142,005 | 149,977 | 135,943 | 134,072 | 139,419 | 459,257 | 719,661 | 955,628 |
| Shareholders' equity | 172,978 | 180,958 | 166,924 | 165,053 | 170,400 | 493,754 | 754,158 | 990,125 |
| Minority interests | 0 | 0 | 0 | 0 | 139 | 138 | 138 | 138 |
| Total equity & liabilities | 191,421 | 202,236 | 192,351 | 206,706 | 208,453 | 566,369 | 850,616 | 1,109,784 |
| EV | 1,604,075 | 1,614,018 | 1,639,917 | 1,650,867 | 1,648,732 | 1,393,712 | 1,270,158 | 1,153,890 |
| Net debt/(cash) | (78,975) | (69,032) | (43,134) | (32,183) | (34,457) | (289,477) | (413,030) | (529,299) |
| BVPS (TWD) | 55.856 | 58.426 | 53.881 | 53.274 | 54.992 | 150.791 | 218.583 | 286.976 |
Key ratios (%)
| Year to 31 Dec | 2021 | 2022 | 2023 | 2024 | 2025 | 2026E | 2027E | 2028E |
|---|---|---|---|---|---|---|---|---|
| Sales (YoY) | 40.3 | (33.5) | (47.5) | 14.2 | 95.1 | 502.4 | 56.0 | 9.8 |
| EBITDA (YoY) | 85.6 | (38.2) | (96.7) | 545.8 | 249.3 | 1,555.9 | 60.9 | 6.4 |
| Operating profit (YoY) | 222.3 | (59.5) | n.a. | n.a. | n.a. | 5,809.8 | 62.2 | 5.8 |
| Net profit (YoY) | 197.3 | (36.0) | n.a. | n.a. | n.a. | 1,471.4 | 57.0 | 13.3 |
| Core EPS (fully-diluted) (YoY) | 195.0 | (36.0) | n.a. | n.a. | n.a. | 3,504.2 | 49.0 | 13.3 |
| Gross-profit margin | 43.3 | 37.5 | n.a. | n.a. | 22.5 | 81.4 | 83.2 | 79.8 |
| EBITDA margin | 49.6 | 46.1 | 2.9 | 16.4 | 29.3 | 80.6 | 83.1 | 80.6 |
| Operating-profit margin | 31.8 | 19.3 | (48.4) | (30.9) | 7.9 | 77.3 | 80.3 | 77.3 |
| Net profit margin | 26.7 | 25.7 | n.a. | n.a. | 9.9 | 62.7 | 63.1 | 65.1 |
| ROAE | 14.0 | 8.3 | n.a. | n.a. | 3.9 | 44.9 | 63.3 | 51.3 |
| ROAA | 12.8 | 7.4 | n.a. | n.a. | 3.2 | 64.9 | 55.7 | 45.7 |
| ROCE | 16.5 | 6.1 | n.a. | n.a. | 2.7 | 87.4 | 77.8 | 59.5 |
| ROIC | 22.6 | 9.3 | n.a. | n.a. | 3.8 | n.a | n.a | n.a |
| Net debt to equity | n.a. | n.a. | n.a. | n.a. | n.a. | n.a. | n.a. | n.a. |
| Effective tax rate | 17.7 | 13.4 | 30.5 | 16.3 | 2.9 | 1.8 | 1.7 | 1.7 |
| Accounts receivable (days) | 41.5 | 51.0 | 58.5 | 50.0 | 56.7 | 48.3 | 66.8 | 77.8 |
| Current ratio (x) | 6.8 | 6.5 | 4.8 | 3.3 | 5.7 | 8.5 | 8.2 | 7.7 |
| Net interest cover (x) | n.a. | n.a. | n.a. | n.a. | n.a. | n.a. | n.a. | n.a. |
| Net dividend payout | 17.5 | 78.5 | n.a. | n.a. | 70.4 | 55.0 | 55.0 | 60.0 |
| Free cash flow yield | 2.0 | 0.0 | n.a. | n.a. | 0.3 | 9.9 | 14.7 | 18.8 |
Source: FactSet, Daiwa forecasts
Company profile
Nanya manufactures dynamic random access memory (DRAM). Focusing on consumer DRAM market, Nanya had developed its technology through cooperation with other advanced suppliers such as Micron. Recently, as the fourth largest player in the global DRAM market, Nanya plans to apply its own process (1anm, 1bnm) developed to manufacture DRAM, targeting the mobile and server DRAM market. Nanya currently has wafer capacity of c.70k units, of which the 20nm-process accounts for 80% and is centred in Taiwan.
ESG analysis
ESG risks
| Risks | Management | Analystcomments |
|---|---|---|
| Executive/board quality | 2 | Nanya is making an effort to ensure the quality of its board by appointing technology and accounting experts. The Board comprises 9 internal and 3 independent directors, 3 of whom are accounting experts and 6 are technology experts. Two of the directors are female and 4 directors are managerial officers of Nanya, including personnel from Nanya Plastic and Formosa. |
| G Capital management | 1 | The company plans to increase its capex to TWD16bn for 2025 . |
| Related party & transaction | 1 | Nanya has no actual or proposed related-party transaction that exceeds 1% of its revenue. The company commented that the terms and pricing of sales with associates did not significantly differ from its normal selling prices. |
| S Supplychain management | 1 | Nanya has multiple material suppliers to reduce its purchasing risk. The number of major suppliers increased to 412 in 2024 from 304 in 2020. Nanya is working with suppliers to construct a resilient and stable supply chain. |
| E Water&wastewater management | 1 | Nanya targets to maintain its water recycling ratio at over 95% through a complete water recycling chain. In 2024, it achieved a 97%water recovery ratio (vs. 87% in 2020), thanks to its wastewater processing effort. Nanya has water supply from its backup wells (400m deep) and water tanks. It maintains 143 days of normal production at its plants with 2,000 CMD of well water. |
| E Waste & hazardous materials management | 2 | Nanya increased its waste recycling and reuse rate to 99% in 2024 (vs. 89.6% in 2019). The company has conducted on-site audits and assists its suppliers with waste disposal. Also, Nanya reviewed 51 raw material suppliers for RoHS terms, and had a 100% rate of completion in 2024. |
| E GHGemissions | 2 | The main sources of greenhouse gas (GHG) emissions are purchased electricity, which accounted for c.86% of Nanya's GHG emissions in 2024. Accordingly, Nanya has set a long- term goal of replacing coal-fired electricity with natural gas and implementing a green energy programme by using solar panels to reduce GHG emissions. On 7 October 2022, Science Based Targets initiative (SBTi) approved Nanya's GHG emission reduction target, ensuring its emission reduction roadmap is consistent with the Paris Agreement. With 2020 as the base year, Nanya targets a 25% reduction in GHG emissions (scope 1 and scope 2) and a 27% reduction in emissions per unit product (scope 3) by 2030. |
Note: Management score represents a company's ability to manage/benefit from certain ESG topics. The scores range from 1 to 3, with 1 being the strongest.
Update Date: 2 Jan 2026
Source: Daiwa, Company