PDF 原檔:報告_Citi_鴻勁7769_20261007_original.pdf
圖片清單(已驗證 2026-10-09)
| 檔名 | size | 分類 | 親眼所見內容 |
|---|---|---|---|
報告_Citi_鴻勁7769_20261007_001.png |
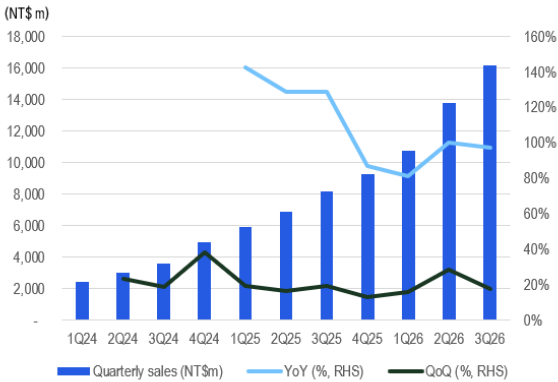
49KB | 真資料圖 | 「Figure 1. Hon – Quarterly Revenues Trend」柱狀圖:近期季營收明顯放大、柱體創圖中歷史新高(對應正文 3Q 達 NT$16bn) |
報告_Citi_鴻勁7769_20261007_002.png |
127KB | 真資料圖 | 雙圖:上「Ratings and Target Price History」表(僅 1 筆:2026-05-28 評等 Buy、TP NT$11,000);下「Short-Term View/Catalyst Watch Research」表(2 筆 CW 新增/移除標記),皆疊加股價走勢圖 |
原始內容
[讀者資訊已遮蔽] citì
07 Oct 2026 06:24:46 ET │ 10 pages
Hon Precision (7769.TW)
Strong revenues beat with 3Q26 reaching the record high
CITI'S TAKE
Hon reported Sep revenues of NT$5.7bn which grew 100% YoY and 10% MoM, driven by continued FT/SLT handler build-up by OSAT clients for next generation AI chips and solid cold plates demand. This brought 3Q sales to NT$16bn (+98% YoY and +17% QoQ), registering another quarterly record high and beating Street and our estimates by 17% and 9%, respectively. Looking ahead, we see sequential QoQ sales growth into next year supported by robust order momentum from AI ASIC and US EV FT/SLT project and sustained capacity build-up demand with OSATs' strong expansion in SEA and US region. With new capacity coming online from 4Q26 onwards, stronger >50% capacity growth in 2027 and more upside potentials from content expansion in 2027 on accelerating adoption of large tray handler, AOI functions and higher TDP requirement, we estimate Hon's 2027/28 earnings to deliver strong growth of 86%/74% respectively. Buy.
Figure 1. Hon - Quarterly Revenues Trend
© 2026 Citigroup Inc. No redistribution without Citigroup's written permission. Source: Citi Research
See Appendix A-1 for Analyst Certification, Important Disclosures and Research Analyst Affiliations
| Buy | |
|---|---|
| Price (07 Oct 26 13:30) | NT$5,885.00 |
| Target price | NT$11,000.00 |
| Expected share price return | 86.9% |
| Expected dividend yield | 0.6% |
| Expected total return | 87.5% |
| Market Cap | NT$1,058,888M |
| US$33,306M |
Nicholas Lai AC
+886-2-8726-9093 nicholas.lai@citi.com
Laura (Chia Yi) Chen +886-2-8726-9090 laura.cy.chen@citi.com
Jack Chen +886-2-8726-9091 jack1.chen@citi.com
Michael Hung +886-2-8726-9092 michael.hung@citi.com [讀者資訊已遮蔽]
Hon Precision
Valuation
Our target price of NT$11,000 is based on a target PER multiple of 36x applied to the average of our 2027E/28E EPS estimates. Our PER target of 35x is set at 1-std above its 1-year PER average, justified by its high share of the AI/HPC testing handler market, which we estimate could support an earnings CAGR of 77% in 2025-28, higher than its 3-year CAGR at c40% in 202225. Our estimated 77% earning CAGR is also higher than the +40% average (Bloomberg consensus) of its global testing equipment peers. As its peers have been trading at average 36x PER on 2027/28 consensus EPS in the past 1 year, we believe Hon Precision deserves a further re-rating to our target PER of 36x.
Risks
Our quantitative risk rating system, which looks at historical share price volatility, rates Hon Precision High Risk. However, we are not assigning a High Risk rating as we forecast an earnings CAGR of >75%, significantly stronger than the growth outlook for its global peers. Also, we note its dominant position in AI/HPC handler market and expanding market TAM opportunity, which support our constructive view over its growth outlook.
Key downside risks that could impede the shares from reaching our target price: 1) Global AI demand slowdown driving weaker capacity build for semiconductor equipment; 2) unexpected share losses at its major AI projects; 3) slower-than-expected capacity ramp at its new facilities, or the company taking a long time to find/secure new sites; 4) slower-than-expected development of its CPO business; 5) shorter-than-expected testing time leading to lower demand for its products; 6) weak adoption of high-premium cold plate products; and 7) increasing competition from new entrants.
[讀者資訊已遮蔽] If you are visually impaired and would like to speak to a Citi representative regarding the details of the graphics in this document, please call USA 1-888-500-5008 (TTY: 711), from outside the US +1-210-677-3788