PDF 原檔:報告_GS_亞德客1590_20261012_original.pdf
圖片清單(已驗證 2026-10-13)
| 檔名 | size | 分類 | 親眼所見內容 |
|---|---|---|---|
報告_GS_亞德客1590_20261012_001.png |
89KB | 真資料圖 | Exhibit 2:長條圖+折線圖,2021/10–2026/9 AirTAC 月營收(人民幣百萬元,淺藍色長條,左軸)與 YoY 增速(綠色折線,右軸);標題「We estimate AirTAC's October revenue will increase by 16% YoY」,最右側一根紅色長條為 2026 年 10 月估計值 |
報告_GS_亞德客1590_20261012_002.png |
73KB | 真資料圖 | 雙軸圖,標題「Airtac International Group (1590.TW) — Goldman Sachs rating and stock price target history」;灰線為台灣加權指數、淺藍線為 AirTAC 股價(右軸,index 值)、藍色方塊為歷次目標價調整點(1300/1350/1120/1100/1060/1096/1020/1085/1240/1310/1505/1725/1925),時間軸 2023–2026,評等區間標示「B」(Buy) |
原始內容
[讀者資訊已遮蔽]
Airtac International Group (1590.TW): Sep Monthly revenue -3% vs. GSe; New orders continue to exceed shipments despite low season; Buy
On October 12th, AirTAC reported September revenue of Rmb806mn (+3% MoM, +14% YoY) / NT$3,811mn (+3% MoM, +27% YoY), which was 3% below GSe in Rmb terms.
In September, AirTAC's revenue was 3% below GSe in Rmb terms, up 3% MoM with 2% more working days. This came in slightly below our estimates, primarily due to (1) normal low season effect with daily pneumatic revenue increasing by 1% MoM at Rmb29.4mn (vs. Rmb35.4mn in 2Q26), which is tracking lower than our estimates of Rmb32.1mn and (2) slightly weaker-than-expected linear guide revenue contribution (Rmb64mn slightly missed GSe of Rmb68mn), but the daily average linear guides revenue is higher at Rmb2.7mn (vs. Rmb2.5mn in August).
Moreover, September revenue was up 14% YoY (in Rmb) with 4% less working days vs. September 2025. We believe this solid YoY revenue growth was driven by (1) the strong performance in electronics continues, which accounts for the highest % of revenue with YoY growth of 27%, and (2) continuous improvement in China pneumatic demand environment, as YoY growth across nearly all end-markets reached double digits except for the battery segment.
In 3Q26, AirTAC's revenue was Rmb2,427mn (-7% QoQ, +23% YoY)/NT$11,525mn (-5% QoQ, +40% YoY), which was 3% below GSe in NT$ terms; we believe this miss was mainly driven by the deceleration in YoY growth for the battery segment (Rmb340mn missed GSe of Rmb482mn), offsetting the better than expected contribution from electronics (Rmb671mn beat GSe of Rmb648mn) and energy lighting (Rmb81mn beat GSe of Rmb64mn). We now expect 3Q26 GM/OPM to reach 48.5/14.5%.
In terms of revenue growth by end-market segment for September (see Exhibit 1), the machine tool sector outgrew all other sectors (+35% YoY), followed by energy lighting (+30% YoY), electronics (+27% YoY), general machinery (+12% YoY), packaging (+11% YoY), automotive (+11% YoY), and battery (-10% YoY).
Chao Wang
+886(2)2730-4195 | kuanchao.wang@gs.com Goldman Sachs (Asia) L.L.C., Taipei Branch
Yuichiro Isayama
+81(3)4587-9806 | yuichiro.isayama@gs.com Goldman Sachs Japan Co., Ltd.
Al Wang
+886(2)2730-4081 | al.wang@gs.com Goldman Sachs (Asia) L.L.C., Taipei Branch e92c7a75ab8b4efbba794e6b187208c8
[讀者資訊已遮蔽]
Exhibit 1: Strength/weakness in major segments of AirTAC
in September
AirTAC's monthly revenue by segment at a glance
| End market | % of revenue | YoY (%) |
|---|---|---|
| General machinery | 5% | 12% |
| Auto | 11% | 11% |
| Machine tools | 8% | 35% |
| Textiles | 5% | 25% |
| Packaging | 8% | 11% |
| Electronics | 27% | 27% |
| Battery | 12% | -10% |
| Energylighting | 4% | 30% |
Revenue breakdown represents the contribution by each end-market customer for AirTAC's 'direct' sales, which represent more than 80%+ of its total revenue. Breakdown of distribution sales, which are c.20% of total sales, is not included in this data.
Source: Company data
For the month of October 2026, we estimate AirTAC's monthly revenue will decrease to Rmb729mn (-10% MoM, +16% YoY)/NT$3,447mn (-10% MoM, +28% YoY)
We expect October revenue will go down by 10% MoM to Rmb729mn/NT$3,447mn, mainly due to 19% fewer working days in Mainland China. However, we expect to see improvement in daily pneumatic revenue (Rmb32.3mn in Oct vs. Rmb 29.4mn in Sept) as the improvement in daily pneumatic revenue is driven by the strong growth from key customers, including electronics, followed by machine tools and battery, and we further expect demand to improve following the end of low season.
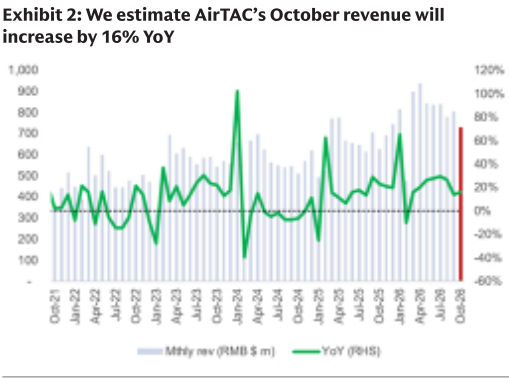
Source: Company data, Goldman Sachs Global Investment Research
Earnings and TP revisions
We revise down our 2026E earnings estimates by 1% to factor in actual 3Q26 revenue (revise down 2026 revenue by 1%). We revise down our 2027E/2028E earnings estimate by 1%/1% to factor in a more conservative assumption on battery and linear guide business (revise down AirTAC revenue by 1%/1% in 2027E/2028E). We continue to see the company focusing on cost control as well as experiencing a better product mix outlook, but we expect some offset by rising material cost (revise down 2026E/2028E OPM by 0.1/0.1ppt).
e92c7a75ab8b4efbba794e6b187208c8
[讀者資訊已遮蔽]
Maintain our Buy rating on AirTAC, with a new 12m TP of NT$1,895 (from NT$1,925), based on an unchanged target P/E of 26x on 2027 EPS.
Exhibit 3: Earnings revision table
| AirTAC P&L (NT$ mn) | 2026E New | 2026E Old | Diff. | 2027E New | 2027E Old | Diff. | 2028E New | 2028E Old | Diff. |
|---|---|---|---|---|---|---|---|---|---|
| Sales | 45,096 | 45,644 | -1% | 52,655 | 53,446 | -1% | 59,393 | 60,126 | |
| Gross Profit | 21,925 | 22,216 | -1% | 26,057 | 26,443 | -1% | 29,821 | 30,144 | |
| EBIT | 15,192 | 15,400 | -1% | 18,541 | 18,814 | 1% | 21,487 | 21,708 | |
| Net Income | 12,225 | 12,389 | -1% | 14,587 | 14,800 | -1% | 16,884 | 17,057 | 1% |
| EPS (NT$) | 61.12 | 61.95 | 72.93 | 74.00 | 84.42 | 85.29 | |||
| Ratio analysis | |||||||||
| Gross margin | 48.6% | 48.7% | -0.1pp | 49.5% | 49.5% | 0.0pp | 50.2% | 50.1% | 0.1pp |
| EBIT margin | 33.7% | 33.7% | -0.1pp | 35.2% | 35.2% | 0.0pp | 36.2% | 36.1% | 0.1pp |
| Net margin | 27.1% | 27.1% | 0.0pp | 27.7% | 27.7% | 0.0pp | 28.4% | 28.4% | 0.1pp |
Source: Goldman Sachs Global Investment Research
Exhibit 4: P&L table
| NT$mn | 1Q25 | 2Q25 | 3Q25 | 4Q25 | 1Q26 | 2Q26 | 3Q26E | 4Q26E | 1Q27E | 2Q27E | 3Q27E | 4Q27E | 2024 | 2025 | 2026E | 2027E | 2028E |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Revenue | 8,096 | 8,953 | 8,246 | 9,035 | 10,014 | 12,164 | 11.512 | 11,406 | 11,939 | 13,918 | 13,610 | 13,188 | 30,660 | 34,330 | 45,096 | 52,655 | 59,393 |
| Gross profit | 3,574 | 4,119 | 3,797 | 4,292 | 4,804 | 6,048 | 5,580 | 5,493 | 5,777 | 7,059 | 6,798 | 6,423 | 14,314 | 15,782 | 21,925 | 26,057 | 29,821 |
| Operating expense | (1,302) | (1,387) | (1,336) | (1,469) | (1,479) | (1,783) | (1,669) | (1,802) | (1,755) | (1,879) | (1,851) | (2,031) | (5,298) | (5,494) | (6,734) | (7,516) | (8,335) |
| Operating income | 2,272 | 2,732 | 2,460 | 2,823 | 3,325 | 4,265 | 3,911 | 3,691 | 4,022 | 5,180 | 4,947 | 4,392 | 9.016 | 10,288 | 15,192 | 18.541 | 21,487 |
| Pretax income | 2,466 | 2,570 | 2,652 | 2,957 | 3,424 | 4,238 | 4,061 | 3.841 | 4,062 | 5,220 | 4,987 | 4,432 | 9,634 | 10,645 | 15,564 | 18,701 | 21,647 |
| Taxes expense | (530) | (533) | (553) | (629) | (753) | (927) | (853) | (807) | (894) | (1.148) | (1,097) | (975) | (2,010) | (2,246) | (3,340) | (4,114) | (4,762) |
| Net income | 1,936 | 2,037 | 2,099 | 2,328 | 2,671 | 3,311 | 3,208 | 3,034 | 3,168 | 4,072 | 3,890 | 3,457 | 7,624 | 8,400 | 12,225 | 14,587 | 16,884 |
| EPS, NT$ | 9.68 | 10.19 | 10.50 | 11.64 | 13.35 | 16.55 | 16.04 | 15.17 | 15.84 | 20.36 | 19.45 | 17.29 | 38.12 | 42.00 | 61.12 | 72.93 | 84.42 |
| Ratio analysis and assumption | Ratio analysis and assumption | Ratio analysis and assumption | Ratio analysis and assumption | Ratio analysis and assumption | Ratio analysis and assumption | Ratio analysis and assumption | Ratio analysis and assumption | Ratio analysis and assumption | Ratio analysis and assumption | Ratio analysis and assumption | Ratio analysis and assumption | Ratio analysis and assumption | Ratio analysis and assumption | Ratio analysis and assumption | Ratio analysis and assumption | Ratio analysis and assumption | Ratio analysis and assumption |
| As % of sales | |||||||||||||||||
| Gross margin | 44.1% | 46.0% | 46.0% | 47.5% | 48.0% | 49.7% | 48.5% | 48.2% | 48.4% | 50.7% | 50.0% | 48.7% | 46.7% | 46.0% | 48.6% | 49.5% | 50.2% |
| Operating expense ratio | 16.1% | 15.5% | 16.2% | 16.3% | 14.8% | 14.7% | 14.5% | 15.8% | 14.7% | 13.5% | 13.6% | 15.4% | 17.3% | 16.0% | 14.9% | 14.3% | 14.0% |
| Operating margin | 28.1% | 30.5% | 29.8% | 31.2% | 33.2% | 35.1% | 34.0% | 32.4% | 33.7% | 37.2% | 36.4% | 33.3% | 29.4% | 30.0% | 33.7% | 35.2% | 36.2% |
| Net margin | 23.9% | 22.8% | 25.5% | 25.8% | 26.7% | 27.2% | 27.9% | 26.6% | 26.5% | 29.3% | 28.6% | 26.2% | 24.9% | 24.5% | 27.1% | 27.7% | 28.4% |
| QoQ growth (%) | QoQ growth (%) | QoQ growth (%) | QoQ growth (%) | QoQ growth (%) | QoQ growth (%) | QoQ growth (%) | QoQ growth (%) | QoQ growth (%) | QoQ growth (%) | QoQ growth (%) | QoQ growth (%) | QoQ growth (%) | QoQ growth (%) | QoQ growth (%) | QoQ growth (%) | QoQ growth (%) | QoQ growth (%) |
| Revenue | %9 | 11% | -8% | 10% | 11% | 21% | %9 | -1% | 5% | 17% | -2% | -3% | |||||
| Gross profit | 2% | 15% | %8- | 13% | 12% | 26% | -8% | -2% | 5% | 22% | -4% | %9- | |||||
| Operating income | 6% | 20% | -10% | 15% | 18% | 28% | -8% | %9- | %6 | 29% | -4% | -11% | |||||
| Net income | 7% | 5% | 3% | 11% | 15% | 24% | %% | -5% | 4% | 29% | -4% | -11% | |||||
| YoY growth (%) | YoY growth (%) | YoY growth (%) | YoY growth (%) | YoY growth (%) | YoY growth (%) | YoY growth (%) | YoY growth (%) | YoY growth (%) | YoY growth (%) | YoY growth (%) | YoY growth (%) | YoY growth (%) | YoY growth (%) | YoY growth (%) | YoY growth (%) | YoY growth (%) | YoY growth (%) |
| Revenue | 12% | 6% | 12% | 18% | 24% | 36% | 40% | 26% | 19% | 14% | 18% | 16% | 3% | 12% | 31% | 17% | 13% |
| Gross profit | 5% | 3% | 11% | 22% | 34% | 47% | 47% | 28% | 20% | 17% | 22% | 17% | 4% | 10% | 39% | 19% | 14% |
| OPEX | 6% | 3% | -1% | 7% | 14% | 29% | 25% | 23% | 19% | 5% | 11% | 13% | %8 | 4% | 23% | 12% | 11% |
| Operating income | 5% | 3% | 19% | 32% | 46% | 56% | %6% | 31% | 21% | 21% | 26% | 19% | 2% | 14% | 48% | 22% | 16% |
| Net income | 6% | -10% | 21% | 29% | 38% | 63% | 53% | 30% | 19% | 23% | 21% | 14% | 9% | 10% | 46% | 19% | 16% |
Source: Company data, Goldman Sachs Global Investment Research
Investment view: Accelerating monthly YoY from smaller segments could be a surprise. Maintain positive view on AirTAC
We reiterate our Buy rating on AirTAC as we continue to believe the company is a key beneficiary of the factory automation/industrial automation localization trend in mainland China, and we expect the company will also benefit from the prolonged upcycle supported by the ongoing government stimulus policies. We see multiple key end-segments' performance tracking ahead of the company's 2026 full year guidance of 20%+ YoY growth (see here), with battery/textile/machine tools/electronics delivering 55%/46%/41%/23% YTD YoY growth while total revenue in Rmb is tracking at 23% YTD YoY growth.
We continue to see solid monthly YoY growth from smaller segments, such as energy lighting and textile. However, the battery segment, which is the key growth driver in 2025 (with 89% YoY in 2025), is seeing its first negative monthly YoY growth since Oct 2024, while other major contribution sectors, such as electronics and automotive are seeing decelerating monthly YoY growth. As a result, we remain cautious on the potential of exaggerated orders (including advance or duplicate orders) despite new orders intake continuing to outpace shipments, and we will continue to monitor the underlying end-demand closely.
e92c7a75ab8b4efbba794e6b187208c8
[讀者資訊已遮蔽]
Maintain Buy on AirTAC with a lower 12m TP of NT$1,895 (from NT$1,925).
Investment Thesis - AirTAC
AirTAC is the 2nd-largest pneumatic supplier in mainland China with 28% market share in 2025, outpacing most local competitors, owing to its low-cost yet high quality product, and service quality reputation in most key cities in mainland China. We forecast its market share will reach 30% in 2026E and expect AirTAC to be the structural winner in a deflationary market, due to its: (1) strong market growth and leadership: AirTAC continues to expand its market share in mainland China driven by competitive pricing that is more than 10% lower vs. international peers (with 45%+ GM / 30-35% OPM) and high demand elasticity among mainland China customers; and (2) superior cost structure and financial health: with best-in-class cash cost and a solid balance sheet, featuring positive net cash over FCF since 2023/2024, we believe AirTAC is well-equipped to weather industry downturns and capitalize on market restructuring.
Overall, we believe AirTAC will see better revenue/profitability in the long term given its share gainer position in the China pneumatic market and potential to gain share in the linear guide market (improved demand in the next 1-2 years). This should lead to strengthened valuation, vs. its recent trading range (trading below its 10-year avg. P/E multiple). We are Buy rated on AirTAC.
Price target risks and methodology - AirTAC
Valuation methodology: Our 12m TP of NT$1,895 is based on a target P/E of 26.0x on our 2027E EPS (0.25x STDV above avg of the last pneumatic upcycle).
Key downside risks: (1) Stronger competition from peers; (2) sharper-than-expected Rmb depreciation, and (3) a longer-than-expected end-market demand downtrend in mainland China.
| 1590.TW | 12m Price Target: NT$1,895.00 | 12m Price Target: NT$1,895.00 | Price: NT$1,210.00 | Price: NT$1,210.00 | Upside: 56.6% | Upside: 56.6% |
|---|---|---|---|---|---|---|
| Buy | Buy | GS Forecast | GS Forecast | GS Forecast | GS Forecast | GS Forecast |
| Market cap: NT$231.4bn / $7.2bn Enterprise value: NT$221.0bn / $6.9bn 3m ADTV: NT$1.2bn / $36.0mn Taiwan Taiwan Electronic M&A Leases incl. in net debt & | Market cap: NT$231.4bn / $7.2bn Enterprise value: NT$221.0bn / $6.9bn 3m ADTV: NT$1.2bn / $36.0mn Taiwan Taiwan Electronic M&A Leases incl. in net debt & | Components Rank: 3 EV?: No Revenue (NT$ mn) New Revenue (NT$ mn) Old EBITDA (NT$ mn) EPS (NT$) New EPS (NT$) Old P/E (X) P/B (X) Dividend yield (%) CROCI (%) EPS (NT$) | 12/25 34,329.9 34,329.9 12,865.9 42.00 42.00 20.9 3.3 3.3 19.2 6/26 16.55 | 12/26E 45,096.4 45,643.9 17,437.2 61.12 61.95 19.8 4.3 3.3 23.8 9/26E 16.04 | 12/27E 52,655.1 53,446.1 20,950.4 72.93 74.00 16.6 3.9 3.9 27.5 12/26E 15.17 | 12/28E 59,393.1 60,126.1 23,958.4 84.42 85.29 14.3 3.6 4.5 30.0 3/27E 15.84 |
Source: Company data, Goldman Sachs Research estimates, FactSet. Price as of 12 Oct 2026 close.
e92c7a75ab8b4efbba794e6b187208c8
[讀者資訊已遮蔽]