PDF 原檔:報告_Daiwa_富世達6805_20261007_original.pdf
圖片清單(已驗證 2026-10-09)
| 檔名 | size | 分類 | 親眼所見內容 |
|---|---|---|---|
報告_Daiwa_富世達6805_20261007_001.png |
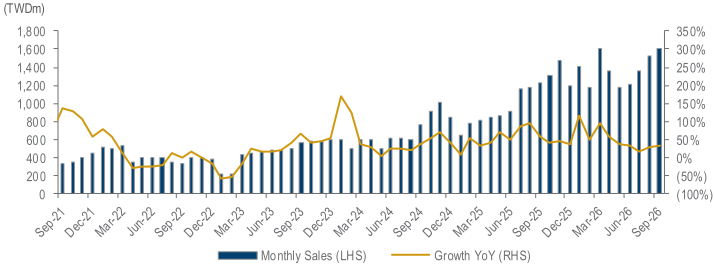
52KB | 真資料圖 | 富世達月營收柱狀圖+YoY成長率折線(Sep-21至Sep-26),2025年底起營收與成長率快速墊高,9月為歷史新高 |
原始內容
Fositek Corp (6805 TT)
Share price (6 Oct): TWD2,415.00
12-mth rating: Buy (1)
3Q26 revenue largely in line with expectations
Helen Chien
(886) 2 8758 6254 helen.chien@daiwacm-cathay.com.tw
Neil Teng, CFA
(886) 2 8758 6256
neil.teng@daiwacm-cathay.com.tw Summary: Fositek reported its September 2026 monthly revenue before market hours on 7 October 2026. Revenue was TWD1,613m (+5.6% MoM and +32.2% YoY; +47.3% YoY for 9M26), a record high. Its 3Q26 revenue accounted for 98.9% and 98.2% of our and consensus forecasts, respectively.
We have a Buy (1) rating and 12-month TP of TWD2,615, based on a target PER of 32x applied to our one-year-forward EPS estimate. For more information on the company, please refer to our latest flash note, Investor meeting: positive tone over 2026-27 outlook, published on 4 August 2026.
What's the impact
- 3Q26 revenue largely in line with expectations. On 7 October, Fositek reported record-high monthly revenue of TWD1,613m for September 2026 (+5.6% MoM and +32.2% YoY; +47.3% YoY for 9M26). Its 3Q26 revenue of TWD4,502m (+20.4% QoQ and +26.2% YoY) was also a record high and accounted for 98.9% of our forecast (TWD4,550m, +21.7% QoQ and +27.6% YoY) and 98.2% of the Bloomberg consensus forecast.
Fositek: consolidated monthly sales
Source: Company
- 4Q26 revenue should grow further QoQ. We expect revenue to increase in 4Q26 vs. 3Q26, with gross margin expanding QoQ as GPU and ASIC projects ramp up in 2H26. With rising liquid cooling penetration, broader product applications, and increased QD shipments per rack, we expect revenue to grow 40.9% YoY in 2026E and 41.7% YoY in 2027E.
What we recommend
We have a Buy (1) rating and 12-month TP of TWD2,615, based on a target PER of 32x applied to our one-year-forward EPS estimate. Based on our 2026/27E EPS, the stock is currently trading at PERs of 40.9x/26.5x, vs. its past-3-year trading range of 9-42x. Key downside risks: lower-than-expected market share with key clients, slower-than-expected penetration rate of foldable phones, and geopolitical risks.
In the interests of timeliness, this document has not been edited.
7 October 2026
Information Technology: Taiwan