PDF 原檔:報告_Citi_雙鴻3324_20261007_original.pdf
圖片清單(已驗證 2026-10-09)
| 檔名 | size | 分類 | 親眼所見內容 |
|---|---|---|---|
報告_Citi_雙鴻3324_20261007_001.png |
61KB | 真資料圖 | 「Figure 1. Auras – Quarterly sales trend」季營收柱狀圖(NT$mn)+QoQ/YoY折線,1Q21至3Q26E |
報告_Citi_雙鴻3324_20261007_002.png |
73KB | 真資料圖 | 「Figure 2. Auras – Monthly sales trend」月營收柱狀圖(TWDm)+MoM/YoY折線,Jan-24至Sep-26 |
報告_Citi_雙鴻3324_20261007_003.png |
157KB | 真資料圖 | 雙鴻(3324.TWO)評等與目標價歷史走勢圖+表格(2025-12-11至2026-09-17,目標價由1,525逐步調升至1,800),下半頁為Short-Term View/Catalyst Watch 標註圖 |
原始內容
[讀者資訊已遮蔽] citi
07 Oct 2026 07:48:31 ET │ 11 pages
Auras Technology (3324.TWO)
Sep-26 Sales Dip on Timing Instead of Demand; 4Q26E Ramp Intact
CITI'S TAKE
Auras reported Sep-26 revenues of NT$2.9bn (-8% MoM/+23% YoY), bringing 3Q26 revenues to NT$9.8bn (+13% QoQ/+64% YoY). 3Q26 revenues missed Citi/cons forecasts by 4%/4% and slightly below mgmt.'s previous guidance of at least 15% QoQ growth. We attribute the shortfall to clients deferring pull-ins to 4Q26 and to Thailand flooding, which disrupted outbound logistics, rather than to weaker end demand. We now expect stronger momentum in 4Q26E, driven by Vera Rubin manifolds shipments starting in Oct, the liquid cooling version of ASIC ramp from Nov, and recovery of deferred shipments. These should support 4Q26E outlook and leave room for upside to our current estimates. We view the Sep dip as a timing issue and expect monthly revenue momentum to reaccelerate from Oct. Maintain Buy.
Flash | Research
| Buy Price (07 Oct 26 15:00) | NT$1,525.00 |
|---|---|
| Target price | NT$1,800.00 |
| Expected share price return | 18.0% |
| Expected dividend yield | 1.7% |
| Expected total return | 19.7% |
| Market Cap | NT$141,942M |
| US$4,465M |
Michael Hung AC
+886-2-8726-9092 michael.hung@citi.com
Laura (Chia Yi) Chen +886-2-8726-9090 laura.cy.chen@citi.com
See Appendix A-1 for Analyst Certification, Important Disclosures and Research Analyst Affiliations [讀者資訊已遮蔽]
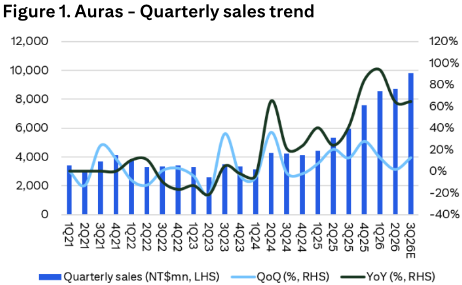
© 2026 Citigroup Inc. No redistribution without Citigroup's written permission. Source: Company Reports, Citi Research
© 2026 Citigroup Inc. No redistribution without Citigroup's written permission. Source: Company Reports, Citi Research [讀者資訊已遮蔽]
Auras Technology
Valuation
We value Auras using a PE-based approach, reflecting its accelerating earnings trajectory and rising share in liquid cooling market of AI servers. Our TP of NT$1,800 is based on 20x 2027E EPS, which we believe is justified given the company's expanding server revenue base, deeper engagement with CSP customers, and broader product portfolio across cold plates, CDMs, and CDUs.
Risks
This stock is High Risk based upon our quantitative model, but assigning a High Risk rating is not supported in our view by other qualitative factors such as rapid RVL progress and Thailand expansion, and so a High Risk rating has not been applied. Key downside risks to our investment thesis and target price include: 1) slower adoption of liquid cooling; 2) heightened price competition; 3) lower-than-expected share in liquid cooling components; and 4) emerging alternative cooling technologies.
[讀者資訊已遮蔽] If you are visually impaired and would like to speak to a Citi representative regarding the details of the graphics in this document, please call USA 1-888-500-5008 (TTY: 711), from outside the US +1-210-677-3788