PDF 原檔:報告_BofA_台積電2330_20261012_original.pdf
圖片清單(已驗證 2026-10-13)
33 張抽圖皆 ≥25KB 且逐張 Read 確認,全數為真資料圖(BofA 內部圖表樣式,無封面/logo/文字卡)。
| 檔名 | size | 分類 | 親眼所見內容 |
|---|---|---|---|
_001.png |
60KB | 真資料圖 | TSMC's wafer pricing (US$) 與 YoY:advanced vs mature/specialty 柱狀+折線圖,2015-2028E |
_002.png |
53KB | 真資料圖 | TSMC 5nm 及以下 wafer consumption/supply/utilization 柱狀+折線圖,1Q22-3Q28 |
_003.png |
64KB | 真資料圖 | TSMC's wafer pricing + advanced node pricing premium vs mature/specialty,2015-2028E |
_004.png |
49KB | 真資料圖 | TSMC 3nm wafer consumption/supply/utilization,3Q23-3Q28 |
_005.png |
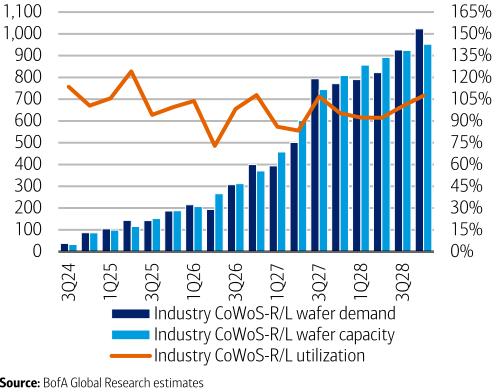
39KB | 真資料圖 | Industry CoWoS-R/L wafer supply/demand 與 utilization,3Q24-3Q28 |
_006.png |
59KB | 真資料圖 | CoWoS demand by customer(Nvidia/AMD/Broadcom/Google/Amazon/Meta等)2020-2028,含 YoY |
_007.png |
90KB | 真資料圖 | TSMC's wafer pricing (US$) 與 YoY,另一版本,2015-2028E |
_008.png |
42KB | 真資料圖 | TSMC's wafer pricing + advanced node premium vs mature,2015-2028E |
_009.png |
63KB | 真資料圖 | Foundry industry sales & capex、capital intensity,2007-2027 |
_010.png |
61KB | 真資料圖 | Back-end industry sales & capex、capital intensity,2007-2027 |
_011.png |
61KB | 真資料圖 | TSMC total capex vs equipment capex per k WPM,2010-2028 |
_012.png |
104KB | 真資料圖 | TSMC revenue & capex、YoY & capital intensity,2010-2028 |
_013.png |
77KB | 真資料圖 | TSMC capex breakdown by node(advanced/specialty/others),2010-2028,含 YoY |
_014.png |
29KB | 真資料圖 | TSMC capacity by node 年底值(20/16/12nm、7nm family、3nm family、N2 family、A16),2020-2028E |
_015.png |
46KB | 真資料圖 | TSMC capacity 組成:Mature/Specialty vs Advanced node,及 advanced % of total,2020-2028E |
_016.png |
65KB | 真資料圖 | TSMC 5nm 及以下 wafer consumption/supply/utilization,1Q22-3Q28(長期版) |
_017.png |
68KB | 真資料圖 | Major advanced demand at TSMC by product(Server CPU/AI accelerator/Mobile SoC等)k WPY,2022-2028,含 Server CPU YoY |
_018.png |
43KB | 真資料圖 | Major 5nm 及以下 wafer demand mix at TSMC(%組成),2022-2028 |
_019.png |
53KB | 真資料圖 | TSMC 3nm wafer consumption/supply/utilization,3Q23-3Q28 |
_020.png |
69KB | 真資料圖 | TSMC 3nm wafer consumption by customer(Apple/Mediatek/Qualcomm/Nvidia/AMD/Intel/Broadcom等),1Q23-4Q28 |
_021.png |
79KB | 真資料圖 | CoWoS demand by customer(k WPY)與 YoY,2020-2028(另一分類版本) |
_022.png |
54KB | 真資料圖 | Industry CoWoS-R/L wafer demand/capacity/utilization,3Q24-3Q28 |
_023.png |
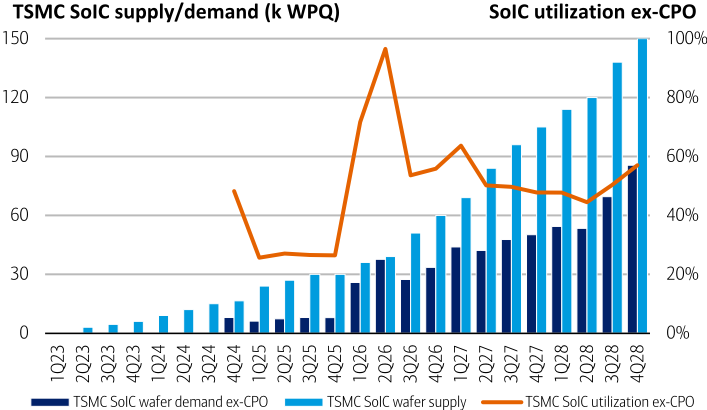
58KB | 真資料圖 | TSMC SoIC supply/demand(k WPQ)與 utilization ex-CPO,1Q23-4Q28 |
_024.png |
25KB | 真資料圖 | Transistor density(MTr/mm^2)比較:TSMC N3/N3E/N2P/A16/A12 vs Intel 3/18A/18A-P/14A |
_025.png |
57KB | 真資料圖 | 大盤估值圖:weekly closing price 搭配 10x/13x/16x/21x/26x P/E 乘數線,Sep16-Sep26 |
_026.png |
52KB | 真資料圖 | TSMC P/E band 歷史走勢(Avg P/E=16x,±1/2 std dev),Sep16-Sep26 |
_027.png |
73KB | 真資料圖 | TSMC NTM forward P/E vs TSMC 客戶估值溢價(均溢價 22%) |
_028.png |
75KB | 真資料圖 | TSMC NTM forward P/E vs TSMC 主要 HPC 客戶估值溢價(均溢價 53%) |
_029.png |
76KB | 真資料圖 | Consensus NTM EPS expectations 與 NTM P/E based on consensus,Jan15-Feb26 |
_030.png |
56KB | 真資料圖 | SOX P/E premium vs TSM ADR,SOX/TSM ADR forward P/E,Jan10-Jan26 |
_031.png |
72KB | 真資料圖 | TSMC common 與 ADR conversion price、ADR premium(均溢價 8%),Jan02-Jan26 |
_032.png |
56KB | 真資料圖 | TSMC 歷年目標價(PO, NT$)調整歷史圖,含分析師與日期標註,2024-2026 |
_033.png |
64KB | 真資料圖 | 同上 PO 歷史圖之 US$(ADR)版本,2024-2026 |
原始內容
Taiwan Semiconductor Manufacturing Co.
3Q26 earnings preview: steeper 2nm ramp lifting sales upside at resilient margins
Reiterate Rating: BUY | PO: 3,260 TWD | Price: 2,550 TWD
Solid HPC and flagship mobile pipeline solidifies 2H26
TSMC's 3Q26 sales were above street +18% QoQ in NT$ and reached US$46.7bn (vs. its guide of US$44.6-45.8bn) which we believe should be driven by the builds for Apple's mobile SoC and AMD's server CPU on 2nm along with multiple GPU and ASIC product refreshes migrating to 3nm. The mix upgrades could lift 4Q26 sales by +10-15% QoQ, putting it on track to the guidance for 40%+ YoY in '26. While utilization and pricing are favorable, GMs could hold steady in 3Q/4Q26 (BofAe 67.0%/67.8%) rather than expand (recent street 67-68%/68-69%) factoring dilution from 2nm and overseas fab ramps.
Tight supply enables greater value capture and investment
On solid AI demand outlook, TSMC's capex should be on track to its lifted guidance of US$60-64bn in '26 (BofAe US$63bn). The investment could see another surge in '27 (BofAe US$83bn) for further N3, N2, A16 and CoWoS-L expansion and new technologies ramp (e.g. CoPoS and CPO). The tool makers' modest price hike could require TSMC to spend 10% more capex though should be reflected in its value when the capacity starts production in '28 on top of a 5-10% leading edge ASP lift in 1Q27 on supply tightness.
Checkpoints: AI demand, capex & competition/partnership
1) TSMC's view on cloud AI investment amid rate hike + challenging FCF, 2) comment on the market and its growth and capex commitment, 3) update on the competition and collaboration (see Exhibit 29 for our analysis on Terafab/SpaceX) and US investment.
AI-led earnings outlook firmer; valuation should catch up
We lift our 26/27/28 EPS by 2-9% to NT$112/NT$161/NT$203 and keep our Buy rating on TSMC and raise PO to NT$3,260/US$620 on 20x '27E P/E. Its current valuation is undemanding at 16x '27E P/E (vs. its long term 11-21x) backed by its advanced technology leadership.
| Estimates (Dec) (NT$) | 2024A | 2025A | 2026E | 2027E | 2028E |
|---|---|---|---|---|---|
| Net Income (Adjusted - mn) | 1,173,268 | 1,717,886 | 2,916,545 | 4,184,666 | 5,276,738 |
| EPS | 45.24 | 66.24 | 112.46 | 161.36 | 203.48 |
| EPS Change (YoY) | 39.9% | 46.4% | 69.8% | 43.5% | 26.1% |
| Consensus EPS (Visible Alpha) | 107.72 | 146.40 | 183.73 | ||
| Dividend / Share | 18.00 | 21.50 | 24.00 | 24.00 | 24.00 |
| Free Cash Flow / Share | 33.55 | 38.66 | 69.93 | 96.56 | 138.58 |
| ADR EPS (US$) | 7.04 | 10.62 | 17.61 | 25.27 | 31.86 |
| ADR Dividend / Share (US$) | 2.80 | 3.45 | 3.76 | 3.76 | 3.76 |
| Valuation (Dec) | |||||
| P/E | 56.36x | 38.49x | 22.67x | 15.80x | 12.53x |
| Dividend Yield | 0.706% | 0.843% | 0.941% | 0.941% | 0.941% |
| EV / EBITDA* | 31.70x | 23.98x | 15.14x | 10.62x | 8.61x |
| Free Cash Flow Yield* | 1.32% | 1.52% | 2.74% | 3.79% | 5.43% |
| * For full definitions of iQmethod SM measures, see page 24. |
This research report provides general information only. No part of this report may be used or reproduced or quoted in any manner whatsoever in Taiwan by the press or other persons without the express written consent of BofA Securities.
>> Employed by a non-US affiliate of BofAS and is not registered/qualified as a research analyst under the FINRA rules.
Refer to "Other Important Disclosures" for information on certain BofA Securities entities that take responsibility for the information herein in particular jurisdictions.
BofA Securities does and seeks to do business with issuers covered in its research reports. As a result, investors should be aware that the firm may have a conflict of interest that could affect the objectivity of this report. Investors should consider this report as only a single factor in making their investment decision.
Refer to important disclosures on page 25 to 28. Analyst Certification on page 22. Price
12 October 2026
Equity
| Key Changes (NT$) | Previous | Current |
|---|---|---|
| Price Obj. | 3,100.00 | 3,260.00 |
| 2026E EPS | 110.20 | 112.46 |
| 2027E EPS | 155.85 | 161.36 |
| 2028E EPS | 187.89 | 203.48 |
| 2026E EBITDA (m) | 4,083,248.5 | 4,155,258.3 |
| 2027E EBITDA (m) | 5,745,945.1 | 5,927,984.9 |
| 2028E EBITDA (m) | 6,793,119.0 | 7,307,336.4 |
Haas Liu >> Research Analyst Merrill Lynch (Taiwan) +886 2 2376 3727 haas.liu@bofa.com
Mike Yang >> Research Analyst Merrill Lynch (Taiwan) +886 2 2376 3729 mike.c.yang@bofa.com
Robert Cheng >> Research Analyst Merrill Lynch (Taiwan) +886 2 2376 3731
Cathy Hsu >> Research Analyst Merrill Lynch (Taiwan) +886 2 2376 3726 cathy.hsu3@bofa.com
| Stock Data | |
|---|---|
| Price (Common / ADR) | 2,550 TWD / 453.31 USD |
| Price Objective | 3,260 TWD / 620.00 USD |
| Date Established | 12-Oct-2026 / 12-Oct-2026 |
| Investment Opinion | B-1-7 / B-1-7 |
| 52-Week Range | 1,375 TWD-2,590 TWD |
| Market Value (mn) | 2,070,984 USD |
| Market Value (mn) | 66,127,544 TWD |
| Shares Outstanding (mn) | 25,932.4 / 5,186.5 |
| Average Daily Value (mn) | 1,767 USD |
| Free Float | 92.2% |
| BofA Ticker / Exchange | TSMWF / TAI |
| BofA Ticker / Exchange | TSM / NYS |
| Bloomberg / Reuters | 2330 TT / 2330.TW |
| ROE (2026E) | 43.8% |
| Net Dbt to Eqty (Dec-2025A) | -37.3% |
iQprofile SM Taiwan Semiconductor Manufacturing Co.
| Key Income Statement Data (Dec) | 2024A | 2025A | 2026E | 2027E | 2028E |
|---|---|---|---|---|---|
| (NT$ Millions) | |||||
| Sales | 2,894,308 | 3,809,054 | 5,551,264 | 7,790,371 | 9,656,518 |
| Gross Profit | 1,624,354 | 2,281,294 | 3,733,064 | 5,371,382 | 6,653,851 |
| Sell General & Admin Expense | (96,888) | (99,222) | (110,416) | (131,671) | (145,125) |
| Operating Profit | 1,322,053 | 1,936,092 | 3,323,549 | 4,866,929 | 6,097,850 |
| Net Interest & Other Income | 83,786 | 105,574 | 193,432 | 175,282 | 261,328 |
| Associates | NA | NA | NA | NA | NA |
| Pretax Income | 1,405,839 | 2,041,666 | 3,516,980 | 5,042,211 | 6,359,178 |
| Tax (expense) / Benefit | (233,407) | (326,266) | (601,062) | (860,526) | (1,086,199) |
| Net Income (Adjusted) | 1,173,268 | 1,717,886 | 2,916,545 | 4,184,666 | 5,276,738 |
| Average Fully Diluted Shares Outstanding | 25,932 | 25,933 | 25,933 | 25,933 | 25,933 |
| Key Cash Flow Statement Data | |||||
| Net Income | 1,173,268 | 1,717,886 | 2,916,545 | 4,184,666 | 5,276,738 |
| Depreciation & Amortization | 662,797 | 688,096 | 831,710 | 1,061,056 | 1,209,487 |
| Change in Working Capital | (143,010) | (72,100) | (102,100) | (161,737) | (113,049) |
| Deferred Taxation Charge | NA | NA | NA | NA | NA |
| Other Adjustments, Net | 133,123 | (58,907) | 154,974 | 77,281 | 95,310 |
| Cash Flow from Operations | 1,826,177 | 2,274,976 | 3,801,128 | 5,161,266 | 6,468,486 |
| Capital Expenditure | (956,007) | (1,272,411) | (1,987,705) | (2,657,265) | (2,874,767) |
| (Acquisition) / Disposal of Investments | (58,000) | (37,014) | (42,792) | 7,594 | 475 |
| Other Cash Inflow / (Outflow) | 149,164 | 165,031 | 76,317 | 411 | 2,594 |
| Cash Flow from Investing | (864,843) | (1,144,393) | (1,954,180) | (2,649,259) | (2,871,699) |
| Shares Issue / (Repurchase) | (9) | (2) | (2) | 0 | 0 |
| Cost of Dividends Paid | (337,129) | (440,855) | (531,614) | (622,377) | (622,377) |
| Cash Flow from Financing | (346,301) | (440,345) | (564,551) | (624,253) | (622,956) |
| Free Cash Flow | 870,171 | 1,002,565 | 1,813,423 | 2,504,002 | 3,593,719 |
| Net Debt | (1,403,733) | (2,035,607) | (3,419,363) | (5,306,194) | (8,280,429) |
| Change in Net Debt | (556,872) | (647,079) | (1,277,442) | (1,889,630) | (2,974,410) |
| Key Balance Sheet Data | |||||
| Property, Plant & Equipment | 3,234,980 | 3,691,841 | 5,015,572 | 6,578,562 | 8,037,977 |
| Other Non-Current Assets | 368,606 | 424,052 | 481,020 | 478,736 | 478,718 |
| Trade Receivables | 272,088 | 281,791 | 341,182 | 430,143 | 481,869 |
| Cash & Equivalents | 2,422,020 | 3,068,595 | 4,463,340 | 6,348,294 | 9,321,950 |
| Other Current Assets | 394,245 | 466,745 | 527,406 | 634,603 | 734,512 |
| Total Assets | 6,691,938 | 7,933,024 | 10,828,520 | 14,470,338 | 19,055,027 |
| Long-Term Debt | 958,429 | 896,062 | 895,282 | 892,832 | 892,526 |
| Other Non-Current Liabilities | 145,408 | 118,147 | 176,911 | 209,050 | 236,572 |
| Short-Term Debt | 59,858 | 136,926 | 148,695 | 149,268 | 148,995 |
| Other Current Liabilities | 1,204,667 | 1,321,094 | 1,682,008 | 1,732,227 | 1,786,768 |
| Total Liabilities | 2,368,362 | 2,472,229 | 2,902,896 | 2,983,378 | 3,064,861 |
| Total Equity | 4,323,576 | 5,460,795 | 7,925,624 | 11,486,960 | 15,990,166 |
| Total Equity & Liabilities | 6,691,938 | 7,933,024 | 10,828,520 | 14,470,338 | 19,055,027 |
| iQmethod SM - Bus Performance* | |||||
| Return On Capital Employed | 23.2% | 28.4% | 36.3% | 38.3% | 35.2% |
| Return On Equity | 30.3% | 35.4% | 43.8% | 43.3% | 38.5% |
| Operating Margin | 45.7% | 50.8% | 59.9% | 62.5% | 63.1% |
| EBITDA Margin | 68.6% | 68.9% | 74.9% | 76.1% | 75.7% |
| iQmethod SM - Quality of Earnings* | |||||
| Cash Realization Ratio | 1.6x | 1.3x | 1.3x | 1.2x | 1.2x |
| Asset Replacement Ratio | 1.4x | 1.8x | 2.4x | 2.5x | 2.4x |
| Tax Rate (Reported) | 16.6% | 16.0% | 17.1% | 17.1% | 17.1% |
| Net Debt-to-Equity Ratio | -32.5% | -37.3% | -43.1% | -46.2% | -51.8% |
| Interest Cover | NM | NM | NM | NM | NM |
Key Metrics
- For full definitions of iQmethod SM measures, see page 24.
Company Sector
Semiconductors
Company Description
TSMC was founded in 1987 and is listed in Taiwan (2330TT) and the US (TSM/NYS).TSMC is the largest and global leader in integrated circuit (IC) manufacturing. As a build-to-order foundry, it provides a wide range of valueadd activities: IC manufacturing, mask-making, IC design services, turnkey solutions, and process development. We attribute its success to its proven, winning business model, unparalleled scale advantage, optimized execution, and technology scope and depth. 5 shares = 1 ADR.
Investment Rationale
The ongoing semi content growth in mobile, rise of artificial intelligence (AI), and proliferation of Internet of Things (IoT) should result in sustainable upside in aggregate computing power globally. TSMC, as the leading contract manufacturer of semiconductor chips, is in a good position to capitalize. We are structurally positive on TSMC and expect it to sustain over 15% growth with rising FCF from 2026 onwards.
| Stock Data | |
|---|---|
| Shares / ADR | 5.00 |
| Price to Book Value | 8.4x |
| Key Changes | Current | |
|---|---|---|
| (US$) Price Obj. | Previous 590.00 | 620.00 |
| 2026E EPS | 17.26 | 17.61 |
| 2027E EPS | 24.40 | 25.27 |
| 2028E EPS | 29.42 | 31.86 |
lül
Focus charts and tables
Exhibit 1: TSMC's wafer pricing by advanced vs. mature nodes
TSMC's wafer pricing by advanced vs. mature nodes
Source: BofA Global Research estimates
BofA GLOBAL RESEARCH
Exhibit 3: TSMC 5nm and below wafer consumption/supply/utilization
Utilization of 5nm and blow to remain high
Exhibit 2: TSMC's wafer pricing gap for advanced vs. mature nodes
TSMC's advanced node pricing is now 9x higher than mature ones
BofA GLOBAL RESEARCH
Exhibit 4: TSMC 3nm wafer consumption/supply/utilization
TSMC 3nm to see utilization staying close to full
Source: Company Data, BofA Global Research estimates
Exhibit 5: Industry CoWoS-R/L supply/demand
CoWoS-R/L utilization should stay at high levels
Industry CoWoS-R/L wafer supply/demand (k WPQ) CoWoS-R/L utilization
Source: BofA Global Research estimates
il
Source: Company Data, BofA Global Research estimates
Exhibit 6: Industry CoWoS demand
CoWoS demand should remain strong through 2028
BofA GLOBAL RESEARCH
BofA GLOBAL RESEARCH
BofA GLOBAL RESEARCH
BofA GLOBAL RESEARCH
3Q26 sales topped guidance; GMs tracking well but recent street could be too bullish
We profile our expectation for TSMC's 3Q26 earnings on October 15 th . 3Q26 sales were reported +18% QoQ in NT$, above BofAe/street expectations of +14%/+13% QoQ. Based on the average FX of NT$31.99/US$ (vs. its NT$32US$ guide), its sales in US$ term would be US$46.7bn, also above its guidance range of US$44.6-45.8bn. we believe the strength is led by strong ramp on 2nm potentially growing to 11% of its sales in 3Q26 (vs. 3% in 2Q26) for Apple's builds for its product launches and surging demand for AMD's Venice server CPU. These growth drivers on the node are supplemented by the incremental inventory stocking from Mediatek and Qualcomm for their flagship smartphone SoCs albeit at a low base and below seasonal due to weak Android demand.
On top of the 2nm scale up, we expect the utilization for 5nm and 3nm to stay above 100% backed by the continued HPC/AI build strength especially with multiple product upgrades including 1) accelerators (GPUs and ASICs): strong demand for Nvidia's Rubin GPU, AMD's MI400, AWS's Trainium3 ramp and initial ramp for Google's TPUv8t/i more than offsetting a mild wind down in Google's Ironwood TPU, 2) CPUs: solid demand for general purpose servers and AI data centers as noted in our deep dive report quantifying CPU demand through '30 across x86 (AMD's Turin CPUs) and ARM based CPUs (e.g. Nvidia's Vera CPU, Google's Axion CPU, AWS Graviton CPU along with incremental contribution from Microsoft Cobalt CPU) and 3) networking switch: more and faster data transmission in the complex AI data centers requires more advanced networking switch solutions from Nvidia/Mellanox, Broadcom and Marvell.
The company's better than expected sales in 3Q26 backed by healthy shipment and pricing trend on the advanced nodes should be supportive to its GMs. However, in contrast to the recent aggressive street expectations of 67-68% GMs in 3Q26, we only model it at the high-end of its guidance of 65-67%, balancing more favorable utilization and gradual 3nm depreciation roll off partially offset by a 3-4% GMs dilution from 2nm ramp which we believe is driver for the incremental sales during the quarter.
Exhibit 7: TSMC 3Q26-4Q26 and 2026-27 estimates BofAe vs. street
We lift our EPS estimates for '26/27 to NT$112.47/NT$161.37
| 3Q26E - BofAe | 3Q26E - BofA Old | 3Q26E - Street | 4Q26E - BofAe | 4Q26E - Old | 4Q26E - Street | 2026E - BofAe | 2026E - Old | 2026E - Street | 2027E - BofAe | 2027E - Old | 2027E - Street | |
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Sales (NT$mn) | $1,494,243 $1,447,447 $1,452,942 $1,652,537 $1,625,222 $1,593,320 $5,551,264 $5,477,153 $5,434,682 $7,790,371 $7,711,575 $7,323,473 | $1,494,243 $1,447,447 $1,452,942 $1,652,537 $1,625,222 $1,593,320 $5,551,264 $5,477,153 $5,434,682 $7,790,371 $7,711,575 $7,323,473 | $1,494,243 $1,447,447 $1,452,942 $1,652,537 $1,625,222 $1,593,320 $5,551,264 $5,477,153 $5,434,682 $7,790,371 $7,711,575 $7,323,473 | $1,494,243 $1,447,447 $1,452,942 $1,652,537 $1,625,222 $1,593,320 $5,551,264 $5,477,153 $5,434,682 $7,790,371 $7,711,575 $7,323,473 | $1,494,243 $1,447,447 $1,452,942 $1,652,537 $1,625,222 $1,593,320 $5,551,264 $5,477,153 $5,434,682 $7,790,371 $7,711,575 $7,323,473 | $1,494,243 $1,447,447 $1,452,942 $1,652,537 $1,625,222 $1,593,320 $5,551,264 $5,477,153 $5,434,682 $7,790,371 $7,711,575 $7,323,473 | $1,494,243 $1,447,447 $1,452,942 $1,652,537 $1,625,222 $1,593,320 $5,551,264 $5,477,153 $5,434,682 $7,790,371 $7,711,575 $7,323,473 | $1,494,243 $1,447,447 $1,452,942 $1,652,537 $1,625,222 $1,593,320 $5,551,264 $5,477,153 $5,434,682 $7,790,371 $7,711,575 $7,323,473 | $1,494,243 $1,447,447 $1,452,942 $1,652,537 $1,625,222 $1,593,320 $5,551,264 $5,477,153 $5,434,682 $7,790,371 $7,711,575 $7,323,473 | $1,494,243 $1,447,447 $1,452,942 $1,652,537 $1,625,222 $1,593,320 $5,551,264 $5,477,153 $5,434,682 $7,790,371 $7,711,575 $7,323,473 | $1,494,243 $1,447,447 $1,452,942 $1,652,537 $1,625,222 $1,593,320 $5,551,264 $5,477,153 $5,434,682 $7,790,371 $7,711,575 $7,323,473 | $1,494,243 $1,447,447 $1,452,942 $1,652,537 $1,625,222 $1,593,320 $5,551,264 $5,477,153 $5,434,682 $7,790,371 $7,711,575 $7,323,473 |
| Sales QoQ / YoY (%) | 17.6% | 13.9% | 14.4% | 10.6% | 12.3% | 9.7% | 45.7% | 43.8% | 42.7% | 40.3% | 40.8% | 34.8% |
| Gross profit (NT$mn) | $1,000,465 67.0% | $961,703 66.4% | $963,882 66.3% | $1,120,993 67.8% | $1,081,275 66.5% | $1,050,189 65.9% | $3,733,064 67.2% | $3,654,584 66.7% | $3,595,640 66.2% | $5,371,382 68.9% | $5,191,137 67.3% | $4,844,770 66.2% |
| GMs (%) | $891,981 | $854,803 59.1% | $842,101 58.0% | $1,005,999 | $971,167 | $4,866,929 | $4,232,893 57.8% | |||||
| Operating profit (NT$mn) OpMs (%) | 59.7% | 60.9% | 59.8% | $922,996 57.9% | $3,323,549 59.9% | $3,251,539 59.4% | $3,154,235 58.0% | 62.5% | $4,689,032 60.8% | |||
| Pretax profit Pretax margins (%) | 61.8% | 61.3% | 60.2% | 63.1% | 62.1% | 59.8% | $3,516,980 63.4% | 62.9% | 61.8% | 64.7% | $4,870,519 63.2% | 60.5% |
| (NT$mn) | $924,044 | $887,585 | $873,964 | $1,042,707 | $1,008,753 | $952,145 | $3,446,566 | $3,357,001 | $5,042,211 | $4,433,422 | ||
| -$786,143 | ||||||||||||
| Tax expense (NT$mn) | -$154,691 | -$148,588 | -$148,114 | -$174,556 | -$168,872 | -$159,351 | -$600,435 | -$588,648 | -$597,694 | -$857,545 | -$828,896 | |
| Tax rate (%) | 16.7% | 16.7% | 16.9% | 16.7% | 16.7% | 16.7% | 17.1% | 17.1% | 17.8% | 17.0% | 17.0% | 17.7% |
| Net profit (NT$mn) | $769,353 | $738,997 | $725,850 | $868,150 | $839,881 | $792,794 | $2,916,545 | $2,857,919 | $2,759,307 | $4,184,666 | $4,041,623 | $3,647,279 |
| Net margins (%) | 51.5% | 51.1% | 50.0% | 52.5% | 51.7% | 49.8% | 52.5% | 52.2% | 50.8% | 53.7% | 52.4% | 49.8% |
| EPS (NT$) | $29.67 | $28.50 | $28.08 | $33.48 | $32.39 | $30.67 | $112.47 | $110.21 | $107.37 | $161.37 | $155.85 | $140.92 |
Source: BofA Global Research estimates, Bloomberg
BofA GLOBAL RESEARCH
lül
HPC/Apple lifting 4Q26 sales outlook; resilient GM expectation but below street
For 4Q26, based on its slightly above +40% YoY full year sales guide, TSMC's sales could grow 10-15% QoQ (BofAe +11%), better than its 10-year seasonality of 7% QoQ even off a high base from 1Q-3Q26. The blended ASPs strength (BofAe +11% QoQ) should be the key driver for 4Q26 sales as shipment mix continues to shift toward advanced nodes, with revenue from 5nm and below processes representing 75% of the company's sales (vs. 66%/71% in 2Q/3Q26). Specifically, 2nm with 15%+ higher wafer pricing than 3nm could further grow its contribution to 18% of TSMC's sales during the quarter. On the other hand, we model a stable wafer shipment (BofAe +9%/-5% QoQ for advanced/mature nodes), balancing HPC demand strength and Apple's seasonal chipset builds for its new product launches and a modest drop on the specialty process output and effective capacity loss due to equipment movement for the node conversion.
While the blended pricing is even more favorable and utilization on the advanced and mature nodes in general stay healthy, we model a relatively stable GMs only up to ~67.8% levels in 4Q26 (vs. recent street and investors' expectations at 68-69%). The key factors we consider as mildly negative offset would be 1) higher depreciation: +25-30% HoH in 2H26 due to more overseas and 2nm capacity ramp and 2) 2nm still going through yield learning curve and could see more meaningful impact in 4Q26 (vs. its 3-4% GMs dilution guide in 2H26) as the sales contribution grows.
Exhibit 8: Our 2026-28E earnings are 5-15% above consensus as we model a higher sales growth
TSMC 2026-28 estimates BofAe vs. Street
| 2026E - BofAe | 2026E - Street | 2026E - vs. street | 2027E - BofAe | 2027E - Street | 2027E - vs. street | 2028E - BofAe | 2028E - Street | 2028E - vs. street | |
|---|---|---|---|---|---|---|---|---|---|
| Sales (NT$mn) Sales QoQ / YoY (%) | $5,551,264 45.7% | $5,434,682 42.7% | 2% | $7,790,371 40.3% | $7,323,473 34.8% | 6% | $9,656,518 24.0% | $9,152,144 25.0% | 6% |
| Gross profit (NT$mn) GMs (%) | $3,733,064 67.2% | $3,595,640 66.2% | 4% 1% | $5,371,382 68.9% | $4,844,770 66.2% | 11% 3% | $6,653,851 68.9% | $6,033,826 65.9% | 10% 3% |
| Operating profit (NT$mn) OpMs (%) | $3,323,549 59.9% | $3,154,235 58.0% | 5% 2% | $4,866,929 62.5% | $4,232,893 57.8% | 15% 5% | $6,097,850 63.1% | $5,255,681 57.4% | 16% 6% |
| Pretax profit (NT$mn) Pretax margins (%) | $3,516,980 63.4% | $3,357,001 61.8% | 5% 2% | $5,042,211 64.7% | $4,433,422 60.5% | 14% 4% | $6,359,178 65.9% | $5,553,349 60.7% | 15% 5% |
| Tax expense (NT$mn) Tax rate (%) | -$600,435 17.1% | -$597,694 17.8% | 0% -1% | -$857,545 17.0% | -$786,143 17.7% | 9% -1% | -$1,082,440 17.0% | -$998,175 18.0% | 8% -1% |
| Net profit (NT$mn) Net margins (%) | $2,916,545 52.5% | $2,759,307 50.8% | 6% 2% | $4,184,666 53.7% | $3,647,279 49.8% | 15% 4% | $5,276,738 54.6% | $4,555,174 49.8% | 16% 5% |
| EPS (NT$) | $112.47 | $107.37 | 5% | $161.37 | $140.92 | 15% | $203.48 | $176.56 | 15% |
Source: BofA Global Research estimates, Bloomberg BofA GLOBAL RESEARCH
2026-27 sales and margins outlook solidified by healthy AI demand
Factoring in stronger CPU and AI GPU/ASIC demand outlook as noted in our Semicon Taiwan takeaways report where we updated our industry models, we are lifting our US$ sales expectation for TSMC in '26/'27 to +42%/+40% YoY respectively (vs. BofA prior +41%/+40% YoY). More importantly, with utilization staying tighter for longer along with inflationary cost pass through (e.g. equipment and consumables), TSMC should raise its advanced node and packaging pricing by 5-10% in the beginning of 2027 to reflect its value. This along with a mild 3-5% price hike on the mature nodes where the utilization is back to 90-95% as it optimizes the product mix following the strategic 6'/8' capacity retirement should lift its GMs to 67%/69% in 2026/27 (vs. BofA prior 67%/67%).
Exhibit 9: TSMC's wafer pricing by advanced vs. mature nodes TSMC's wafer pricing by advanced vs. mature nodes
Exhibit 10: TSMC's wafer pricing gap for advanced vs. mature nodes TSMC's advanced node pricing is now 9x higher than mature ones
Source: BofA Global Research estimates
Source: BofA Global Research estimates
BofA GLOBAL RESEARCH
Capex on track for lifted guide for 2026 and will grow 20%+ CAGR from '26-28
We lifted our front-end foundry industry capex growth expectation to 19%/26% YoY for '26/27 to US$86bn/US$108bn, supporting a CAGR of 16% from '26-28. This is mostly led by our higher expectation on TSMC's capex on stronger wafer demand on N3 and N2 from GPUs, ASICs, CPUs, networking switches and HBM base dies and initial ramp of A16, along with incremental spending reacceleration from tier 2 foundries.
Separately, we also raised the back-end packaging and testing industry spending estimates from 66%/36% YoY to 82%/21% YoY for '26/27 to US$27bn/US$33bn, supporting a CAGR of 15% from '26-28. The upward revision is driven by our higher expectation of TSMC's more aggressive capacity addition on CoWoS-R/L to accommodate more demand from its customers amid growing level of chipset complexity and reticle size and higher level of capacity readiness of SoIC for higher 3D packaging adoption for logic and memory dies integration and CPO. The more aggressive spending from ASE is set to grow by another 30-50% YoY in 2027 off a high base in 2026 on its own FoCoS capacity ramp and TSMC's CoWoS licensing.
BofA GLOBAL RESEARCH
il
Exhibit 11: Front-end sales, capex, and capital intensity
Front-end capex should reach US$86bn/US$108bn in '26/27
Exhibit 12: Back-end sales, capex, and capital intensity
Back-end capex should reach US$27bn/US$33bn in '26/27
Source: Company Data, BofA Global Research estimates, Bloomberg
BofA GLOBAL RESEARCH
Specifically on TSMC, based on our bottom up capacity analysis across front-end manufacturing and back-end packaging, TSMC's capex spending is tracking to US$63bn for 2026 (vs. its latest guidance of US$60-64bn) mostly skewed toward advanced frontend manufacturing including 55-60k WPM 3nm capacity addition, 60k WPM 2nm capacity ramp, initial 3-5k WPM A16 capacity installation. The back-end packaging investment should be largely driven by its CoWoS capacity growth while the spending on the equipment pull-in for CPO and CoPoS remains limited as most of the equipment are still under sampling process for qualification and meaningful shipment will be in 202728.
In addition to the earlier tool pull-in schedule due to tighter equipment supply with memory makers expanding, the fast-growing capex should reflect the rising cost per 1k WPM on the advanced nodes vs. mature nodes, with the equipment cost per 1k WPM advanced wafer capacity expansion has grown from US$156mn in 2023 to US$241mn in 2025. Even factoring in more common use of equipment on the advanced nodes, the capex/1k WPM advanced capacity could further rise by 20% to US$289mn in 2027 with the technology architecture upgrade.
On top of the investment in the core front-end manufacturing, we expect the company to slightly outspend in the back-end packaging and estimate it is at the upper half of its guidance for 10-20% total capex, mainly for more aggressive capacity expansion to meet its customers' demand amid growing competition from Intel's EMIB-T solution and technology innovation. On the other hand, the maintenance capex could be reduced for specialty technologies as the company gradually retires the equipment.
il
Source: Company Data, BofA Global Research estimates, Bloomberg
BofA GLOBAL RESEARCH
Exhibit 13: TSMC's total Capex vs. equipment spending per k WPM capacity addition
TSMC spend 1-2x more on 1k WPM expansion due to its shift to advanced nodes in recent years
TSMC's capex (US$mn) TSMC's equipment capex per k WPM (US$mn)
Source: Company Data, BofA Global Research estimates
BofA GLOBAL RESEARCH
Considering the capex required for further 3nm capacity expansion in the additional phases in its Tainan megafab, Arizona and the recently announced 2 nd fab in Kumamoto on strong AI/HPC/automotive demand, ramping scale for 2nm family including A16, R&D on A14 supplemented by multiple back-end packaging technologies in progress (e.g. CoWoS, CoPoS, SoIC, WMCM) and lower capex efficiency in its US operation, our bottom up model shows TSMC's capex could be US$83bn/US$90bn in 2027/28 at a CAGR of 20% CAGR from 2026-28.
Exhibit 14: TSMC's revenue and Capex trend
TSMC's sales should still outgrow Capex to keep its capital intensity manageable
BofA GLOBAL RESEARCH
Beyond the technology upgrades and capacity expansion, we would note the equipment price hike would drive additional spending required by TSMC in the next few years. Our feedback from the tool suppliers noted they plan to hike the price by 10-15% for the front-end manufacturing equipment and 5-10% for the back-end packaging equipment effective from 2027 to reflect higher component and labor cost.
il With TSMC's stronger bargaining power against the equipment supply chain vs. its peers, it should be able to fully pass on the ~10% higher nominal capex to its customers by lifting its foundry pricing when the tools are delivered for its production ramp in 2H27, setting up a good start for the pricing outlook in 2028.
While the surge in headline capex hike could lead to concern on accelerating depreciation, we estimate it will only grow at 21% CAGR from 2026-28 due to modestly higher portion of the spending towards facility and clean room with much longer depreciation cycle than equipment. This should keep the depreciation still undergrowing its sales of +32% CAGR, sustaining GMs expansion to 68-69% levels by 2028.
Exhibit 15: TSMC Capex spending breakdown by technology TSMC spends the most on advanced front-end but packaging is outgrowing
BofA GLOBAL RESEARCH
We keep our Buy rating on TSMC and lift PO from NT$3,100 to NT$3,260 on unchanged 20x '27E P/E and US$ADR PO from $590 to $620. Our EPS for 2026/27/28E are now NT$112/161/203 (vs. NT$110/156/188 prior) as we factor in stronger CPU and AI GPU/ASIC demand outlook. Its current valuation seems undemanding at 16x '27E P/E (vs. its long term P/E average of 11-21x).
il
Exhibit 16: TSMC's depreciation trend TSMC's depreciation growth will be led by equipment
YoY TSMC's depreciation breakdown (NT$mn)
$1,400,000
$1,200,000
$1,000,000
$800,000
$600,000
$400,000
$200,000
$0
-$200,000
2012
2010
2014
2016
Office depreciation
175%
150%
125%
100%
75%
50%
25%
0%
-25%
2024
2022
2026
2028
Buildings depreciation
Equipment depreciation Equipment depreciation YoY
Buildings depreciation YoY
Office depreciation YoY
Source: Company Data, BofA Global Research estimates BofA GLOBAL RESEARCH
2020
2018
Capacity expansion accelerates across advanced front-end and back-end
As TSMC is in the process to retire a portion of its equipment on 6', 8' and mature 12' processes while still adding the capacity on the advanced nodes, we estimate the company's total front-end manufacturing capacity will drop by 2% YoY in 2026.
Exhibit 17: TSMC's year-end capacity by node for 20nm and below
TSMC will expand aggressively on 3nm and 2nm through 2027
TSMC's year-end capacityby node 20nm and below (k WPM, 12" equivalent)
Exhibit 18: TSMC's advanced node capacity as % of its installed base TSMC's advanced nodes will reach 40% of its total capacity
TSMC's capacity (k WPM, 12" equivalent) TSMC's 7nm and below nodes % of total capacity
900
The trend could be more stable into 2027-28 as TSMC strives to optimize its capacity mix and across node conversion to accommodate its customers' demand especially on the leading-edge technologies, with its advanced capacity set to grow by 10% CAGR from 2025-28 balanced by the mature capacity reduction at -8% CAGR.
Based on our estimate, TSMC's capacity for 7nm and below nodes will grow from 320k WPM per month in 2023 to ~700k WPM by 2028 at a 16% CAGR, through expansion and efficient conversion from higher equipment commonality, cross technology planning and AI productivity gains (e.g. tool idle time and chamber cleaning schedule optimization). This will also support the mix of 7nm and below capacity climb toward 40-45% of its total capacity (vs. 24% in 2023). By region, we expect the capacity expansion through 2027 to enable its overseas fabs to account for 17% of TSMC's total capacity by 2028 (vs. 7% in 2020) and similarly for the advanced node capacity (vs. ~0% in 2023), mainly in Arizona and Kumamoto.
Specifically, we believe the company is on track to its target on 25% CAGR capacity expansion for its 5nm and 3nm from '22-27. We model its 3nm capacity will reach 190k/230k WPM by 4Q26/27. On N2 family, TSMC plans to grow capacity by 70% CAGR from '26-28, with 1 st year ramp delivering 45% more capacity vs. 3nm as it rolls out 5 fabs at once.
BofA GLOBAL RESEARCH
lül
Exhibit 19: TSMC 5nm and below wafer consumption/supply/utilization
Utilization of 5nm and blow to remain high
BofA GLOBAL RESEARCH
On the demand, with 5nm and 3nm generating ~50% of TSMC's revenue in 2025, we analyze the supply and demand landscape through our bottom-up capacity model and wafer consumption by the company's major customers for their major products on these nodes. Based on our estimate, the utilization for 5nm and below nodes could stay high at least 90% if we only consider the effective capacity which is especially important during the period of frequent capacity conversion and new node ramp in the next few years.
Exhibit 21: Major 5nm and below wafer demand at TSMC
Server CPU demand outgrows overall major advanced chipsets Server CPU accounts for 13% in 2028
Exhibit 22: Major 5nm and below wafer demand mix at TSMC
Major 5nm and below waferdemand mix at TSMC
Source: BofA Global Research estimates
Source: BofA Global Research estimates
il
BofA GLOBAL RESEARCH
BofA GLOBAL RESEARCH
Exhibit 20: TSMC 3nm wafer consumption/supply/utilization
TSMC 3nm to see utilization staying close to full
Source: Company Data, BofA Global Research estimates
BofA GLOBAL RESEARCH
We would note 3nm, as a sweet spot for high performance computing, networking and flagship smartphone chipsets, could see the utilization staying close to full even with continued expansion on strong project pipeline, sustaining continued price hike even in 2027 following the price surge in 2025-26. The node could be even more profitable from 2028-29 when the fixed cost starts rolling off following 5 year depreciation cycle.
Exhibit 23: TSMC 3nm wafer consumption by customers
Mediatek/Qualcomm/Nvidia should remain the largest customers following Apple's migration to 2nm
TSMC 3nm wafer consumption (k WPM)
Source: BofA Global Research estimates
BofA GLOBAL RESEARCH
On the back-end packaging, with surging server CPU demand on top of the already strong order backlog for GPUs and ASICs, we estimate the industry's CoWoS supply will need to grow by 52% CAGR from 2026-28. TSMC will still lead the capacity expansion from 120k WPM in 4Q26 to 210k WPM in 4Q27, while the OSATs will also grow their portion of the supply with ASE and Amkor adding capacity to 70-75k+ WPM (vs. 30-35k in 4Q26) and 25-30k WPM (vs. 15-20k by 4Q26) in 4Q27 respectively. Specifically, while TSMC should still lead the supply for complex GPU and ASIC packaging, ASE grows as a major 2 nd source with its capacity share growing from 18% of the industry in '26 to 29% in '28 and proven track record as the major CoWoS full process service provider for AMD's Venice server CPU.
lül
Exhibit 24: Industry CoWoS-R/L supply/demand
CoWoS-R/L utilization should stay at high levels
Industry CoWoS-R/L wafer supply/demand (k WPQ) CoWoS-R/L utilization
Exhibit 25: Industry CoWoS demand
CoWoS demand should remain strong through 2028
BofA GLOBAL RESEARCH
BofA GLOBAL RESEARCH
We estimate TSMC's SoIC capacity will reach 20k WPM by 4Q26 and will need to grow to 35k WPM by 4Q27 and further to 50k WPM by 4Q28 with the applications proliferating from AMD's GPUs to Apple's M-series CPUs in 2026, hyperscalers' customized ARM based server CPUs in 2027 and adoption by Nvidia for its Feynman GPU along with the inflection of CPO penetration in 2028.
Similar to CoWoS, the SoIC technology could be even more important for TSMC going forward and the capacity ramp could be steep given much faster data transmission required for the HPC chipsets across CPUs, GPUs, AI accelerators and networking switches. At full utilization, we estimate SoIC could contribute US$2.9bn annually to TSMC in 2028 (1% of the company's total sales)
Exhibit 26: TSMC SoIC supply/demand trend
TSMC's SoIC capacity will reach 20k WPM by 4Q26 and will need to grow to 35k WPM by 4Q27
Source: Company Data, BofA Global Research estimates
il
Solid technology roadmap and execution easing competition concern
TSMC is pursuing a dual track strategy for its front-end manufacturing, advancing the solution for both its consumer and HPC customers. The nodes targeted for consumer chipsets requiring cost efficiency and IP reuse will be introduced on an annual basis to match its customers' yearly product launch schedule. For the HPC applications, the company targets to roll out a new node with biennial cadence, supporting major leaps in performance, transistor density, and power density.
Exhibit 27: Front-end manufacturing roadmap comparison
TSMC's advanced node technology roadmap advancing faster vs. Intel and Samsung and has the widest offerings targeted for different applications
| Company | End Market / Segment | 2023 | 2024 | 2025 | 2026 | 2027 | 2028 | 2029 |
|---|---|---|---|---|---|---|---|---|
| TSMC | Data Center | N4P & N4X | N3X & N2 | N2P & A16 | N2X | A12 | ||
| TSMC | High-end consumer/mobile | N3 | N3E | N3P & N2 | N2P | N2U & A14 | A13 | |
| TSMC | Automotive | N5A | N3A | |||||
| TSMC | Mainstream | N4P | N4C | N3C | N2U | |||
| Intel Foundry | Data center and high-end client | 3 | 3 | 3 & 18A | 18A-P | 14A & 14A-E | ||
| Intel Foundry | Mature | 16 | 16-E | Intel/UMC 12 | ||||
| Samsung Foundry | Data Center | SF4P | SF4X | SF2X | SF2Z | |||
| Samsung Foundry | High-end consumer/mobile | SF4P | SF3 | SF2 | SF2P | SF2P+ | SF1.4 | |
| Samsung Foundry | Automotive | SF5A | SF4A | SF2A | ||||
| Samsung Foundry | Mainstream | SF4U |
Source: BofA Global Research estimates
This is evidenced in its N2 family and below nodes, with N2U ramping in '28 for mobile applications and A13 node in '29 which will be backward compatible to A14. It will also have A12 node in '29 integrated SPR to address power integrity and current delivery constraint suitable for AI/HPC systems. The strategy along with the continued expansion of the derivative offerings for main nodes should position TSMC well to defend its market share with its competitors claiming their progress on the advanced manufacturing.
Specifically, Intel's 18A has been in mass production since 4Q25 for its Panther Lake and Clearwater Forest chipsets though yield will not be fully fine tuned until 1Q27 at 2530k WPM capacity scale in its Oregon and Arizona fabs. The follow on derivative technology, 18A-P, has recently started risk production featuring 9% performance gains though may not enter into mass production until 2027 at the earliest.
Longer term, Intel's next major upgrade will be on 14A which is guided to start risk production in 2028 for commercialization in 2029. It is important to note A14 will be the first major node Intel provides with its external foundry customers and 0.9 PDK is targeted to be shipped in 4Q26.
For Samsung, at its recent SAFE Forum in 2Q26, the company reaffirmed four generations of 2nm roadmap, including SF2 which has been in production since 2025, SF2P in 2026, SF2P+ in 2027-28 and SF2X (no firm date). Notably, the previously announced derivative technologies, including SF2Z featuring backside power for HPC applications and SF2A for automotive applications, were not included in its latest roadmap which should be folded as part of its SF2P+ offerings. With a modest delay for its 2nm progress, the company also pushed out its SF1.4 mass production to 2029 (vs. original 2027).
On the capacity and yield planning for its advanced nodes, Samsung noted its SF2 yield is still at 50-60% levels but confirmed its SF2P+ tooling has been in installation through 2026 for mass production in 2027 in its Taylor fab. Its capacity expansion in the US along with the existing 20k WPM capacity on SF2 in Korea put the company's capacity installed base on the node at 35k WPM by the end of 2027.
BofA GLOBAL RESEARCH
il
Exhibit 28: TSMC's front-end manufacturing transistor density vs. Intel
TSMC is widening its transistor density advantage against Intel as technology advances
Source: BofA Global Research estimates
BofA GLOBAL RESEARCH
Based on the capacity planning and technology roadmap, we believe TSMC retains the leadership through its roadmap and yield execution and scale. Specifically, the company's transistor density has been outperforming by ~30% for its N3/N3E vs. Intel 3/18A. With similar production timing and targeted applications, we estimate the transistor density gap could be even widened to ~50%/~60% for TSMC's upcoming A16/A12 nodes when comparing with Intel 18A-P/14A.
In addition to delivering superior specs on the power, performance and area, TSMC's execution reliability has become self-reinforcing: superior yield and on-time delivery on the leading edge technologies win customer trust. The profitable business opportunity then translates the cash flow funds to the next leg of capex cycle required for further technology and capacity lead. In contrast to TSMC's 150-200k+ WPM capacity scale on every major node at mature yield, Samsung and Intel running their business at 15-20% of the company's scale at 60-70% yield is not sufficient to meet their own demand nor the stringent requirement from the external customers especially as the opportunity cost gets higher on the advanced manufacturing.
On the back-end packaging and testing solutions, TSMC provides its customers with higher complexity of the system level integration across advanced logic dies, CPO components and HBM through its CoWoS and SoIC technologies for the compute density and efficiency optimization. To accommodate larger size package, it is rolling out 5.5-reticle CoWoS in '26 with yield reaching 98%+ and will push the technology to 9.5x/14x reticle limit in '27/'28
Longer term, the company is developing SoW for up to 40-reticle packaging and CoPoS potentially for late '28 / early '29 mass deployment. The company is also upgrading CPO with COUPE solutions from PCB and substrate to interposer for 10x power efficiency uplift and 20x latency reduction though the contribution would still be limited based on our estimate at least through '27 before accelerating to 1% of its sales in '28 with more scale up switch adoption.
While CoPoS mass ramp is toward '29, the CoWoS upgrade at good yield should keep its position vs. Intel's EMIB-T currently at 80-85% pilot yield seeing risk of losing business if it fails to deliver 95%+ mass production yield by mid-'27.
il
SpaceX could be an anchor customer for TSMC, but not co-owning capacity/tech
On top of the competition risk from the incumbent players, the headline of Elon Musk's aggressiveness to build Terafab targeting long term 1 terawatt equivalent chipset capacity for AI compute deployment in the space term also triggers the investor concerns on TSMC's positioning. We believe the risk is overstated as there could be a delay in the qualification process of Intel's 18A for external customers and 14A due to IP and manufacturing flow issues based on the recent supply chain feedback. In addition, the equipment vendors also noted Terafab is only evaluating on equipment spec and potential procurement rather than placing firm orders. With extending equipment delivery lead time, this could put the company in an unfavorable position to receive tools for the initial production ramp in '29 it scheduled.
In the mid-term, Terafab's applications under Texas's JETI program earlier this year outlined ~US$119bn of planned investment across 4 phases from '26-36, with ~60% of it on tool procurement. The spending in '26-28 would be highly skewed toward facility construction before it starts to pull in US$6-8bn equipment per annum from '29-36.
We estimate the company will need to spend US$600mn+ for every 1k WPM expansion on the advanced nodes it targets in the US. Factoring the investment it targets to spend in the next decade, Terafab could only grow its capacity installed base by ~10k WPM per annum at maximum to 96k WPM front-end manufacturing capacity installed by '36, well below TSMC's scale, even if it can successfully deliver the technology roadmap through its own R&D effort and Intel partnership. This would prevent Terafab's operation from the economies of scale as the node migration continues, keeping TSMC as the major foundry partner for Tesla/SpaceX.
Exhibit 29: Wafer supply/demand analysis on Elon Musk's AI deployment target
With Terafab's near term delay and limited long term scale, TSMC will continue to be critical for Musk's ambitious AI compute deployment plan
Wafer supply/demand analysis on Elon Musk's AI deployment target
| SpaceX's annual orbital AI deployment target in 2028 (GW) SpaceX's annual orbital AI deployment target in 2029 (GW) Musk's long term target to deploy AI compute annual run rate (GW) | 10 100 1,000 |
|---|---|
| TDP of Nvidia's Feynman GPU (W) GPU die output per front-end wafer (units) | 6,000 55 |
| Wafer demand for Feynman compute die for SpaceX's in '28 (k WPM) Wafer demand for Feynman compute die for SpaceX's in '29 (k WPM) Wafer demand for Feynman compute die to meet Musk's LT target (k WPM) | 10 101 1,006 |
| TSMC's 3nm and below capacity in 2028 (k WPM) | 505 |
| Terafab advanced wafer capacity scale by 2028 (k WPM) Terafab capacity by 2036 based on its US$119bn investment plan (k WPM) | 0 96 |
Source: BofA Global Research estimates
We also analyze the wafer consumption from SpaceX's annual orbital AI deployment target in '28/'29 of 10GW/100GW and Musk's long term 1TW target. Assuming the compute it plans to deploy in '28-29 is all powered by the most advanced Nvidia's Feynman GPUs delivering 6kW per package, this would drive 1.7mn/16.7mn chipset demand in '28/'29 respectively which requires 10k/101k monthly advanced wafer production. From the supply perspective, as Feynman GPU will be built on TSMC's A16 node, the chipset demand should be fully accommodated. With limited support from Terafab, SpaceX in this scenario could become one of the largest customers for TSMC consuming ~20% of its advanced node capacity in '29 (vs. ~1% in '26 and ~2% in '28).
Longer term, Musk's ambitious target to deploy 1 terawatt AI compute power annually would consume 1mn+ wafers per month on the advanced nodes. To have higher level of the control on capacity sufficiency, Terafab could consider to partner with TSMC though the likelihood of TSMC licensing technology or operating a fab with Terafab holding a meaningful share should be low. Specifically, we would note TSMC's JV fab record is limited only with WaferTech, SSMC, VIS, JASM, ESMC and AVSM mostly on mature nodes and it did not co-own a fab with Apple who contributed ~21% of its revenue from '15-25 mostly on the advanced processes as it keeps full business control and preserves customer neutrality.
BofA GLOBAL RESEARCH
il
TSMC valuation reasonable and has room to re-rate with its HPC customers
Exhibit 30: TSMC's P/E valuation band
TSMC's share at 16x '27E P/E is undemanding
BofA GLOBAL RESEARCH
Exhibit 31: TSMC's valuation based on BofA estimates
TSMC's valuation of 16x '27E P/E is at the middle of its historical 10-21x range Sep 26
BofA GLOBAL RESEARCH
TSMC's current valuation remains well supported when viewed through both its historical context and its relative positioning vs. its customers. In the past decade, TSMC's forward P/E has averaged ~16x with a range of 10-21x through the cycles.
Exhibit 32: TSMC's P/E trend vs. its customers
TSMC customers' P/E is now at 45% premium to TSMC vs. 22% average
Exhibit 33: TSMC's P/E trend vs. its HPC customers
HPC fabless are the main driver for valuation premium at 100%
Source: BofA Global Research, Bloomberg
BofA GLOBAL RESEARCH
Source: BofA Global Research, Bloomberg
BofA GLOBAL RESEARCH
The relatively more modest valuation improvement for TSMC also contrasts with its customers' more pronounced re-ratings. Based on our analysis of forward P/E spreads, TSMC's major customers usually have a 22% average premium vs. TSMC in the long term though the current level is at 45%, suggesting TSMC's valuation has been lagging.
il Specifically, the valuation deviation for TSMC's HPC customers vs. the company has widened with 100-150% valuation premium vs. TSMC at this stage (vs. historical average of 53%). We believe this is driven by a surge in valuation for the direct beneficiaries from AI data center deployment, including the companies designing GPUs, ASICs and networking chipsets.
Exhibit 34: TSMC's consensus earnings vs. P/E trend TSMC's share price strength only driven by earnings upgrade so far
Source: BofA Global Research, Bloomberg
BofA GLOBAL RESEARCH
It is also noteworthy that, while TSMC's share performance since 2H23 has been solid, it is predominantly driven by the earnings upward revisions rather than multiple expansion. The company's NTM P/E has remained largely stable, only lifted to 18x in the past 2 years vs. its long-term ~17x levels. The company's ADR though has been performing better as it attracts a broader investor base vs. common share, with its premium still at 10% (vs. the long term average 8%) and at 20x 2027 consensus P/E.
With its firmer technology leadership, this should bode well for the company's earnings upgrade cycle and its share should also be re-rated at least 20x NTM P/E (24x P/E for ADR factoring the premium), back closer to its customers and the broader ecosystem.
lül
Exhibit 35: TSM ADR 1-year forward P/E vs. SOX premium
SOX index P/E is at -8% premium vs. TSM ADR
Source: BofA Global Research, Bloomberg
BofA GLOBAL RESEARCH
Exhibit 37: TSMC's quarterly and annual income statement
TSMC's quarterly and annual income statement
| (NT$bn, %) | 1Q26 | 2Q26E | 3Q26E | 4Q26E | 1Q27E | 2Q27E | 3Q27E | 4Q27E | 2025 | 2026E | 2027E | 2028E |
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Revenues | $1,134 | $1,270 | $1,494 | $1,653 | $1,703 | $1,811 | $2,065 | $2,212 | $3,809 | $5,551 | $7,790 | $9,657 |
| Cost of Sales | -$383 | -$410 | -$494 | -$532 | -$547 | -$584 | -$622 | -$666 | -$1,528 | -$1,818 | -$2,419 | -$3,003 |
| Gross Profit | $751 | $860 | $1,000 | $1,121 | $1,156 | $1,226 | $1,443 | $1,545 | $2,281 | $3,733 | $5,371 | $6,654 |
| Operating Expenses | -$92 | -$94 | -$108 | -$115 | -$118 | -$121 | -$131 | -$135 | -$345 | -$410 | -$504 | -$556 |
| Operating Income | $659 | $767 | $892 | $1,006 | $1,039 | $1,105 | $1,312 | $1,411 | $1,936 | $3,324 | $4,867 | $6,098 |
| Non-operating Income (Exp) | $29 | $96 | $32 | $37 | $39 | $41 | $45 | $50 | $106 | $193 | $175 | $261 |
| Pretax Income | $688 | $862 | $924 | $1,043 | $1,078 | $1,146 | $1,358 | $1,460 | $2,042 | $3,517 | $5,042 | $6,359 |
| Net tax | -$115 | -$156 | -$155 | -$175 | -$180 | -$207 | -$228 | -$245 | -$326 | -$601 | -$861 | -$1,086 |
| Net Income | $573 | $707 | $769 | $868 | $898 | $939 | $1,130 | $1,215 | $1,718 | $2,917 | $4,185 | $5,277 |
| Fully Diluted EPS - Local (NT$) | $22.08 | $27.25 | $29.67 | $33.48 | $34.65 | $36.24 | $43.59 | $46.88 | $66.24 | $112.46 | $161.36 | $203.48 |
| % of Revenue | ||||||||||||
| Gross Profit | 66.2 | 67.7 | 67.0 | 67.8 | 67.9 | 67.7 | 69.9 | 69.9 | 59.9 | 67.2 | 68.9 | 68.9 |
| Operating Expenses | -8.1 | -7.4 | -7.3 | -7.0 | -6.9 | -6.7 | -6.3 | -6.1 | -9.1 | -7.4 | -6.5 | -5.8 |
| Operating Income | 58.1 | 60.3 | 59.7 | 60.9 | 61.0 | 61.0 | 63.6 | 63.8 | 50.8 | 59.9 | 62.5 | 63.1 |
| Pretax Income | 60.6 | 67.9 | 61.8 | 63.1 | 63.3 | 63.3 | 65.8 | 66.0 | 53.6 | 63.4 | 64.7 | 65.9 |
| Net Income | 50.5 | 55.6 | 51.5 | 52.5 | 52.7 | 51.9 | 54.7 | 54.9 | 45.1 | 52.5 | 53.7 | 54.6 |
| QoQ Growth % | ||||||||||||
| Revenues | 8.4 | 12.0 | 17.6 | 10.6 | 3.1 | 6.3 | 14.0 | 7.1 | ||||
| Gross Profit | 15.2 | 14.5 | 16.3 | 12.0 | 3.1 | 6.1 | 17.7 | 7.1 | ||||
| Operating Income | 16.7 | 16.3 | 16.4 | 12.8 | 3.2 | 6.4 | 18.8 | 7.5 | ||||
| Net Income | 13.3 | 23.4 | 8.8 | 12.8 | 3.5 | 4.6 | 20.3 | 7.6 | ||||
| YoY Growth % | ||||||||||||
| Revenues | 35.1 | 36.0 | 50.9 | 58.0 | 50.2 | 42.5 | 38.2 | 33.8 | 31.6 | 45.7 | 40.3 | 24.0 |
| Gross Profit | 52.3 | 57.2 | 70.0 | 71.9 | 53.9 | 42.5 | 44.3 | 37.9 | 40.4 | 63.6 | 43.9 | 23.9 |
| Operating Income | 61.9 | 65.4 | 78.2 | 78.1 | 57.6 | 44.2 | 47.1 | 40.2 | 46.4 | 71.7 | 46.4 | 25.3 |
| Net Income | 58.8 | 77.8 | 70.2 | 71.6 | 56.7 | 32.9 | 46.9 | 40.0 | 46.4 | 69.8 | 43.5 | 26.1 |
| EPS | 58.3 | 77.4 | 70.1 | 71.7 | 56.9 | 33.0 | 46.9 | 40.0 | 46.4 | 69.8 | 43.5 | 26.1 |
Source: Company data, BofA Global Research
il
Exhibit 36: TSM ADR conversion price vs. common share and premium
TSM ADR premium is higher than common historical level at 10%
BofA GLOBAL RESEARCH
BofA GLOBAL RESEARCH
Exhibit 38: TSMC's quarterly and annual balance sheet
TSMC's quarterly and annual balance sheet
| (NT$bn) | 1Q26 | 2Q26E | 3Q26E | 4Q26E | 1Q27E | 2Q27E | 3Q27E | 4Q27E | 2025 | 2026E | 2027E | 2028E |
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Cash | $3,036 | $3,134 | $3,761 | $4,089 | $4,283 | $4,625 | $5,181 | $5,976 | $2,768 | $4,089 | $5,976 | $8,950 |
| Short Term Investment | $348 | $384 | $366 | $375 | $370 | $373 | $371 | $372 | $301 | $375 | $372 | $372 |
| Accounts receivable | $363 | $441 | $354 | $341 | $428 | $439 | $469 | $430 | $282 | $341 | $430 | $482 |
| Inventory | $311 | $386 | $366 | $357 | $422 | $445 | $474 | $457 | $288 | $357 | $457 | $552 |
| Other current assets | $207 | $221 | $157 | $171 | $187 | $189 | $185 | $178 | $179 | $171 | $178 | $182 |
| Current Assets | $4,266 | $4,566 | $5,005 | $5,332 | $5,690 | $6,071 | $6,680 | $7,413 | $3,817 | $5,332 | $7,413 | $10,538 |
| Long Term Investments | $167 | $228 | $197 | $213 | $205 | $209 | $207 | $208 | $172 | $213 | $208 | $207 |
| Fixed Assets | $3,955 | $4,303 | $4,587 | $5,016 | $5,417 | $5,824 | $6,211 | $6,579 | $3,692 | $5,016 | $6,579 | $8,038 |
| Other Assets | $274 | $279 | $269 | $268 | $273 | $272 | $270 | $271 | $252 | $268 | $271 | $271 |
| Long-term Assets | $4,395 | $4,810 | $5,053 | $5,497 | $5,894 | $6,305 | $6,689 | $7,057 | $4,116 | $5,497 | $7,057 | $8,517 |
| Total Assets | $8,661 | $9,376 | $10,057 | $10,829 | $11,584 | $12,376 | $13,369 | $14,470 | $7,933 | $10,829 | $14,470 | $19,055 |
| Short term loans | $0 | $0 | $0 | $0 | $0 | $0 | $0 | $0 | $0 | $0 | $0 | $0 |
| Notes & Accounts Payable | $100 | $111 | $97 | $102 | $121 | $130 | $137 | $137 | $84 | $102 | $137 | $175 |
| Current portion of long term debt | $156 | $167 | $134 | $149 | $152 | $150 | $146 | $149 | $137 | $149 | $149 | $149 |
| Other current Liabilities | $1,458 | $1,580 | $1,580 | $1,580 | $1,596 | $1,596 | $1,596 | $1,596 | $1,237 | $1,580 | $1,596 | $1,611 |
| Current Liabilities | $1,714 | $1,858 | $1,811 | $1,831 | $1,868 | $1,876 | $1,879 | $1,881 | $1,458 | $1,831 | $1,881 | $1,936 |
| Long term debt | $901 | $864 | $902 | $895 | $893 | $889 | $895 | $893 | $896 | $895 | $893 | $893 |
| Other non-current liabilities | $113 | $179 | $134 | $177 | $151 | $160 | $155 | $209 | $118 | $177 | $209 | $237 |
| Long-term Liabilities | $1,014 | $1,043 | $1,036 | $1,072 | $1,044 | $1,049 | $1,050 | $1,102 | $1,014 | $1,072 | $1,102 | $1,129 |
| Total Liabilities | $2,729 | $2,901 | $2,847 | $2,903 | $2,912 | $2,925 | $2,929 | $2,983 | $2,472 | $2,903 | $2,983 | $3,065 |
| Total parent shareholders' equity | $5,891 | $6,433 | $7,170 | $7,884 | $8,631 | $9,410 | $10,399 | $11,446 | $5,420 | $7,884 | $11,446 | $15,949 |
| Minority Interest | $41 | $42 | $40 | $41 | $41 | $41 | $41 | $41 | $41 | $41 | $41 | $41 |
| Total Liabilities and Equity | $8,661 | $9,376 | $10,057 | $10,829 | $11,584 | $12,376 | $13,369 | $14,470 | $7,933 | $10,829 | $14,470 | $19,055 |
BofA GLOBAL RESEARCH
Source: Company data, BofA Global Research
Exhibit 39: TSMC's quarterly and annual cash flow
TSMC's quarterly and annual cash flow
| (NT$bn) | 1Q26 | 2Q26E | 3Q26E | 4Q26E | 1Q27E | 2Q27E | 3Q27E | 4Q27E | 2025 | 2026E | 2027E | 2028E |
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Net Profit | $572 | $707 | $769 | $868 | $898 | $940 | $1,130 | $1,216 | $1,718 | $2,917 | $4,185 | $5,277 |
| Depreciation & Amortization | $165 | $199 | $233 | $235 | $244 | $255 | $265 | $297 | $688 | $832 | $1,061 | $1,209 |
| Change in Working Capital | -$118 | -$155 | $156 | $15 | -$150 | -$27 | -$48 | $63 | -$72 | -$102 | -$162 | -$113 |
| Other adjustment | $79 | $33 | $17 | $25 | $12 | $6 | $20 | $40 | -$59 | $155 | $77 | $95 |
| Operating Cash Flow | $699 | $783 | $1,176 | $1,143 | $1,005 | $1,173 | $1,368 | $1,615 | $2,275 | $3,801 | $5,161 | $6,468 |
| Capital Expenditure | -$351 | -$496 | -$497 | -$644 | -$664 | -$664 | -$664 | -$664 | -$1,272 | -$1,988 | -$2,657 | -$2,875 |
| Proceeds from sale of non-current assets | $2 | $0 | $1 | $1 | $1 | $1 | $1 | $1 | $1 | $3 | $3 | $3 |
| Acquisitions/Disposals of investments | -$30 | -$37 | $49 | -$24 | $12 | -$6 | $3 | -$2 | -$37 | -$43 | $8 | $0 |
| Other investment items | $22 | $40 | $10 | $0 | -$4 | $0 | $2 | $0 | $164 | $73 | -$3 | $0 |
| Investing Cash Flow | -$357 | -$493 | -$437 | -$667 | -$656 | -$669 | -$659 | -$666 | -$1,144 | -$1,954 | -$2,649 | -$2,872 |
| Net Share issue/repurchase | $0 | $0 | $0 | $0 | $0 | $0 | $0 | $0 | $0 | $0 | $0 | $0 |
| Dividends paid | -$130 | -$156 | -$117 | -$156 | -$156 | -$156 | -$156 | -$156 | -$467 | -$558 | -$622 | -$622 |
| Change in debt | $14 | -$22 | $5 | $8 | $0 | -$5 | $2 | $1 | $43 | $5 | -$2 | -$1 |
| Other financing cash flow | -$5 | -$7 | $0 | $0 | $0 | $0 | $0 | $0 | -$17 | -$12 | $0 | $0 |
| Financing Cash Flow | -$120 | -$185 | -$112 | -$148 | -$155 | -$161 | -$154 | -$154 | -$440 | -$565 | -$624 | -$623 |
| Net Change in Cash | $222 | $106 | $627 | $328 | $194 | $343 | $555 | $795 | $690 | $1,282 | $1,888 | $2,974 |
| Exchange effect | $46 | -$7 | $0 | $0 | $0 | $0 | $0 | $0 | -$50 | $38 | $0 | $0 |
| Cash, Beginning of Year | $2,768 | $3,036 | $3,134 | $3,761 | $4,089 | $4,283 | $4,625 | $5,181 | $2,128 | $2,768 | $4,089 | $5,976 |
| Cash, End of Year | $3,036 | $3,134 | $3,761 | $4,089 | $4,283 | $4,625 | $5,181 | $5,976 | $2,768 | $4,089 | $5,976 | $8,950 |
Source: Company data, BofA Global Research
BofA GLOBAL RESEARCH
lül
Exhibit 40: Terms and definitions
Glossary of abbreviations/acronyms
| Term | Definition |
|---|---|
| AI | Artificial Intelligence |
| AMD | Advanced Micro Devices |
| ASIC | Application Specific Integrated Circuit |
| AVSM | Advanced Vision Semiconductor Manufacturing |
| CoPoS | Chip-on-Panel-on-Substrate |
| CoWoS-L | Chip-on-Wafer-on-Substrate-Local Silicon Bridge |
| CoWoS-R | Chip-on-Wafer-on-Substrate-Redistribution Layer |
| CPO | Co-Packaged Optics |
| CPU | Central Processing Unit |
| EMIB | Embedded Multi-die Interconnect Bridge |
| ESMC | European Semiconductor Manufacturing Company |
| FoCoS | Fan-Out Chip on Substrate |
| GPU | Graphic Processing Unit |
| HBM | High Bandwidth Memory |
| HPC | High-Performance Computing |
| JASM | Japan Advanced Semiconductor Manufacturing |
| JV | Joint Venture |
| SoC | System on Chip |
| SoIC | System on Integrated Chips |
| SoW | System-on-Wafer |
| SPR | Super Power Rail |
| SSMC | Systems on Silicon Manufacturing Company |
| TPU | Tensor Processing Unit |
| VIS | Vanguard |
| WMCM | Wafer-level-multi-chip-module |
| WPM | Wafer per month |
Source: BofA Global Research
il BofA GLOBAL RESEARCH
Price objective basis & risk
Taiwan Semiconductor Manufacturing Co. (TSMWF / TSM)
Our PO for TSMC is NT$3,260 per share (US$620 per ADR), based on 20x 2027E P/E. TSMC's valuation has traded in the range of 10-26x PE from 2017. 20x is in the mid to high end of the historical range, above the average P/E of 16x. We think a PE above the average is justified given TSMC's enhanced industry position and mid-to-high 50% 5year CAGR in AI should underpin a rerating
Downside risks to our price objective are: (1) greater-than-expected slowdown in global smartphone/consumer electronics demand, (2) Intel's potential insourcing strategy and ambitions in foundry service, (3) execution risks on advanced nodes, and (4) higher than expected tariffs.